Let’s dig into the relative performance of ProFrac (NASDAQ: ACDC) and its peers as we unravel the now-completed Q2 oilfield services earnings season.
Oilfield services companies provide equipment, technology, and services enabling exploration and production activities, including drilling, completion, well intervention, and reservoir evaluation. Their fortunes closely track upstream capital spending cycles. Tailwinds include increased drilling activity during favorable commodity environments, demand for efficiency-enhancing technologies, and growing offshore and unconventional resource development. Headwinds include significant revenue volatility tied to oil and gas price swings and producer spending discipline. Intense competition pressures pricing and margins, while the energy transition may structurally reduce long-term demand. Workforce availability and technological disruption require continuous adaptation.
The 25 oilfield services stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 4.6%.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
ProFrac (NASDAQ: ACDC)
Operating one of the largest electric-powered fracturing fleets in North America, ProFrac (NASDAQ: ACDC) provides hydraulic fracturing services that help oil and gas companies extract hydrocarbons from underground shale formations.
ProFrac reported revenues of $498.1 million, flat year on year. This print exceeded analysts’ expectations by 5.3%. Overall, it was a satisfactory quarter for the company with a solid beat of analysts’ EBITDA estimates but a significant miss of analysts’ EPS estimates.
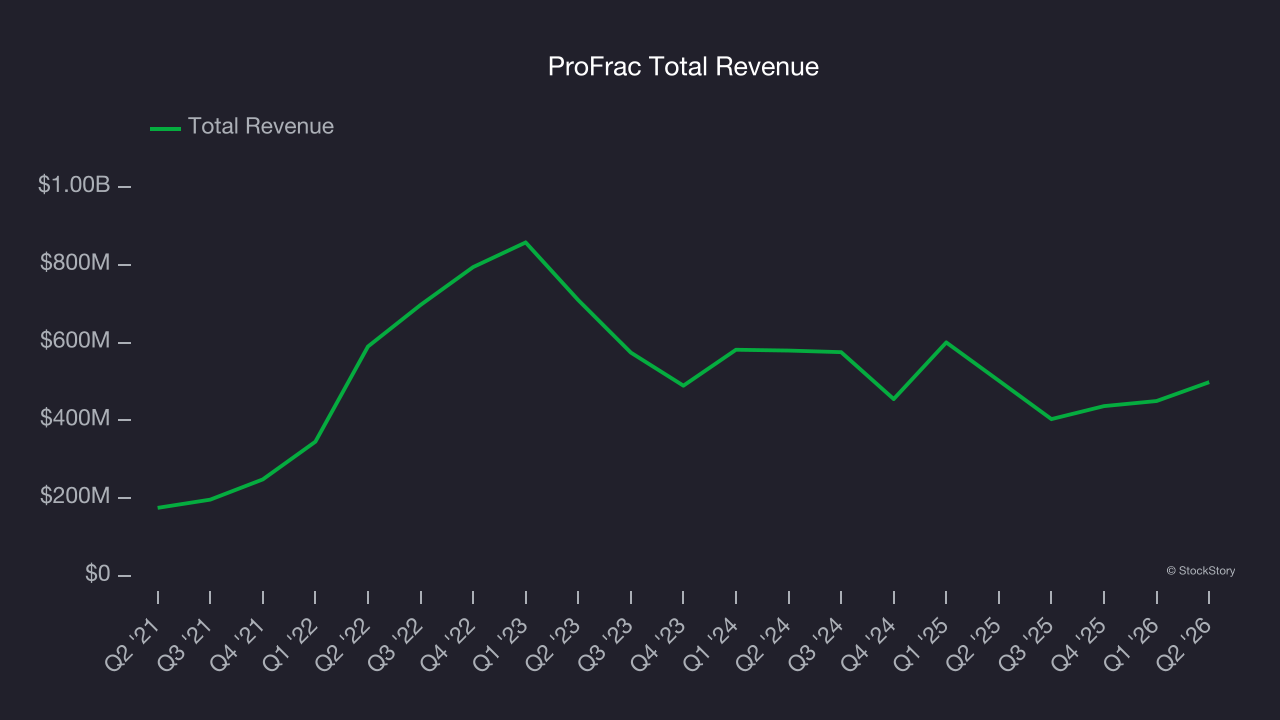
The market was likely pricing in the results, and the stock is flat since reporting. It currently trades at $4.48.
Is now the time to buy ProFrac? Access our full analysis of the earnings results here, it’s free.
Best Q2: NESR (NASDAQ: NESR)
Operating across 16 countries from Algeria to Indonesia, NESR (NASDAQ: NESR) provides oilfield services like hydraulic fracturing, cementing, and drilling to oil and gas companies.
NESR reported revenues of $520.8 million, up 59.1% year on year, outperforming analysts’ expectations by 17.8%. The business had an incredible quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
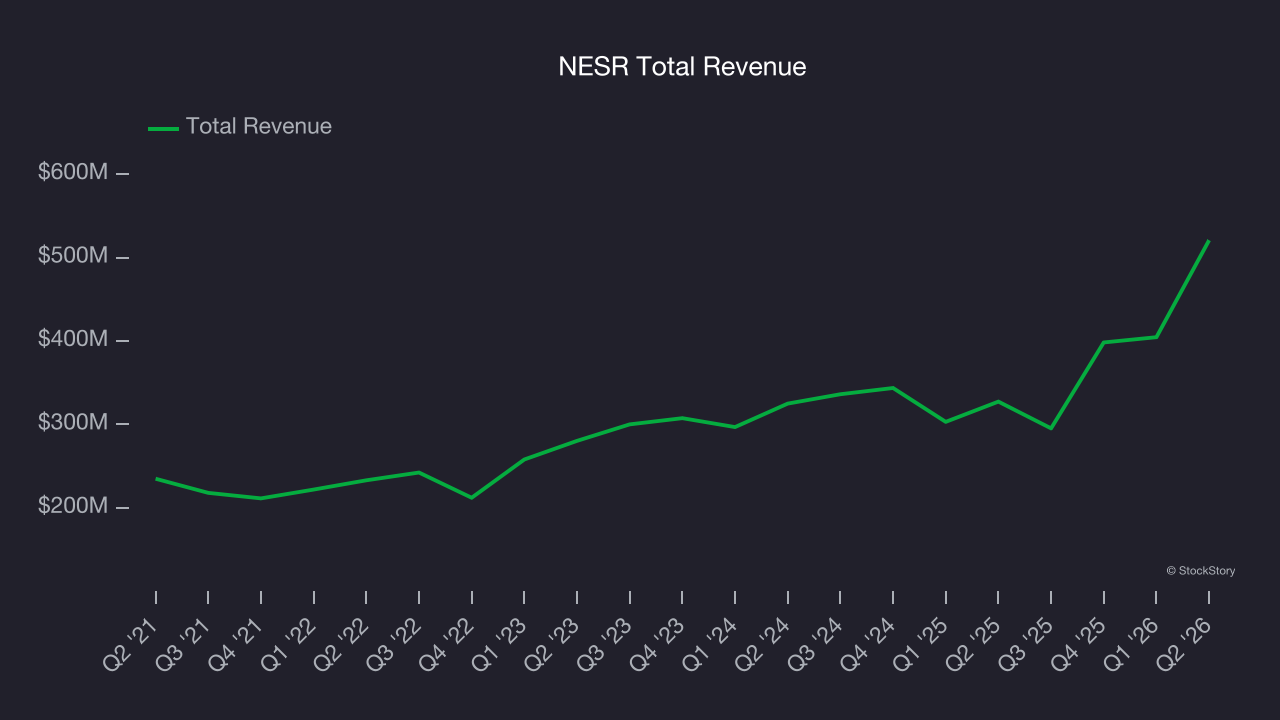
NESR achieved the fastest revenue growth in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 28.3% since reporting. It currently trades at $20.80.
Is now the time to buy NESR? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: ProPetro (NYSE: PUMP)
Operating exclusively in the Permian Basin—one of America's most prolific oil-producing regions—ProPetro (NYSE: PUMP) provides hydraulic fracturing services that pump high-pressure fluid and sand into oil wells to release trapped hydrocarbons.
ProPetro reported revenues of $305.8 million, down 6.2% year on year, falling short of analysts’ expectations by 1.6%. It was a disappointing quarter as it posted a significant miss of analysts’ EBITDA estimates and a significant miss of analysts’ EPS estimates.
As expected, the stock is down 17.9% since the results and currently trades at $8.75.
Read our full analysis of ProPetro’s results here.
Valaris (NYSE: VAL)
Operating the world's largest fleet of offshore drilling rigs across six continents, Valaris (NYSE: VAL) provides offshore drilling rigs and crews to oil and gas companies exploring and producing in deep waters and shallow seas.
Valaris reported revenues of $539.2 million, down 12.4% year on year. This number surpassed analysts’ expectations by 8%. Overall, it was a very strong quarter as it also put up a beat of analysts’ EPS estimates.
The stock is up 10.1% since reporting and currently trades at $84.73.
Read our full, actionable report on Valaris here, it’s free.
Select Water Solutions (NYSE: WTTR)
Managing over 24 billion barrels of produced water annually across major U.S. shale plays, Select Water Solutions (NYSE: WTTR) provides water sourcing, recycling, disposal, and treatment services for oil and gas producers.
Select Water Solutions reported revenues of $395.8 million, up 8.7% year on year. This print topped analysts’ expectations by 5.7%. Overall, it was an incredible quarter as it also logged a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
The stock is up 4.5% since reporting and currently trades at $19.33.
Read our full, actionable report on Select Water Solutions here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 6 Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.