Industrial supplier Fastenal (NASDAQ: FAST) reported Q3 2026 results exceeding the market’s revenue expectations, with sales up 15.5% year on year to $2.46 billion. Its GAAP profit of $0.35 per share was 3.9% above analysts’ consensus estimates.
Is now the time to buy Fastenal? Find out by accessing our full research report, it’s free.
Fastenal (FAST) Q3 2026 Highlights:
- Revenue: $2.46 billion vs analyst estimates of $2.44 billion (15.5% year-on-year growth, 1% beat)
- EPS (GAAP): $0.35 vs analyst estimates of $0.34 (3.9% beat)
- Operating Margin: 21.5%, in line with the same quarter last year
- Free Cash Flow Margin: 14.1%, down from 15.3% in the same quarter last year
- Sales Volumes rose 7.4% year on year (8.7% in the same quarter last year)
- Market Capitalization: $59.02 billion
Company Overview
Founded in 1967, Fastenal (NASDAQ: FAST) provides industrial and construction supplies, including fasteners, tools, safety products, and many other product categories to businesses globally.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Fastenal grew its sales at a solid 9.2% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers, a helpful starting point for our analysis.
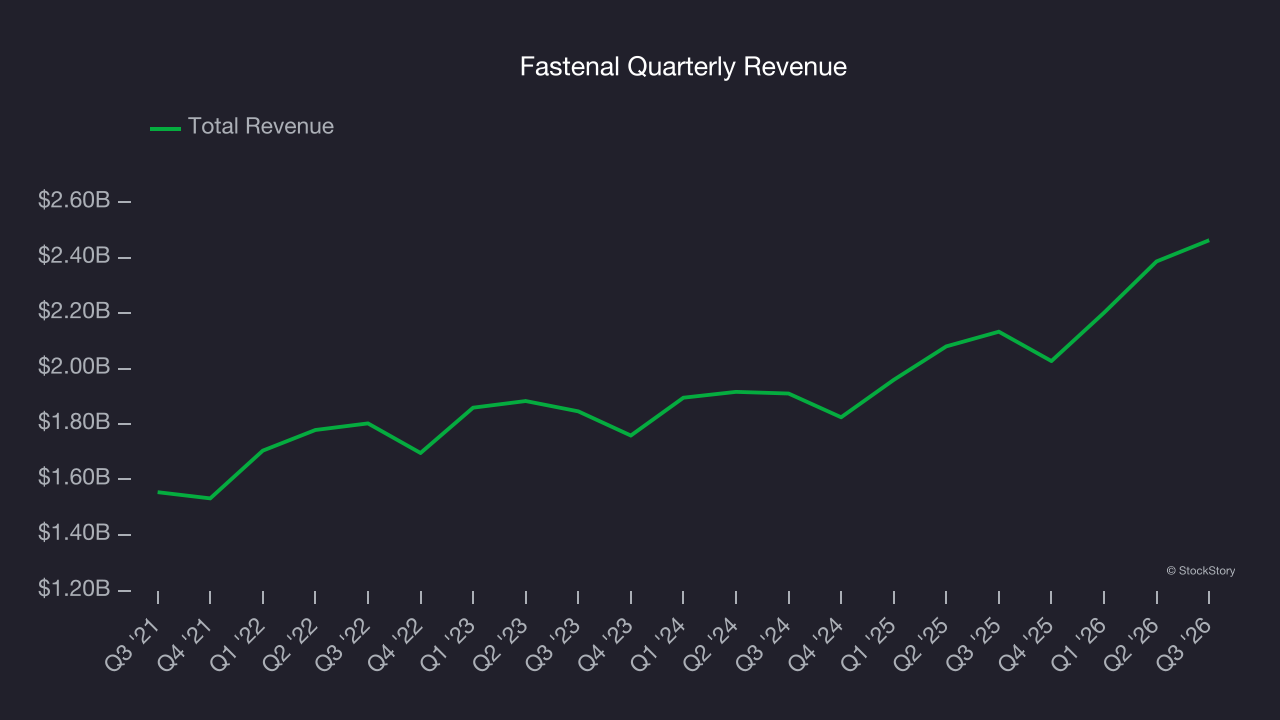
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Fastenal’s annualized revenue growth of 10.2% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 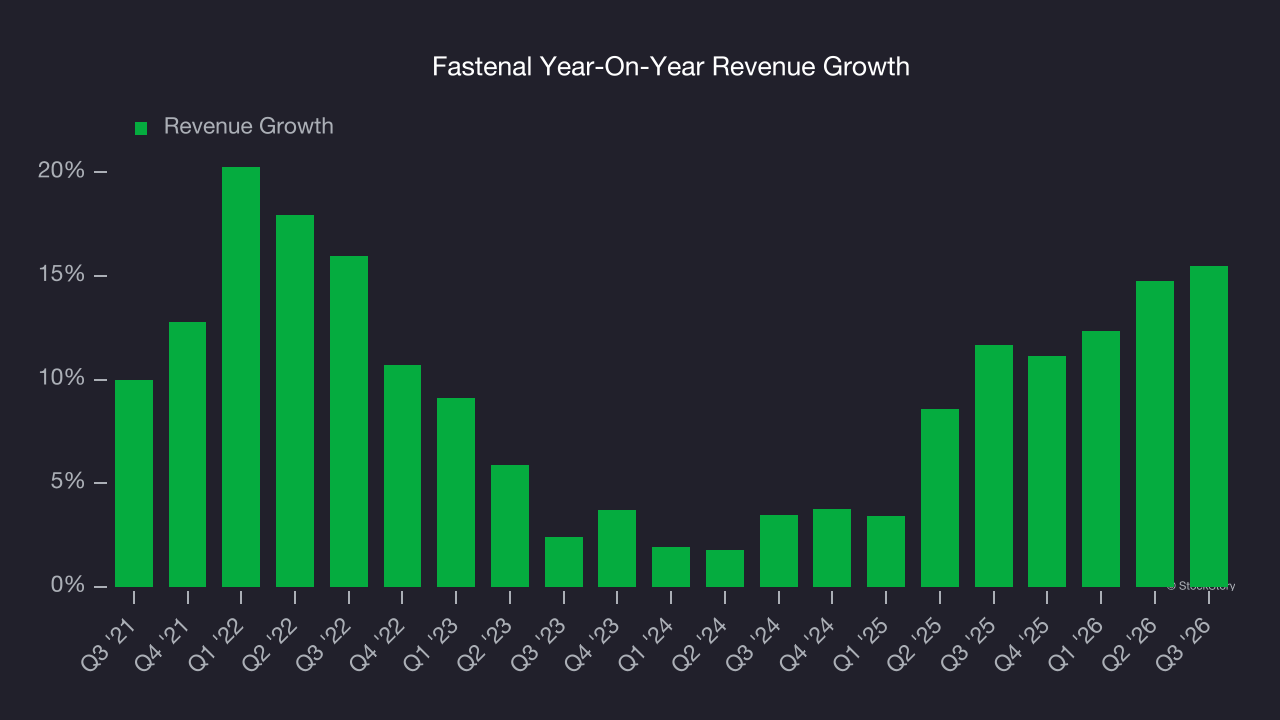
We can dig further into the company’s revenue dynamics by analyzing its number of units sold, which reached 143,878 in the latest quarter. Over the last two years, Fastenal’s units sold averaged 7.6% year-on-year growth. Because this number is lower than its revenue growth, we can see the company benefited from price increases. 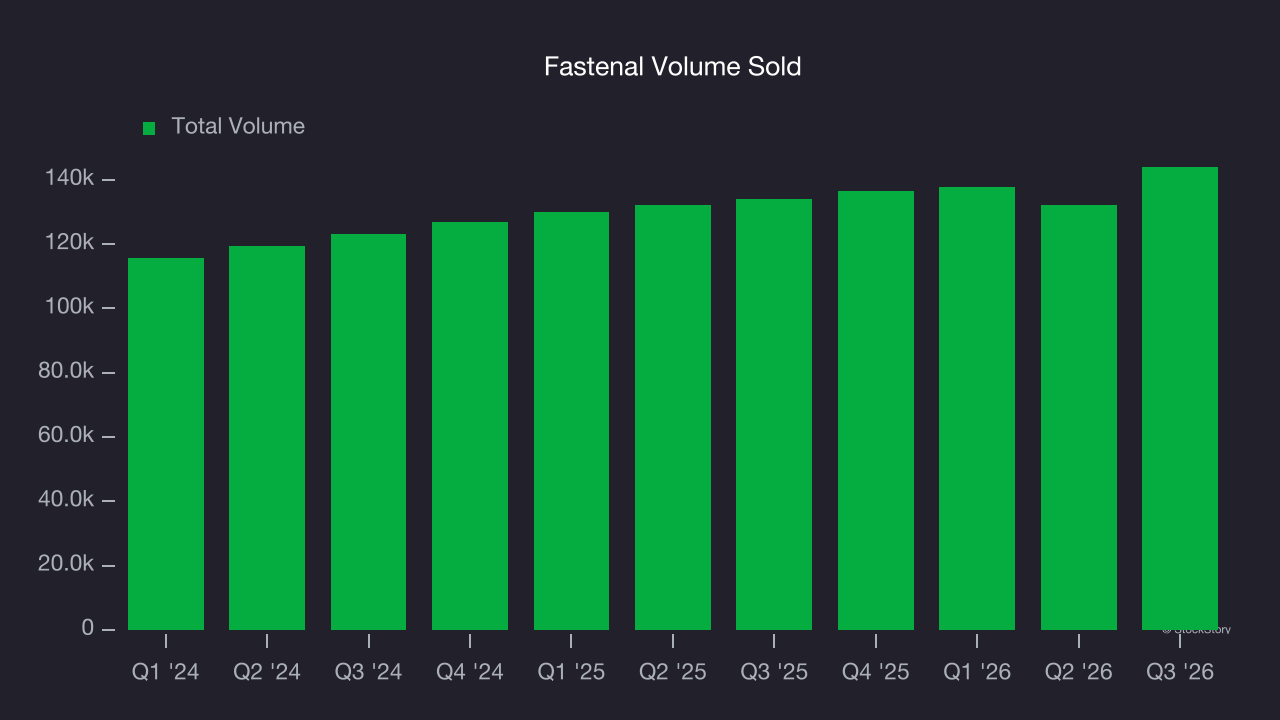
This quarter, Fastenal reported year-on-year revenue growth of 15.5%, and its $2.46 billion of revenue exceeded Wall Street’s estimates by 1%.
Looking ahead, sell-side analysts expect revenue to grow 10.8% over the next 12 months, similar to its two-year rate. This projection is admirable and indicates the market is forecasting success for its products and services.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Fastenal’s operating margin has generally stayed the same over the last 12 months, averaging 20.5% over the last five years. This profitability was elite for an industrials business thanks to its efficient cost structure and economies of scale. This is seen in its fast historical revenue growth and healthy gross margin, which is why we look at all three data points together.
Analyzing the trend in its profitability, Fastenal’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. We like to see margin expansion, but Fastenal’s performance still shows it’s one of the better Maintenance and Repair Distributors companies as most peers saw their margins plummet.
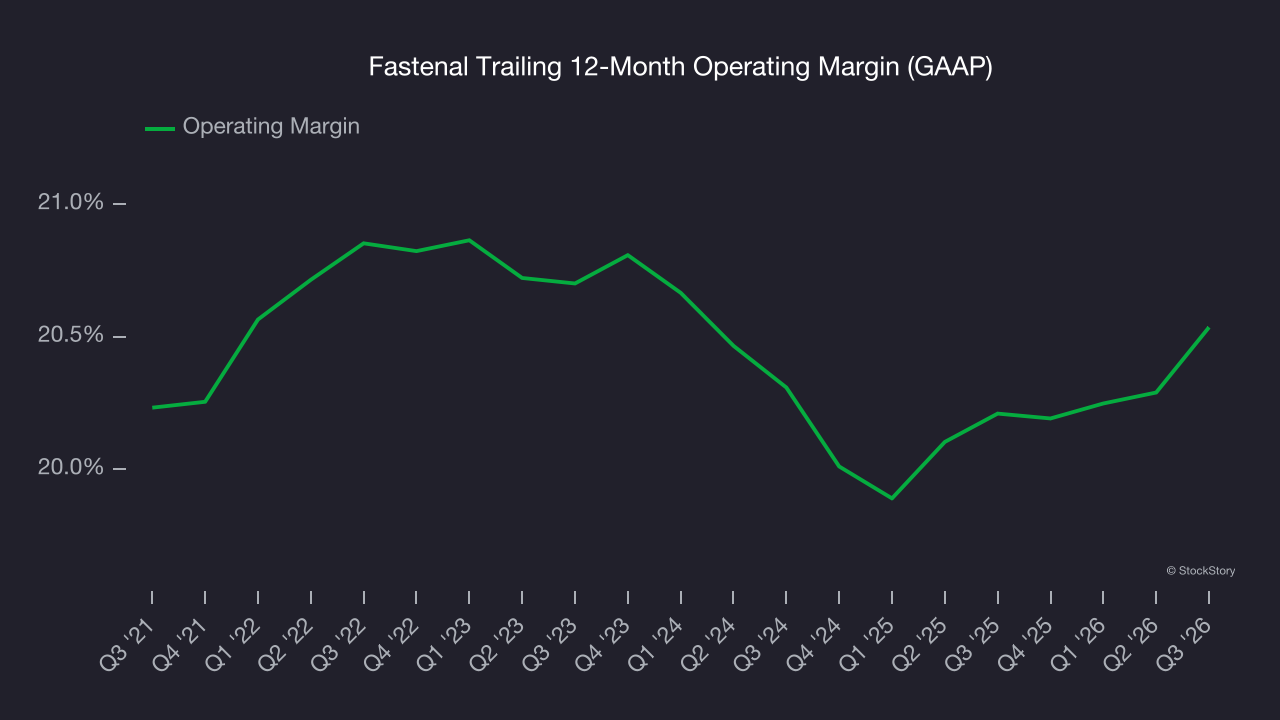
This quarter, Fastenal generated an operating margin profit margin of 21.5%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Fastenal’s decent 9.8% annual EPS growth over the last five years aligns with its revenue performance. This tells us its incremental sales were profitable.
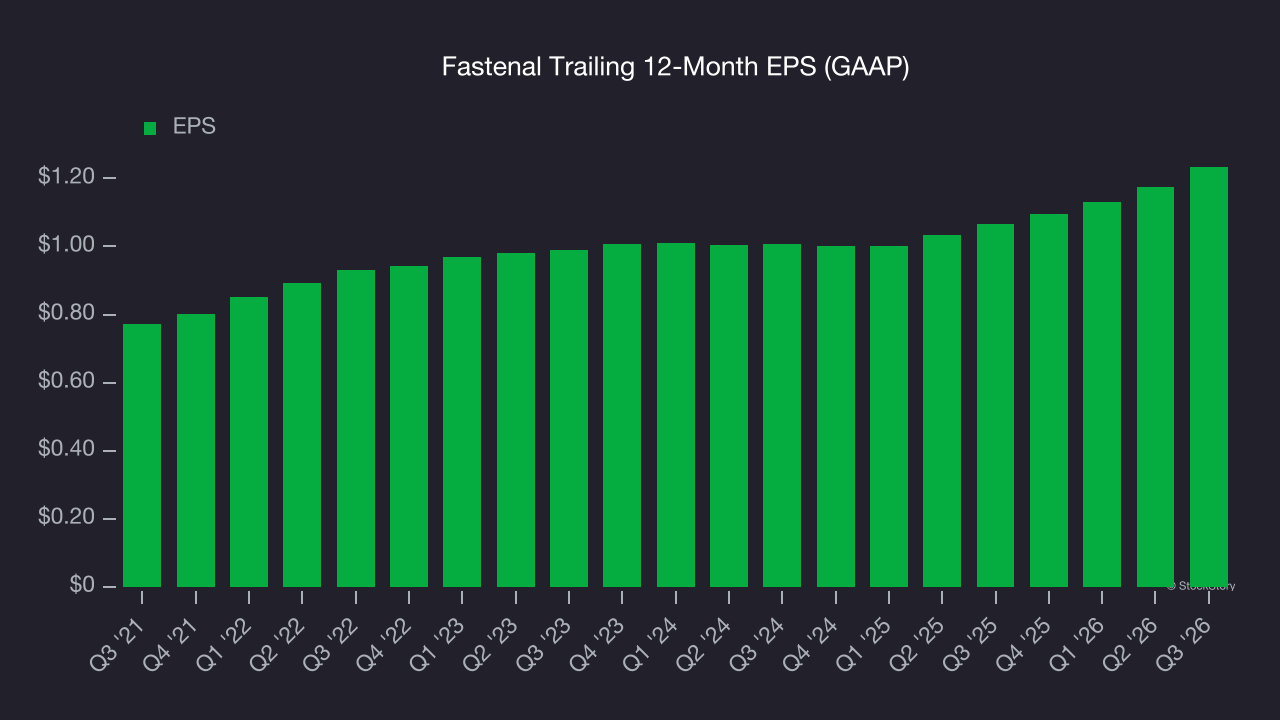
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Fastenal, its two-year annual EPS growth of 10.7% is similar to its five-year trend, implying stable earnings power.
In Q3, Fastenal reported EPS of $0.35, up from $0.29 in the same quarter last year. This print beat analysts’ estimates by 3.9%. Over the next 12 months, Wall Street expects Fastenal’s full-year EPS to grow 10.6% from $1.23 to $1.36.
Key Takeaways from Fastenal’s Q3 Results
It was good to see Fastenal narrowly top analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The market seemed to be hoping for more, and the stock traded down 3.1% to $49.84 immediately after reporting.
Should you buy the stock or not? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).