Recreational vehicle and boat retailer Camping World (NYSE: CWH) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 12.4% year on year to $1.58 billion. Its non-GAAP loss of $0.19 per share was significantly below analysts’ consensus estimates.
For more on Camping World, read our free full research report.
Camping World (CWH) Q3 2026 highlights:
- Revenue $1.58 billion vs S&P analysts’ consensus estimates of $1.65 billion (12.4% year-on-year decline, 4.1% miss)
- Adjusted EPS -$0.19 vs S&P analysts’ consensus estimates of $0.14 (significant miss)
- Adjusted EBITDA $36.01 million vs analysts’ consensus estimates of $66.18 million (2.3% margin, 45.6% miss)
- Operating margin -17.3%, down from 4.4% in the same quarter last year
- Free cash flow margin 8.1%, up from 5.8% in the same quarter last year
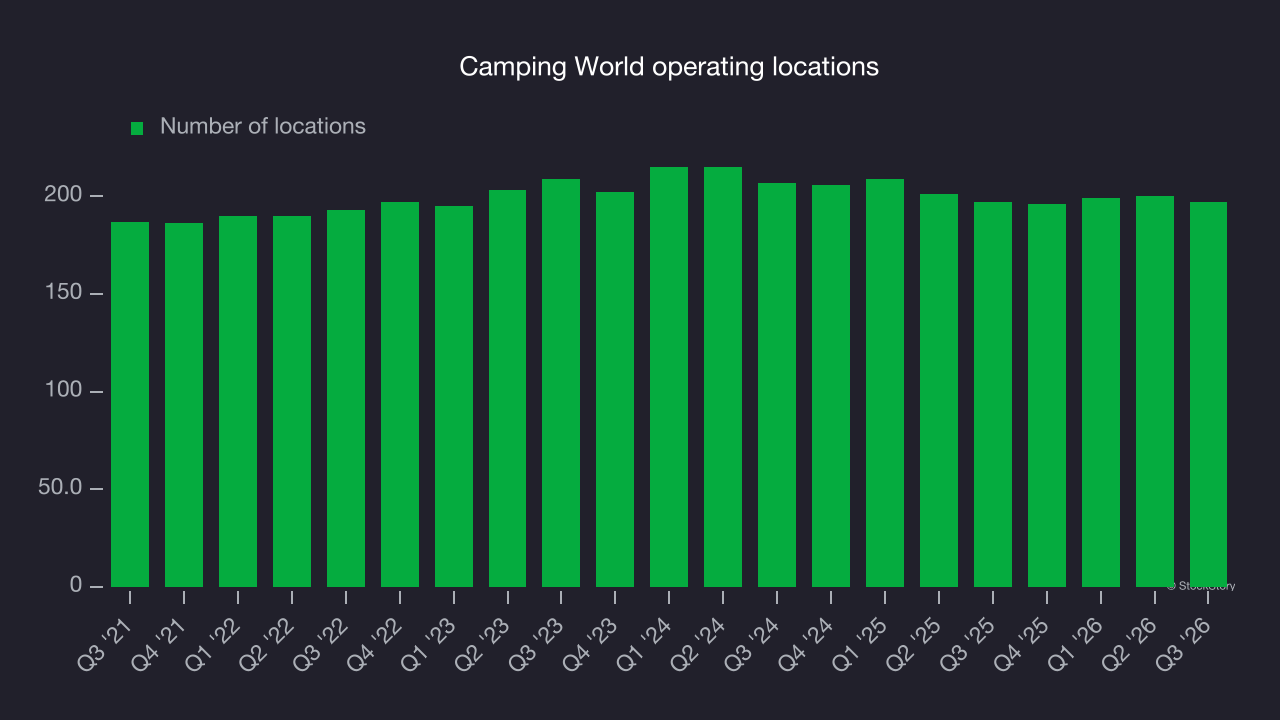
- Locations 197 at quarter end, in line with the same quarter last year
- Same-store sales were flat year on year (5.2% in the same quarter last year)
- Market capitalization $319.1 million
Mr. Wagner continued, “As signals emerged over the summer that new vehicle gross margins across the industry were likely to remain under greater pressure than we had anticipated, we moved swiftly to further optimize our cost structure. We accelerated elements of our previously announced $100 million efficiency program and implemented additional reductions amounting to over $50 million of anticipated incremental annualized savings. We enter the fourth quarter with a cost base that we believe is rebuilt for the current market backdrop and a team focused on the variables we can control.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $6.05 billion in revenue over the past 12 months, Camping World is a mid-sized retailer, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale.
Camping World’s revenue declined by 1.9% per year over the last three years as it closed stores.
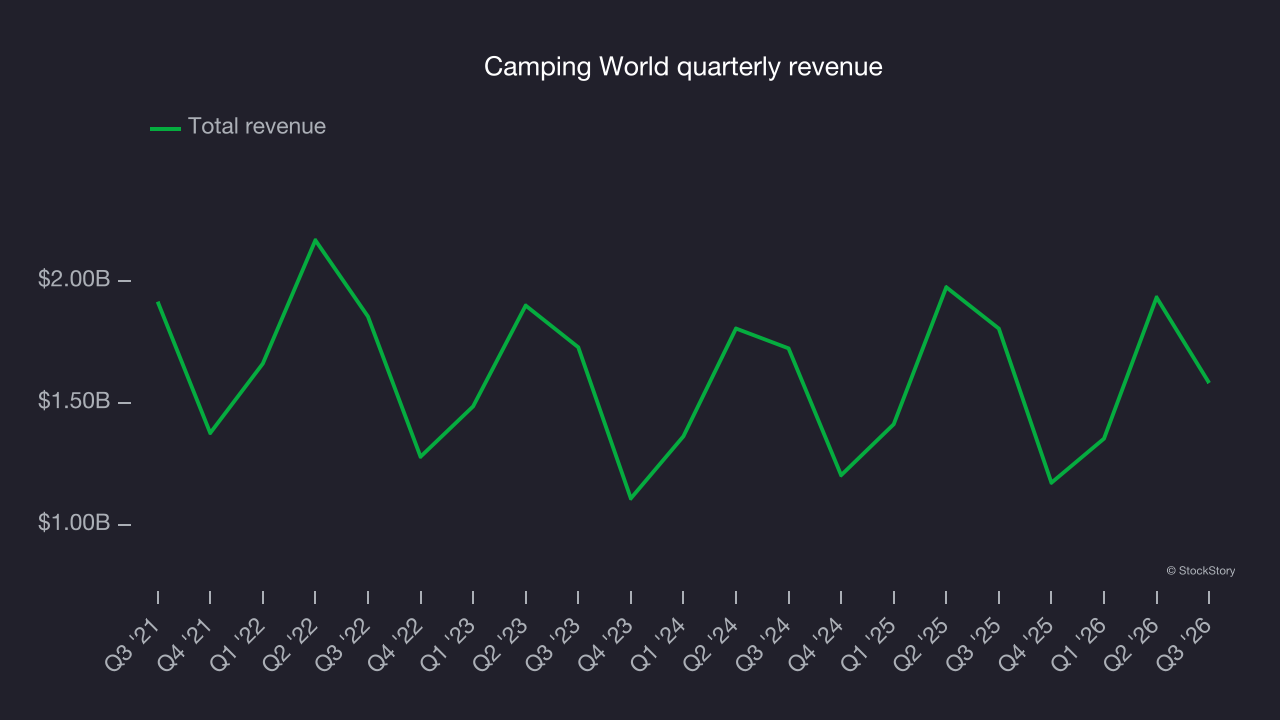
This quarter, Camping World missed Wall Street’s consensus estimates and reported an uninspiring 12.4% year-on-year revenue decline, generating $1.58 billion in revenue.
Looking ahead, sell-side analysts expect revenue to grow 4.4% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is above average for the sector and suggests its newer products will spur better top-line performance.
Store performance
Number of stores
Camping World listed 197 locations in the latest quarter and has generally reduced its store count over the last two years, with annual declines averaging 2.8%.
When a retailer shutters stores, it usually means that brick-and-mortar demand is less than supply, and it is responding by closing underperforming locations to improve profitability.
Same-store sales
A company’s store base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales provide a deeper understanding of this issue because the metric measures organic growth at brick-and-mortar shops open for at least a year.
Camping World’s demand within its existing locations has been relatively stable over the last two years but was below most retailers. On average, the company’s same-store sales have grown by 2% per year. Given its declining store base over the same period, this performance stems from a mixture of higher e-commerce sales and increased foot traffic at existing locations (closing stores can sometimes boost same-store sales).
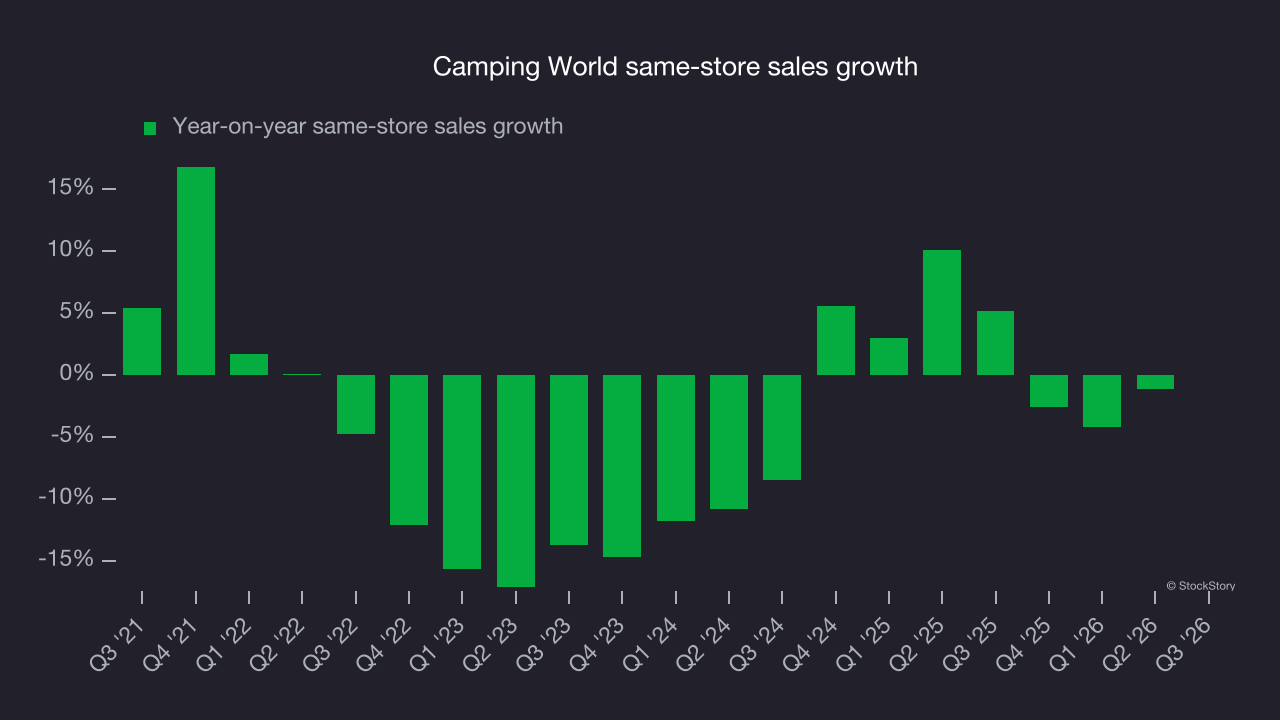
In the latest quarter, Camping World’s same-store sales were flat year over year. This was a meaningful deceleration from its historical levels. The question now is whether Camping World can accelerate growth again.
Key takeaways from Camping World’s Q3 results
Camping World delivered a softer quarter with few positives: revenue missed expectations and EBITDA fell short of Wall Street’s consensus estimates. Shares plunged 11.9% to $4.71 immediately after the results.
Camping World underperformed this quarter, but that alone doesn’t determine whether the stock is worth buying. When making that decision, it’s important to consider its valuation, business quality and latest quarterly results. For more, read our full research report here (it’s free).