Oil and gas producer Vitesse Energy (NYSE: VTS) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 23% year on year to $82.95 million. Its GAAP loss of $0.86 per share was significantly below analysts’ consensus estimates.
For more on Vitesse Energy, read our free full research report.
Vitesse Energy (VTS) Q3 2026 highlights:
- Revenue $82.95 million vs S&P analysts’ consensus estimates of $78.33 million (23% year-on-year growth, 5.9% beat)
- EPS (GAAP) -$0.86 vs analysts’ consensus estimates of $0.01 (significant miss)
- Adjusted EBITDA $39.34 million vs analysts’ consensus estimates of $40.4 million (47.4% margin, 2.6% miss)
- Operating margin 19.7%, up from 0.2% in the same quarter last year
- Free cash flow margin 11.4%, down from 34.7% in the same quarter last year
- Oil production down -14.1% year on year
- Market capitalization $770.5 million
“The third quarter was highlighted by the successful closing of the DJ Basin acquisition, which reinforces our ability to identify and capitalize on attractive investment opportunities,” stated Jamie Benard, Vitesse’s President and Chief Executive Officer. “We expect the transaction to add meaningful cash flow at a valuation accretive to all key metrics while expanding our position in the DJ Basin. This investment, along with anticipated continuation of accelerated drilling and completion activities, reflects Vitesse’s strategy of disciplined capital allocation, strengthening our portfolio, supporting our dividend, and generating sustainable returns for our stockholders.”
Revenue growth
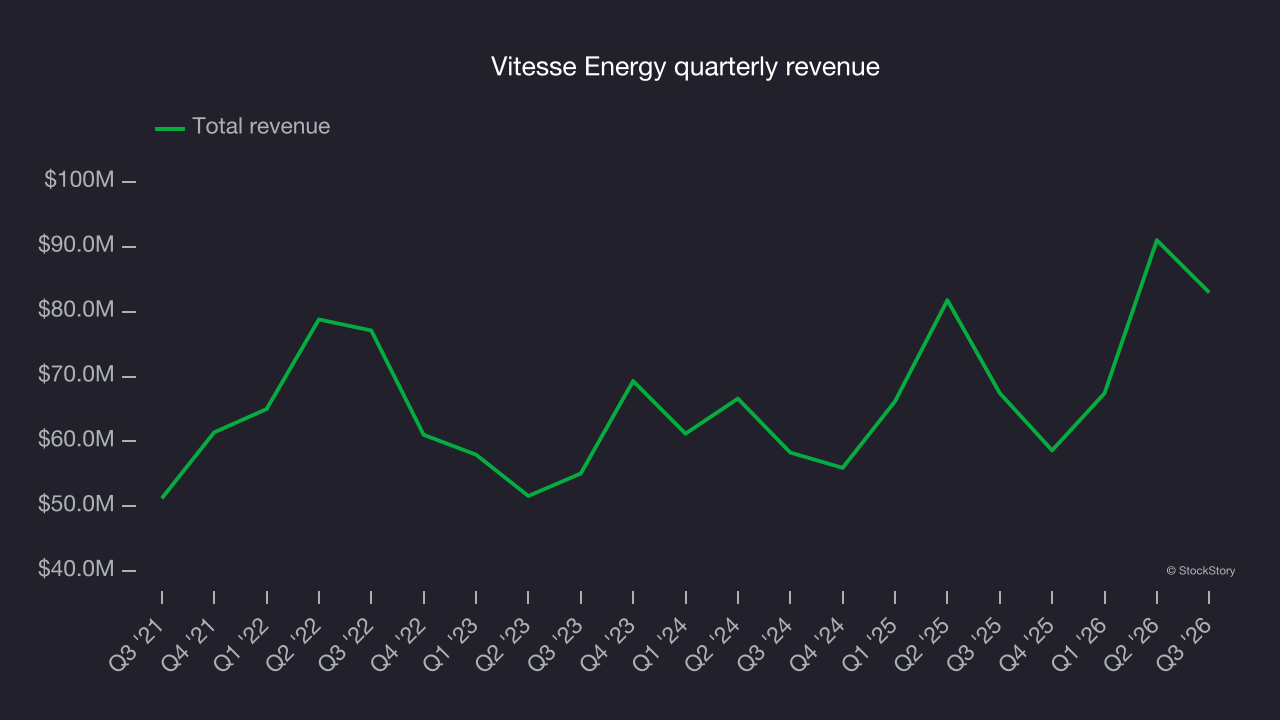
Cyclical industries such as energy can make mediocre companies look strong for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Vitesse Energy’s 13.1% annualized revenue growth over the last five years was solid. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
Revenue provides useful context, but it is heavily influenced by commodity prices and acquisitions. Production volumes, by contrast, reveal whether the underlying asset base is actually growing. Over the last two years, Vitesse Energy’s oil production averaged 10% year-on-year growth while its natural gas production averaged 33.5% year-on-year growth. 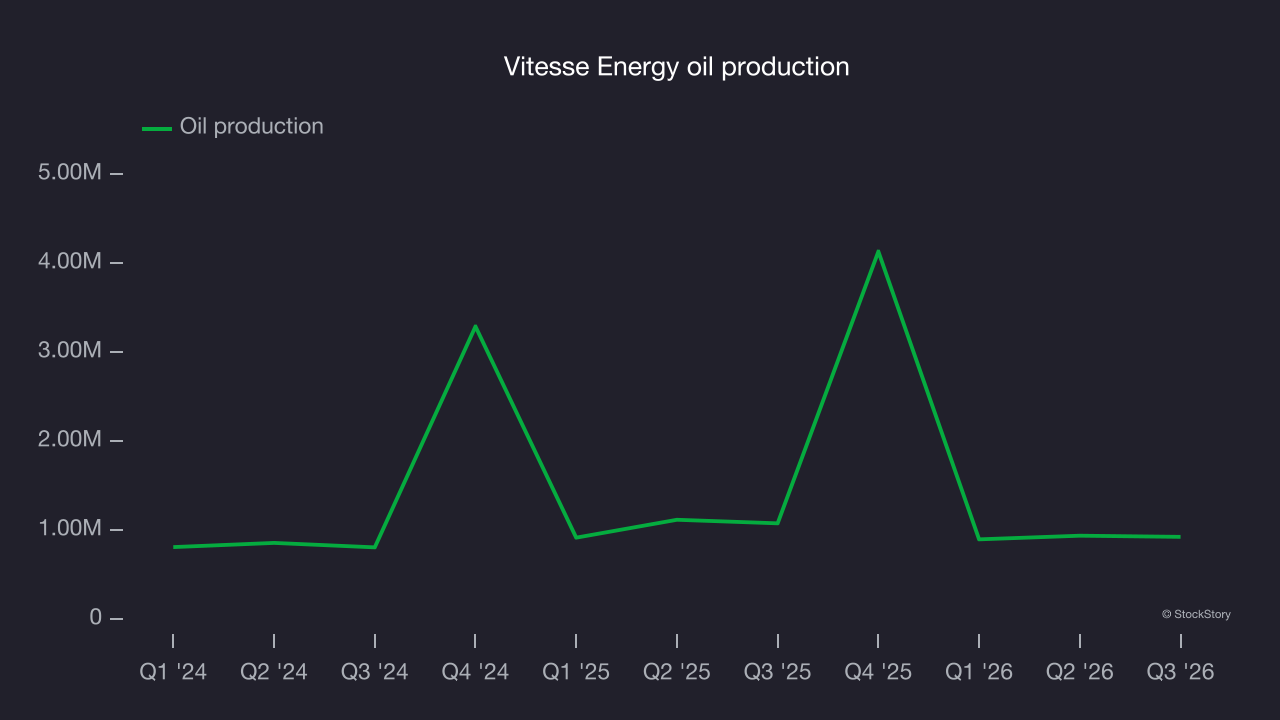
This quarter, Vitesse Energy reported strong year-on-year revenue growth of 23%, and its $82.95 million of revenue topped Wall Street’s consensus estimates by 5.9%. Its oil production fell by 14.1% year on year.
Adjusted EBITDA margin
Adjusted EBITDA margin measures an energy producer’s operating profitability by excluding accounting effects related to depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Vitesse Energy has performed well over the last five years. It demonstrated high profitability for an upstream and integrated energy business, with an average EBITDA margin of 59.4%.
Analyzing the trend in its profitability, Vitesse Energy’s EBITDA margin decreased by 18.2 percentage points over the last year. Even though its historical margin was healthy, shareholders will want to see Vitesse Energy become more profitable in the future.
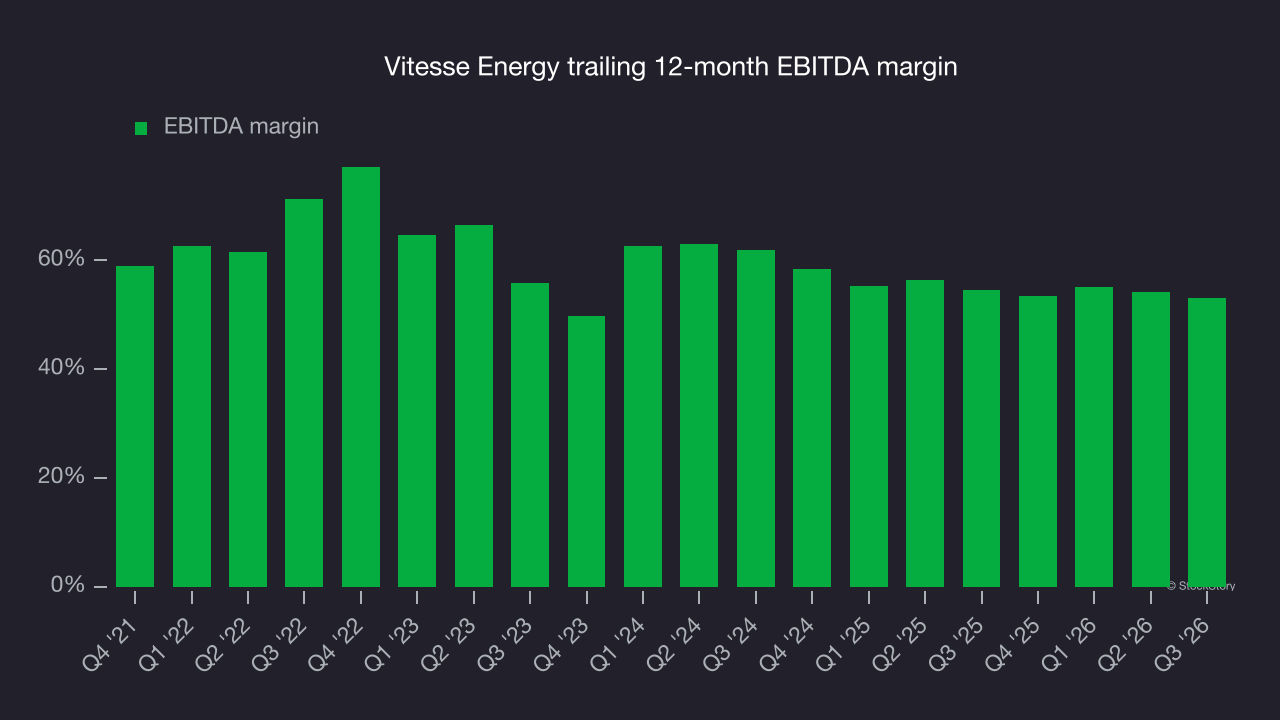
This quarter, Vitesse Energy generated an EBITDA margin of 47.4%, down 3.5 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Vitesse Energy has shown strong cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors and maintain its competitive edge. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 22.3% over the last five years.
While the level of free cash flow margins is important, their consistency matters just as much.
Vitesse Energy’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude price volatility over the past five years was 5 (lower is better), indicating strong insulation from commodity swings. This stability supports capital access in downturns and positions Vitesse Energy to act as a consolidator when weaker peers are forced to retrench.
Why use free cash flow for this stability analysis rather than compare Vitesse Energy’s revenue or EBITDA with WTI crude prices? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
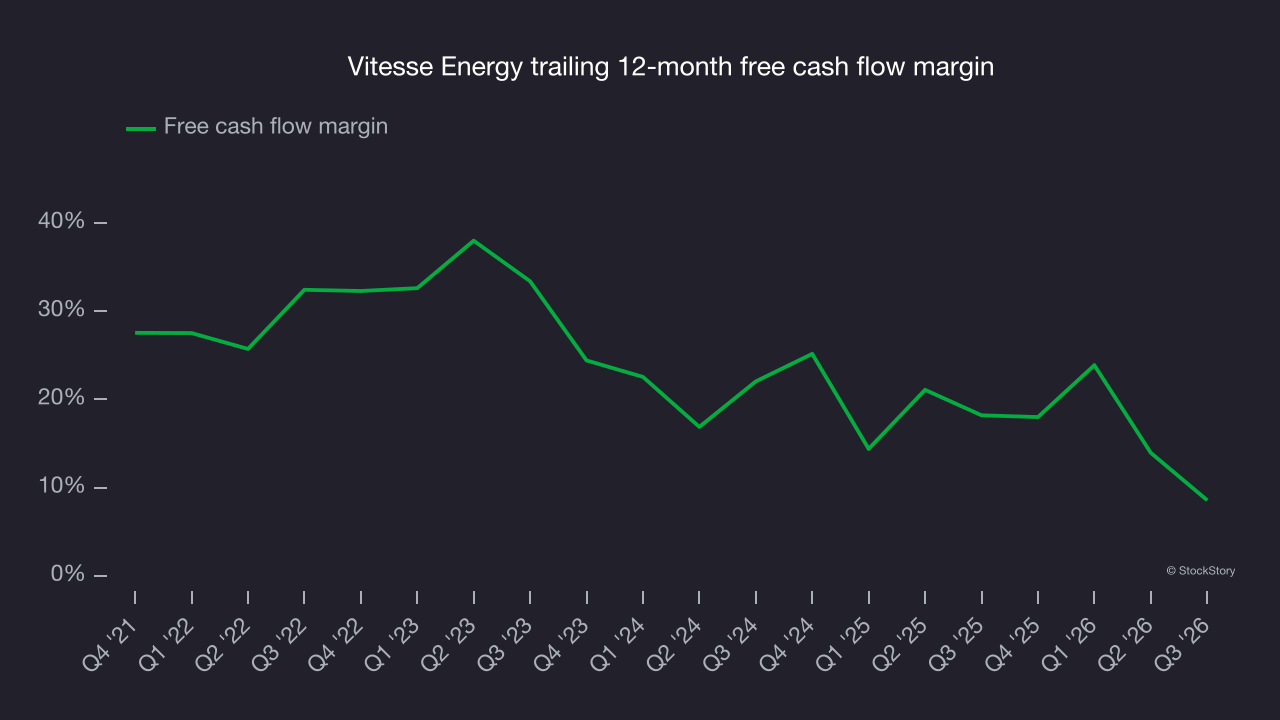
Vitesse Energy’s free cash flow was $9.45 million in Q3, equivalent to an 11.4% margin. The company’s cash profitability declined, with its margin 23.3 percentage points lower than in the same quarter last year, an unfavorable result given its longer-term trend.
Key takeaways from Vitesse Energy’s Q3 results
Vitesse Energy’s revenue came in well ahead of analysts’ consensus estimates, but misses on both EPS and EBITDA left this quarter short of a better overall result. Shares edged higher 1.2% to $17.42 immediately after the release.
When considering an investment in Vitesse Energy, the latest quarter matters, but longer-term business quality and valuation matter more. Read the full research report here for more on those factors (it’s free).