What a time it’s been for Etsy. In the past six months alone, the company’s stock price has increased by a massive 43.5%, reaching $71.72 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Etsy, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Etsy Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on Etsy for now. Here are three reasons why ETSY doesn’t excite us, plus one stock we’d rather own.
1. Declining Active Buyers Reflect Product Weakness
As an online marketplace, Etsy generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Etsy struggled with new customer acquisition over the last two years as its active buyers have declined by 2.1% annually. This performance isn’t ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Etsy wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 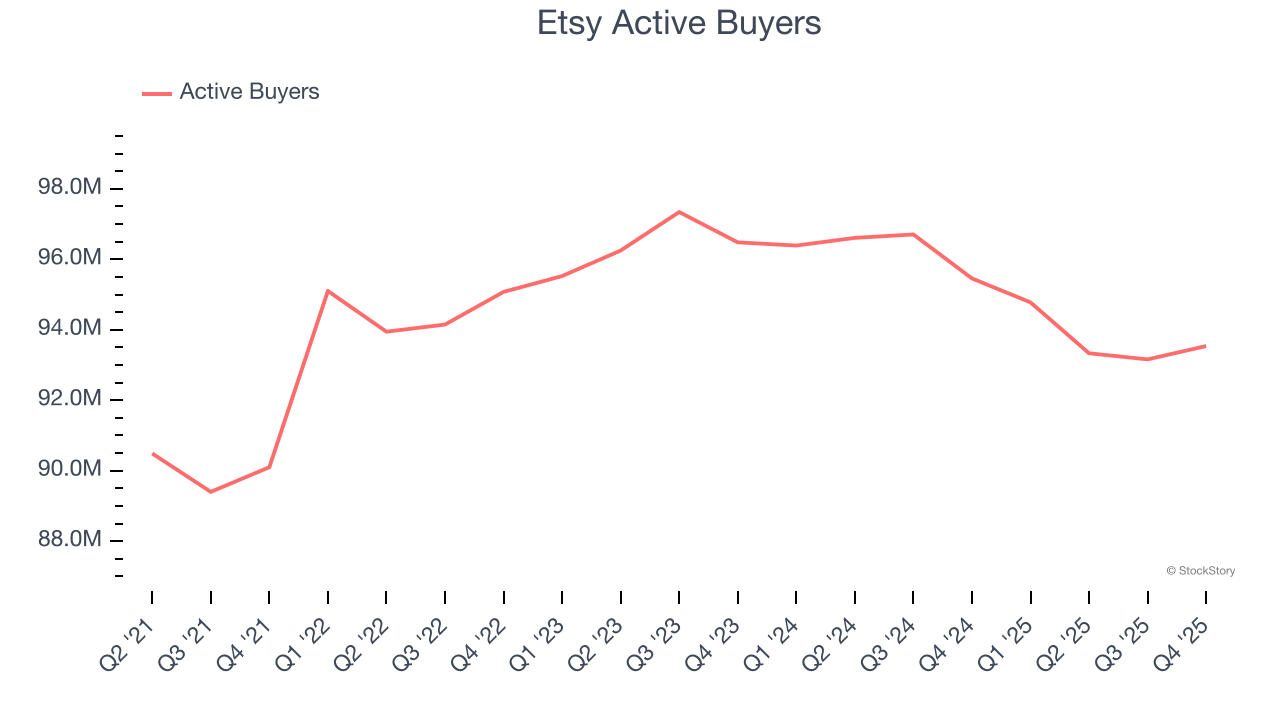
2. Customer Spending Stalls, Engagement Falling?
Average revenue per buyer (ARPB) is a critical metric to track because it measures how much the company earns in transaction fees from each buyer. ARPB also gives us unique insights into a user’s average order size and Etsy’s take rate, or “cut”, on each order.
Etsy’s ARPB has been roughly flat over the last two years. This raises questions about its platform’s health and ability to engage its users. 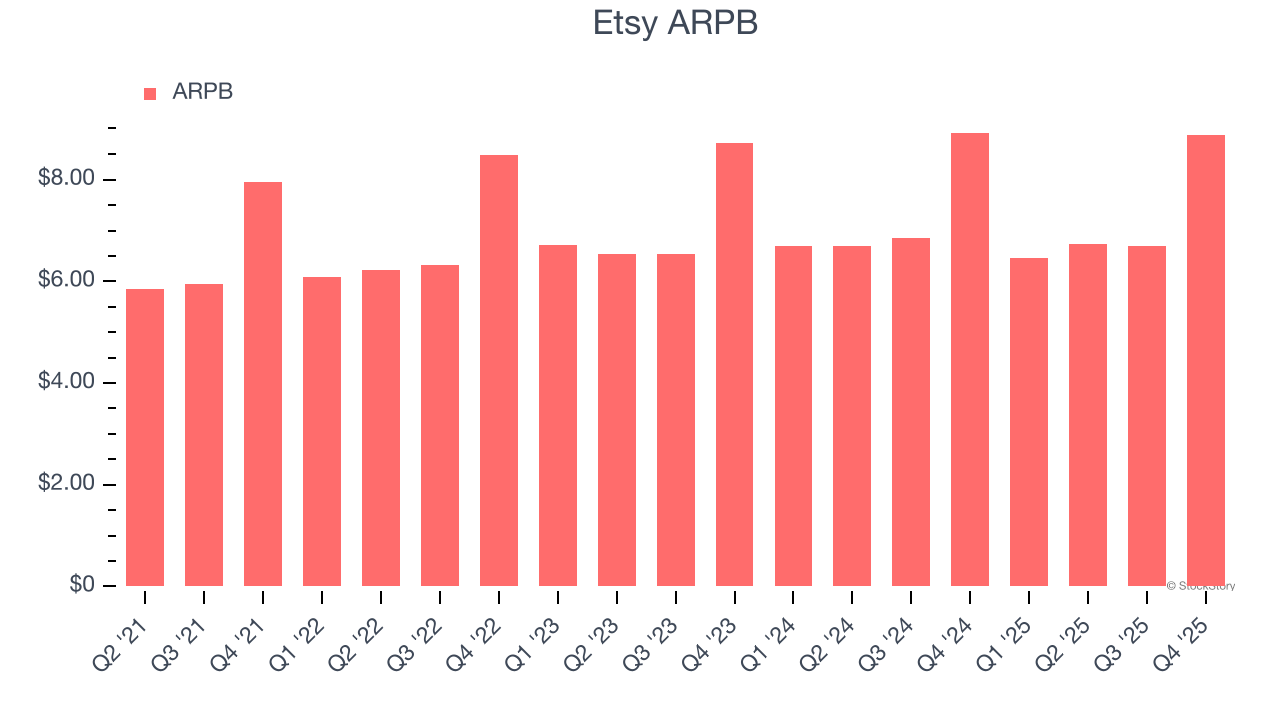
3. EPS Barely Growing
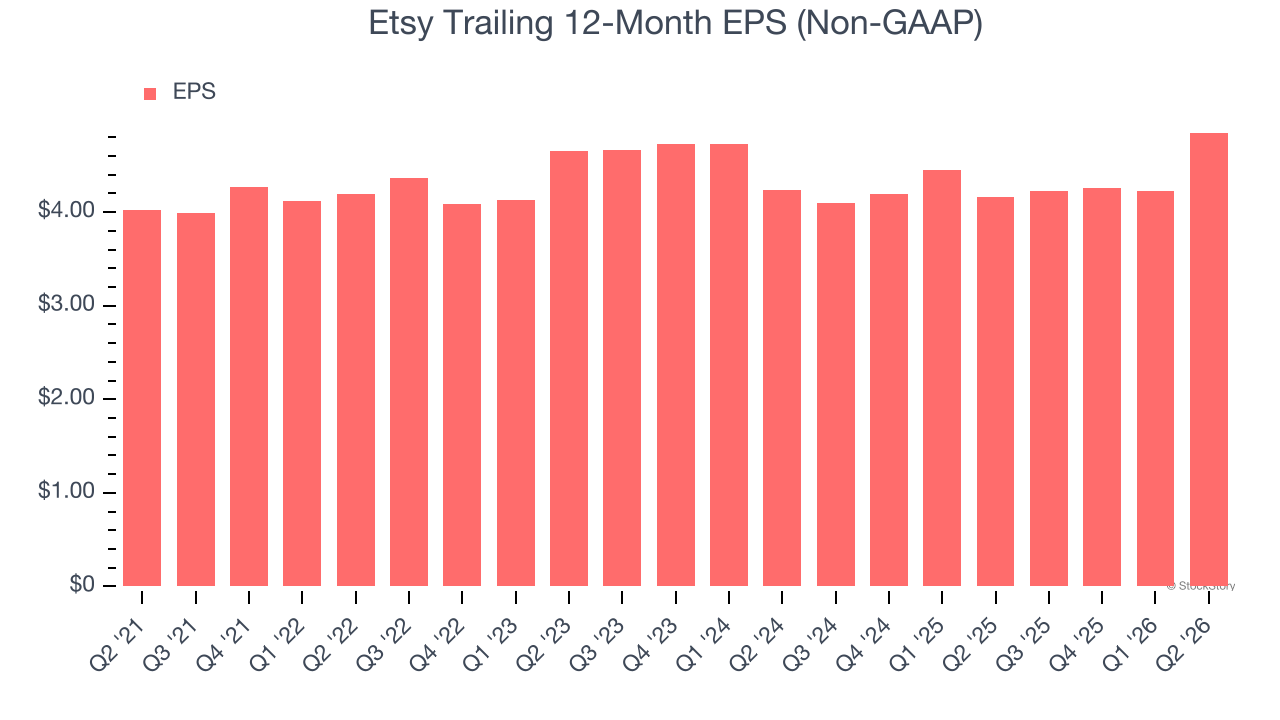
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Etsy’s weak 1.4% annual EPS growth over the last three years aligns with its revenue performance. On the bright side, this tells us its incremental sales were profitable.
Final Judgment
Etsy isn’t a terrible business, but it isn’t one of our picks. Following the recent surge, the stock trades at 11.8× forward EV/EBITDA (or $71.72 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Would Buy Instead of Etsy
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.