Hitting a new 52-week low can be a pivotal moment for any stock. These floors often mark either the beginning of a turnaround story or confirmation that a company faces serious headwinds.
At StockStory, we dig beneath the surface of price movements to uncover whether a company’s fundamentals justify its current valuation or suggest hidden potential. Keeping that in mind, here are three stocks where the skepticism is well-placed and some better opportunities to consider.
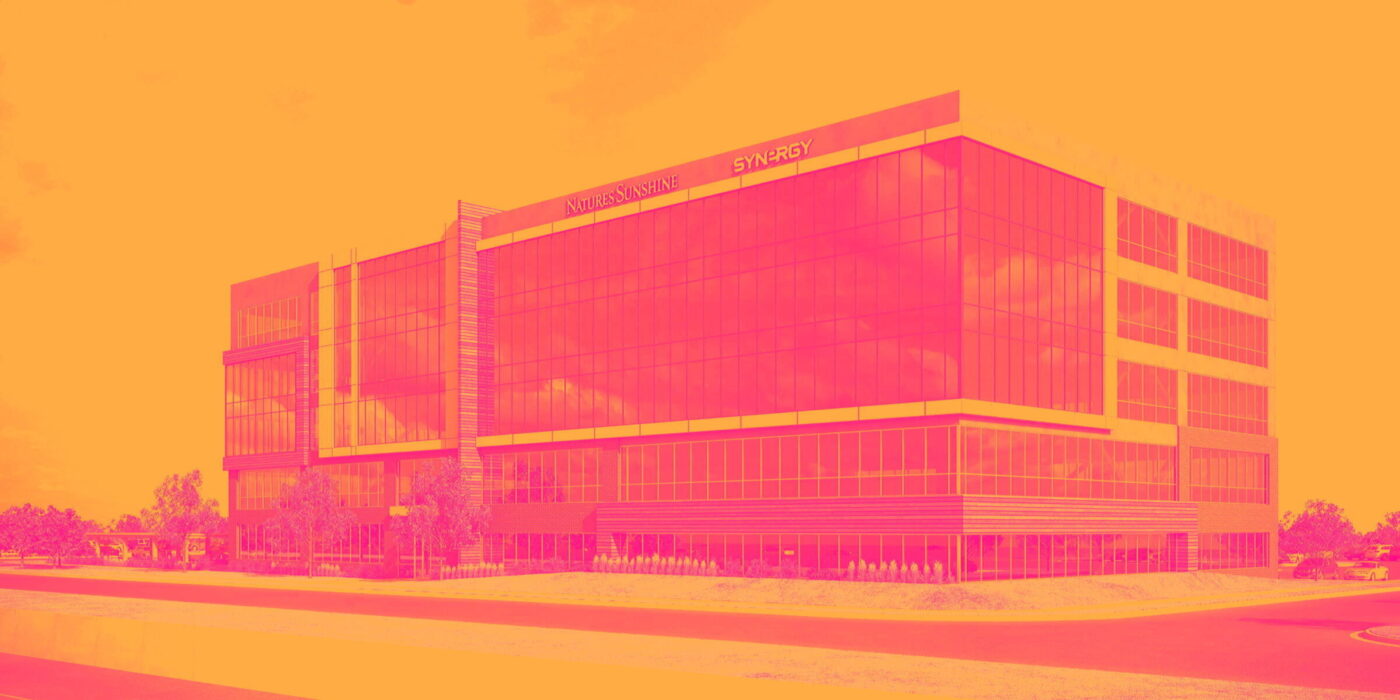
Nature's Sunshine (NATR)
One-Month Return: -3.2%
Started on a kitchen table in Utah, Nature’s Sunshine (NASDAQ: NATR) manufactures and sells nutritional and personal care products.
Why Are We Cautious About NATR?
- Lackluster 4.4% annual revenue growth over the last three years indicates the company is losing ground to competitors
- Subscale operations are evident in its revenue base of $492 million, meaning it has fewer distribution channels than its larger rivals
- Estimated sales growth of 2.8% for the next 12 months implies demand will slow from its three-year trend
At $12.61 per share, Nature's Sunshine trades at 11.8x forward P/E. To fully understand why you should be careful with NATR, check out our full research report (it’s free).
Meritage Homes (MTH)
One-Month Return: -7.2%
Originally founded in 1985 in Arizona as Monterey Homes, Meritage Homes (NYSE: MTH) is a homebuilder specializing in designing and constructing energy-efficient and single-family homes in the US.
Why Should You Sell MTH?
- Demand cratered as it couldn’t win new orders over the past two years, leading to an average 27.6% decline in its backlog
- Earnings per share have dipped by 7.7% annually over the past five years, which is concerning because stock prices follow EPS over the long term
- Diminishing returns on capital suggest its earlier profit pools are drying up
Meritage Homes is trading at $59.73 per share, or 11.7x forward P/E. Dive into our free research report to see why there are better opportunities than MTH.
Ellington Financial (EFC)
One-Month Return: -7.1%
Operating under the guidance of Ellington Management Group, a respected name in structured credit markets, Ellington Financial (NYSE: EFC) acquires and manages a diverse portfolio of mortgage-related, consumer-related, and other financial assets to generate returns for investors.
Why Do We Avoid EFC?
- Annual earnings per share growth of 4.6% underperformed its revenue over the last five years, showing its incremental sales were less profitable
- Tangible book value per share tumbled by 5.9% annually over the last five years, showing banking sector trends are working against it during this cycle
- Below-average return on equity indicates management struggled to find compelling investment opportunities
Ellington Financial’s stock price of $11.71 implies a valuation ratio of 0.9x forward P/B. Check out our free in-depth research report to learn more about why EFC doesn’t pass our bar.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.