
Online education Stride (NYSE: LRN) reported calendar Q3 2026 (fiscal Q1 2027) results exceeding the market’s revenue expectations, with sales up 3% year on year to $639.4 million. The company expects next quarter’s revenue to be around $635 million, close to analysts’ estimates. Its non-GAAP profit of $1.37 per share was 5.9% above analysts’ consensus estimates.
Is now the time to buy Stride? Find out by accessing our full research report, it’s free.
Stride (LRN) Q3 CY2026 Highlights:
- Revenue: $639.4 million vs analyst estimates of $615.7 million (3% year-on-year growth, 3.8% beat)
- Adjusted EPS: $1.37 vs analyst estimates of $1.29 (5.9% beat)
- Adjusted EBITDA: $111.8 million vs analyst estimates of $107.4 million (17.5% margin, 4.1% beat)
- Revenue Guidance for the full year is $2.57 billion at the midpoint, roughly in line with what analysts were expecting
- Operating Margin: 13.2%, up from 11.1% in the same quarter last year
- Market Capitalization: $3.33 billion
Company Overview
Formerly known as K12, Stride (NYSE: LRN) is an education technology company providing education solutions through digital platforms.
Revenue Growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years.
With $2.54 billion in revenue over the past 12 months, Stride is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale. On the bright side, it can still flex high growth rates because it’s working from a smaller revenue base.
As you can see below, Stride’s 10.1% annualized revenue growth over the last five years was impressive. This is a great starting point for our analysis because it shows Stride’s demand was higher than many business services companies.
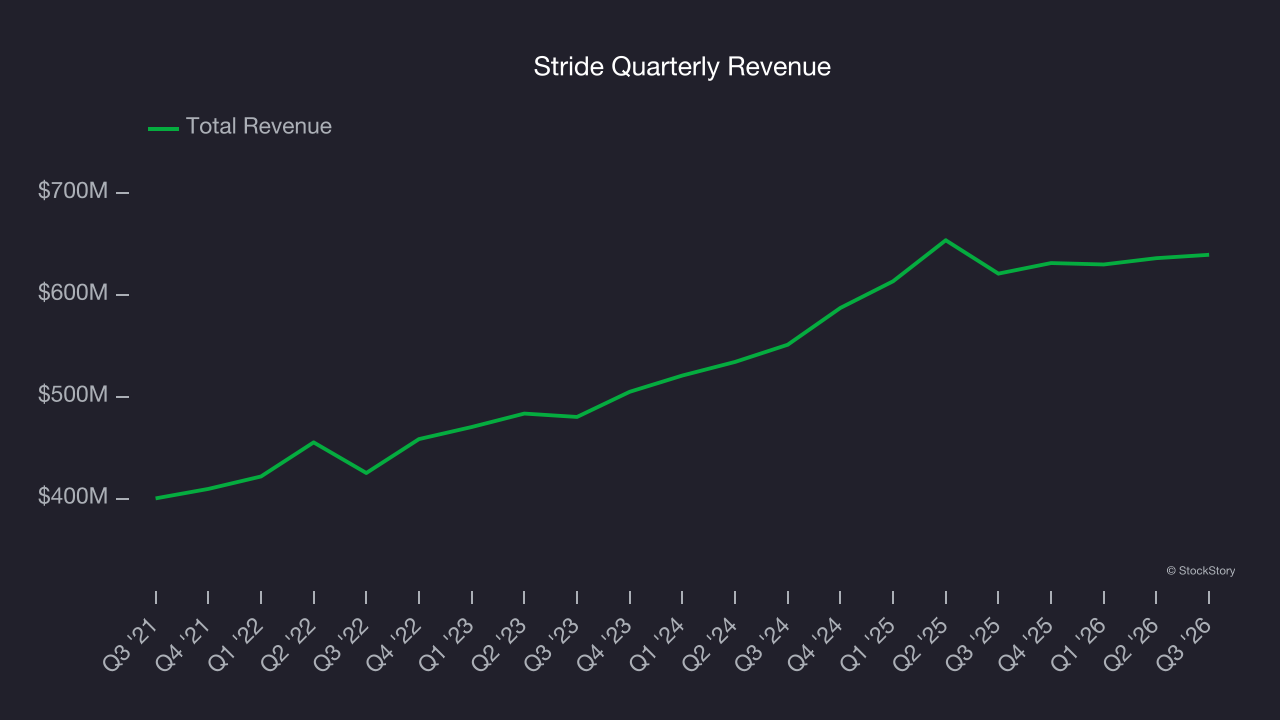
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Stride’s annualized revenue growth of 9.6% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 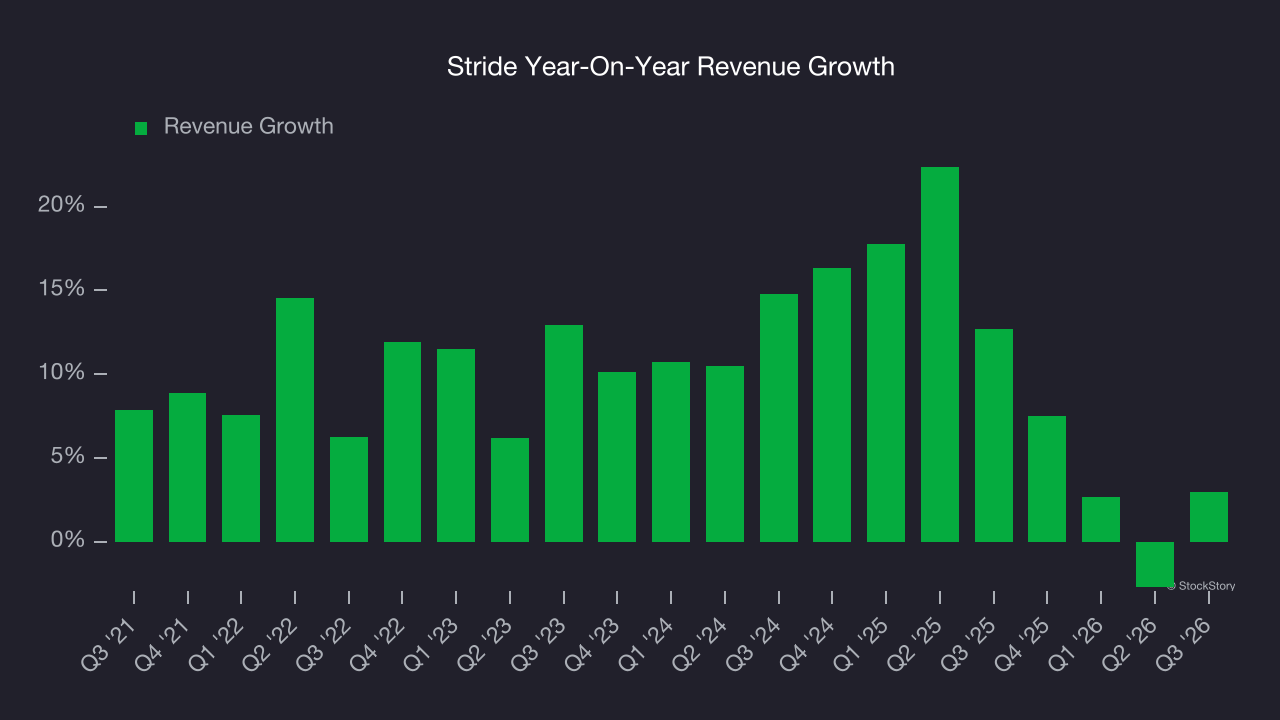
This quarter, Stride reported modest year-on-year revenue growth of 3% but beat Wall Street’s estimates by 3.8%. Company management is currently guiding for flat sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. At least the company is tracking well in other measures of financial health.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Adjusted Operating Margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
Stride has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, boasting an average adjusted operating margin of 16%.
Looking at the trend in its profitability, Stride’s adjusted operating margin rose by 9.9 percentage points over the last five years, as its sales growth gave it immense operating leverage.
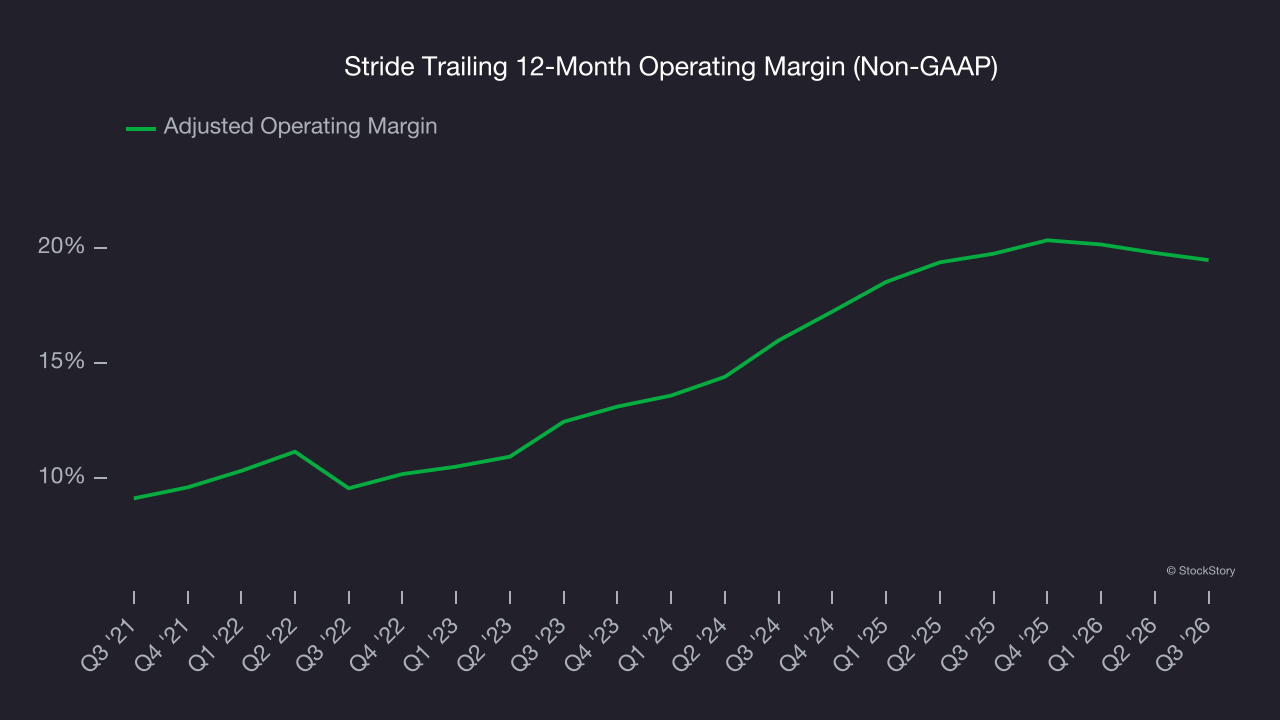
In Q3, Stride generated an adjusted operating margin profit margin of 12%, down 1 percentage points year on year. This reduction is quite minuscule and indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Stride’s EPS grew at 45.5% compounded annual growth rate over the last five years, higher than its 10.1% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
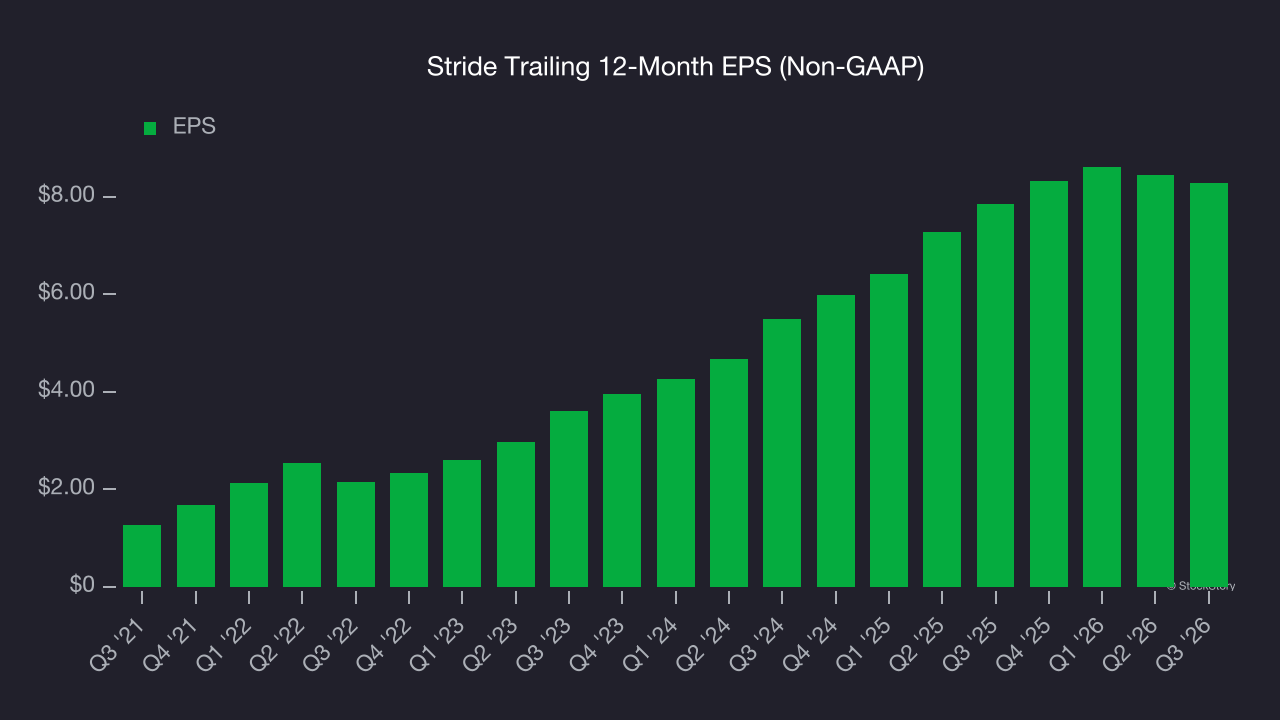
We can take a deeper look into Stride’s earnings to better understand the drivers of its performance. As we mentioned earlier, Stride’s adjusted operating margin declined this quarter but expanded by 9.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Stride, its two-year annual EPS growth of 22.8% was lower than its five-year trend. We still think its growth was good and hope it can accelerate in the future.
In Q3, Stride reported adjusted EPS of $1.37, down from $1.52 in the same quarter last year. Despite falling year on year, this print beat analysts’ estimates by 5.9%. Over the next 12 months, Wall Street expects Stride’s full-year EPS to grow 5.8% from $8.29 to $8.77.
Key Takeaways from Stride’s Q3 Results
We enjoyed seeing Stride beat analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. On the other hand, its revenue guidance for next quarter was in line. Overall, this print had some key positives. The market seemed to be hoping for more, and the stock traded down 2.3% to $77.19 immediately following the results.
So do we think Stride is an attractive buy at the current price? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).