
Infrastructure and agriculture equipment manufacturer Valmont Industries (NYSE: VMI) missed Wall Street’s revenue expectations in Q3 2026, but sales rose 5.5% year on year to $1.10 billion. On the other hand, the company’s outlook for the full year was close to analysts’ estimates with revenue guided to $4.38 billion at the midpoint. Its non-GAAP profit of $6.24 per share was 9% above analysts’ consensus estimates.
Is now the time to buy Valmont? Find out by accessing our full research report, it’s free.
Valmont (VMI) Q3 2026 Highlights:
- Revenue: $1.10 billion vs analyst estimates of $1.12 billion (5.5% year-on-year growth, 1.3% miss)
- Adjusted EPS: $6.24 vs analyst estimates of $5.73 (9% beat)
- Adjusted EBITDA: $753 million vs analyst estimates of $185.5 million (68.2% margin, significant beat)
- The company reconfirmed its revenue guidance for the full year of $4.38 billion at the midpoint
- Adjusted EPS guidance for the full year is $23.25 at the midpoint, beating analyst estimates by 1.4%
- Operating Margin: 15.7%, up from 13.5% in the same quarter last year
- Free Cash Flow Margin: 5%, down from 6.7% in the same quarter last year
- Backlog: $2.01 billion at quarter end, up 16.1% year on year
- Market Capitalization: $8.73 billion
“Given our results, we are raising our adjusted earnings per share guidance range. As we finish 2026 and prepare for 2027, we are focused on turning our capacity investments into higher throughput and improved productivity across the Infrastructure segment. At the same time, we are taking pricing actions and applying contractual pass-throughs to recover higher steel and zinc costs. The pace of margin expansion depends in part on how quickly input costs stabilize. Strong customer demand in Utility and Coatings, together with our investments and operating improvements across Infrastructure and Agriculture support our confidence in the objectives presented at our 2026 Investor Day.”
Company Overview
Credited with an invention in the 1950s that improved crop yields, Valmont (NYSE: VMI) provides engineered products and infrastructure services for the agricultural industry.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Valmont’s 5.2% annualized revenue growth over the last five years was tepid. This wasn’t a great result compared to the rest of the industrials sector, but there are still things to like about Valmont.
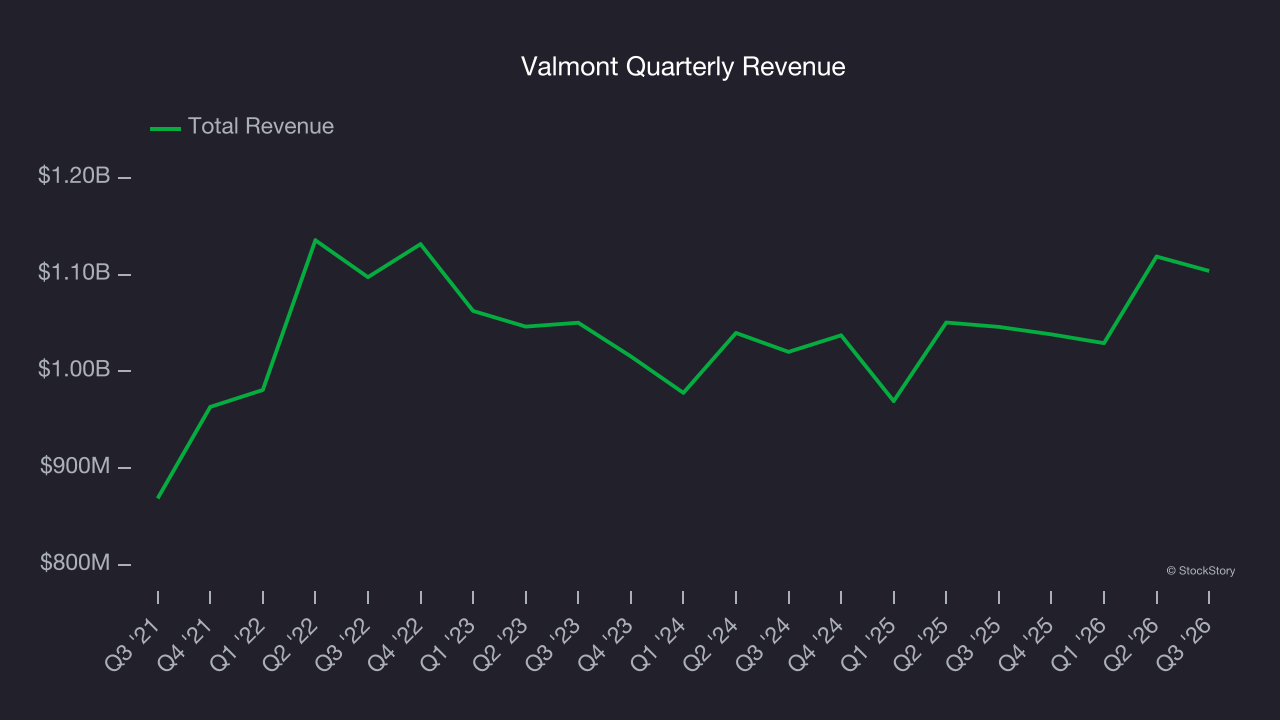
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Valmont’s recent performance shows its demand has slowed as its annualized revenue growth of 2.9% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 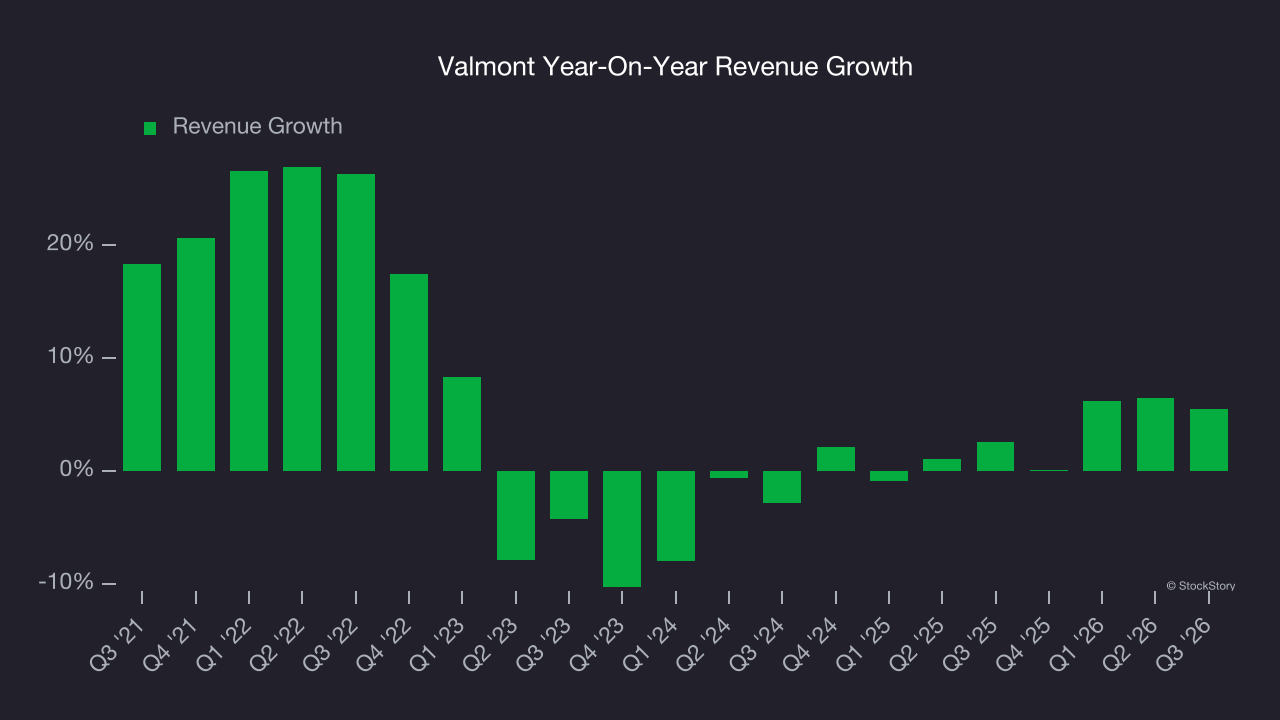
This quarter, Valmont’s revenue grew by 5.5% year on year to $1.10 billion, missing Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 7.7% over the next 12 months, an improvement versus the last two years. This projection is above average for the sector and suggests its newer products and services will spur better top-line performance.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Operating Margin
Valmont has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 10.6%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes huge shifts to move meaningfully. Companies have more control over their operating margins, and it’s a show of well-managed operations if they’re high when gross margins are low.
Looking at the trend in its profitability, Valmont’s operating margin rose by 5.3 percentage points over the last five years, as its sales growth gave it operating leverage.
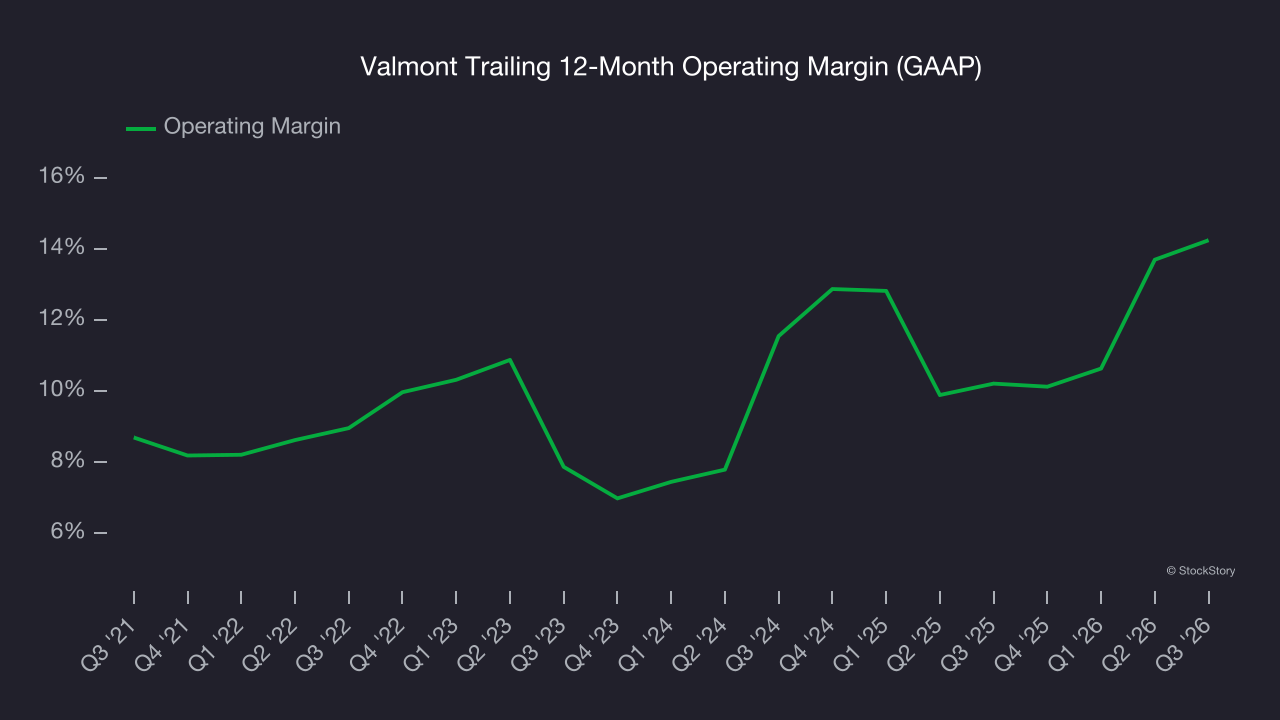
This quarter, Valmont generated an operating margin profit margin of 15.7%, up 2.1 percentage points year on year. The increase was encouraging, and because its operating margin rose more than its gross margin, we can infer it was more efficient with expenses such as marketing, R&D, and administrative overhead.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Valmont’s EPS grew at 17% compounded annual growth rate over the last five years, higher than its 5.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
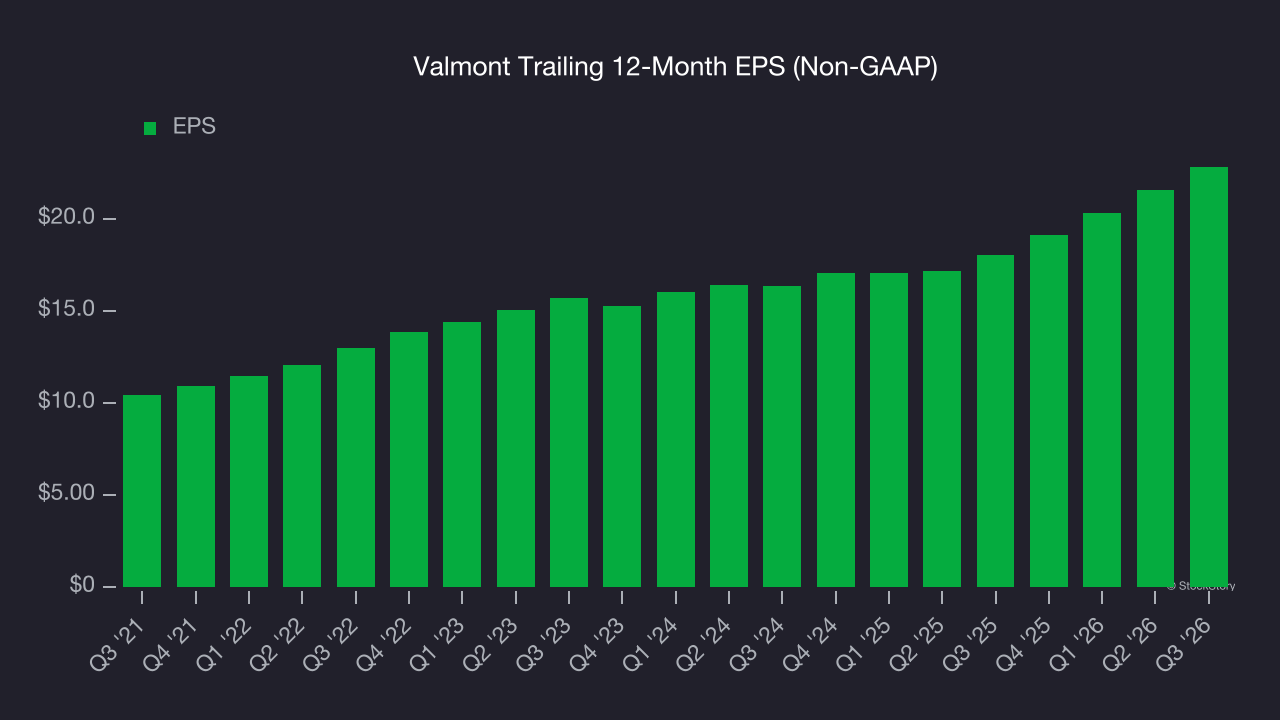
Diving into Valmont’s quality of earnings can give us a better understanding of its performance. As we mentioned earlier, Valmont’s operating margin expanded by 5.3 percentage points over the last five years. On top of that, its share count shrank by 10%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 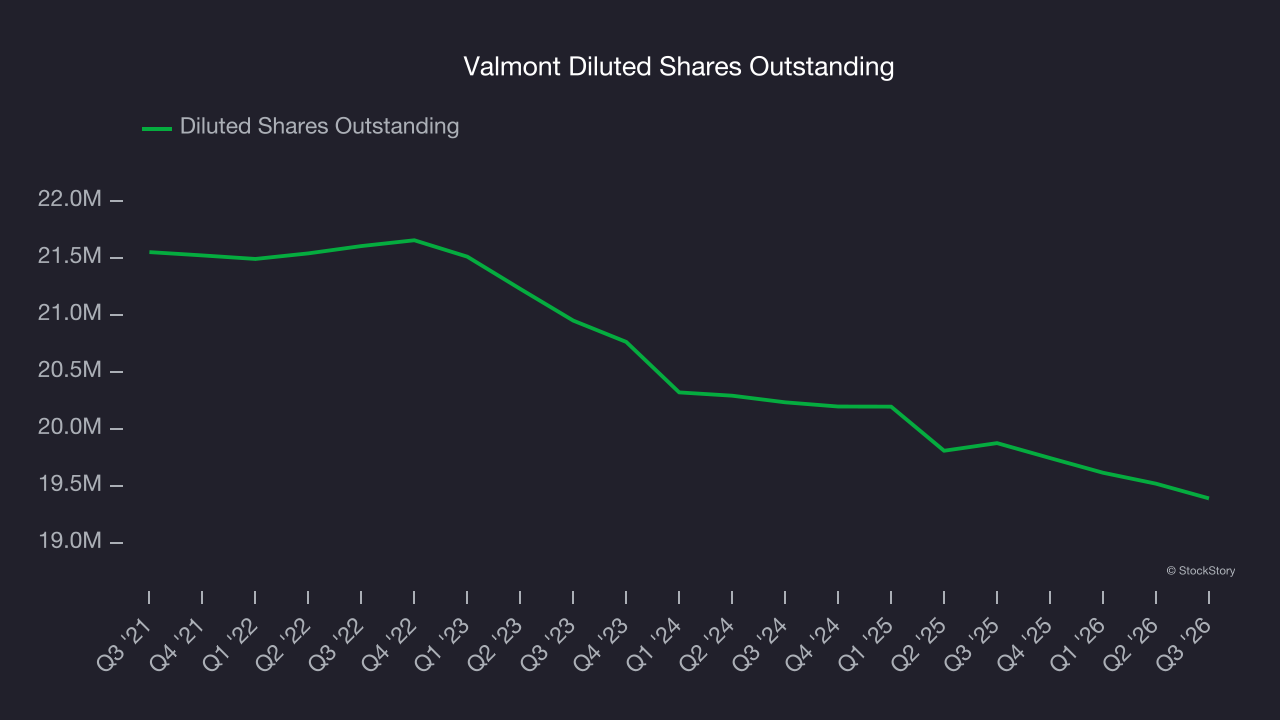
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Valmont, its two-year annual EPS growth of 18% was higher than its five-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, Valmont reported adjusted EPS of $6.24, up from $4.98 in the same quarter last year. This print beat analysts’ estimates by 9%. We also like to analyze expected EPS growth based on Wall Street analysts’ consensus projections, but there is insufficient data.
Key Takeaways from Valmont’s Q3 Results
We were impressed by how significantly Valmont blew past analysts’ EBITDA expectations this quarter. We were also glad its full-year EPS guidance slightly exceeded Wall Street’s estimates. On the other hand, its revenue slightly missed. Overall, this print had some key positives. The stock remained flat at $453.32 immediately after reporting.
Valmont may have had a good quarter, but does that mean you should invest right now? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).