
Steel wire manufacturer Insteel (NYSE: IIIN) reported calendar Q3 2026 (fiscal Q4 2026) results exceeding the market’s revenue expectations, with sales up 17.9% year on year to $209.3 million. Its GAAP profit of $0.40 per share was 13% below analysts’ consensus estimates.
Is now the time to buy Insteel? Find out by accessing our full research report, it’s free.
Insteel (IIIN) Q3 CY2026 highlights:
- Revenue: $209.3 million vs analyst estimates of $201.3 million (17.9% year-on-year growth, 4% beat)
- EPS (GAAP): $0.40 vs analyst expectations of $0.46 (13% miss)
- Operating Margin: 4.8%, down from 10.7% in the same quarter last year
- Free Cash Flow was $15.5 million, up from -$18.73 million in the same quarter last year
- Market Capitalization: $588.3 million
“Our fourth quarter results reflect the challenging cost environment we have navigated for the last two years,” commented H.O. Woltz III, Insteel’s President and CEO. “Domestic wire rod prices remain at historically high levels, well above prices in global markets, while availability continues to be constrained, thereby requiring the Company to supplement domestic purchases with offshore purchases and accept the working capital implication of elevated import volumes. Higher freight costs and persistent inflation affecting most of our cost structure continue to challenge the Company. While we have recovered a substantial portion of elevated costs through price increases, rising costs are relentless. From a demand perspective, publicly funded infrastructure activity continues to provide a solid foundation for our business, while ongoing investment in data center projects constitutes the bulk of the activity we see in private nonresidential construction. Our pursuit of additional growth opportunities within our engineered structural mesh business has broadened our customer base and supported shipment growth. We expect this trend to continue throughout 2027.”
Company overview
Growing from a small wire manufacturer to one of the largest in the U.S., Insteel (NYSE: IIIN) provides steel wire reinforcing products for concrete.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Insteel’s 4.6% annualized revenue growth over the last five years was tepid. This fell short of our benchmark for the industrials sector and is a rough starting point for our analysis.
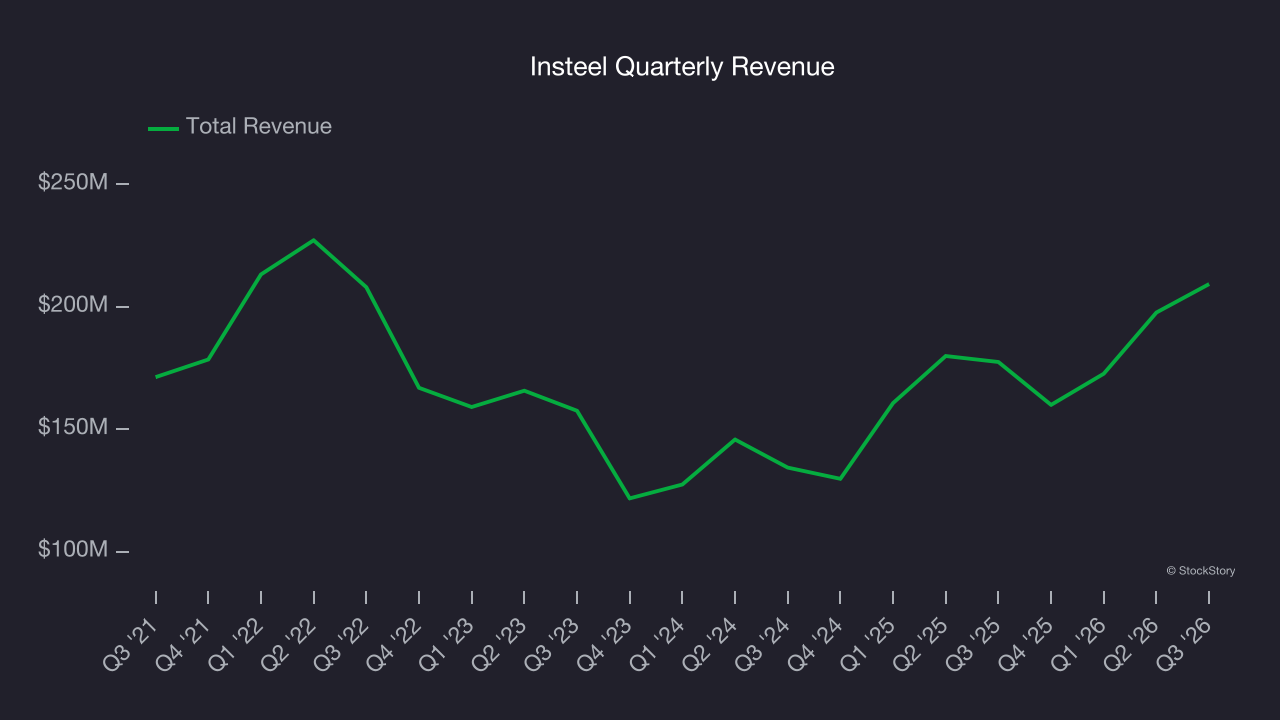
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Insteel’s annualized revenue growth of 18.2% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 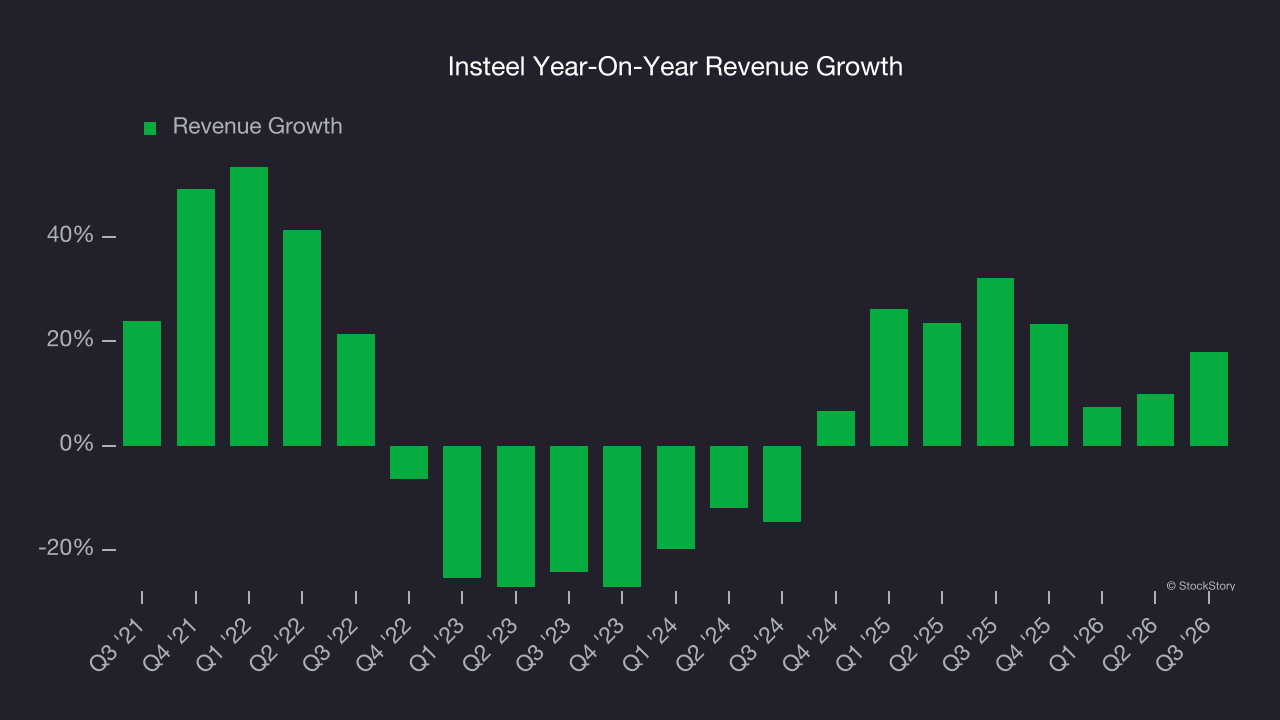
This quarter, Insteel reported year-on-year revenue growth of 17.9%, and its $209.3 million of revenue exceeded Wall Street’s estimates by 4%.
Looking ahead, sell-side analysts expect revenue to grow 7.4% over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Insteel has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 9.1%, higher than the broader industrials sector.
Looking at the trend in its profitability, Insteel’s operating margin decreased by 14.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
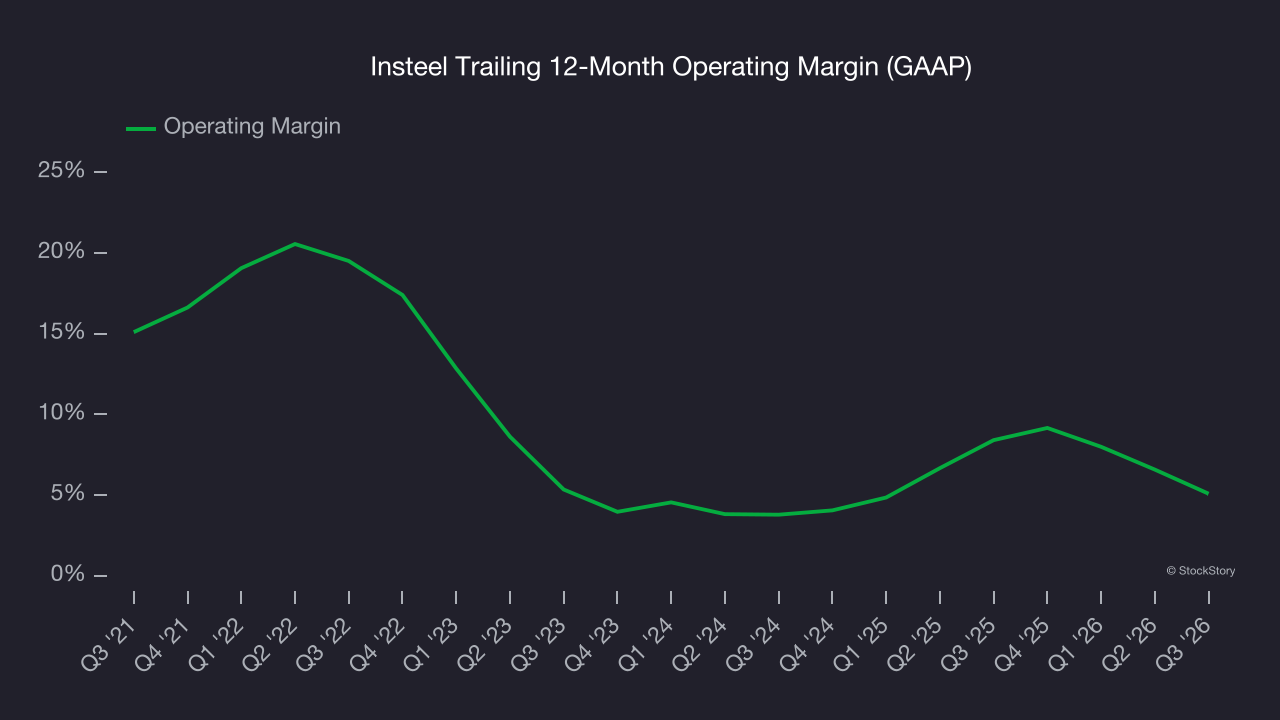
In Q3, Insteel generated an operating margin profit margin of 4.8%, down 5.9 percentage points year on year. Since Insteel’s gross margin decreased more than its operating margin, we can assume its recent inefficiencies were driven more by weaker leverage on its cost of sales rather than increased marketing, R&D, and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for Insteel, its EPS declined by 14.9% annually over the last five years while its revenue grew by 4.6%. This tells us the company became less profitable on a per-share basis as it expanded.
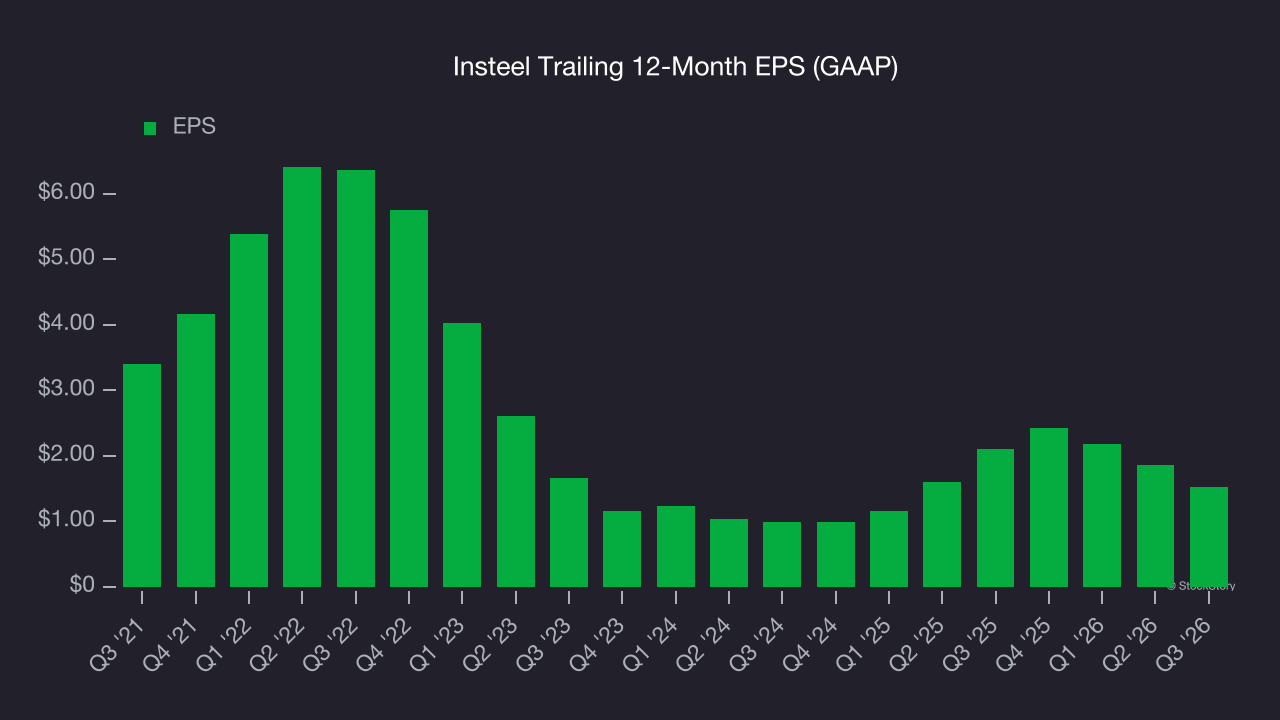
Diving into the nuances of Insteel’s earnings can give us a better understanding of its performance. As we mentioned earlier, Insteel’s operating margin declined by 14.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Insteel, its two-year annual EPS growth of 23.9% was higher than its five-year trend. This acceleration made it one of the faster-growing industrials companies in recent history.
In Q3, Insteel reported EPS of $0.40, down from $0.74 in the same quarter last year. This print missed analysts’ estimates. Over the next 12 months, Wall Street expects Insteel’s full-year EPS to grow 50.7% from $1.52 to $2.29.
Key takeaways from Insteel’s Q3 results
We were impressed by how significantly Insteel blew past analysts’ revenue expectations this quarter. On the other hand, its EPS missed. Overall, this was a weaker quarter. The stock traded down 7.3% to $28.18 immediately following the results.
Big picture, is Insteel a buy here and now? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).