
Industrial supplies company MSC Industrial Direct (NYSE: MSM) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 (fiscal Q4 2026), with sales up 10.3% year on year to $1.08 billion. Its non-GAAP profit of $1.45 per share was 3.1% above analysts’ consensus estimates.
Is now the time to buy MSC Industrial? Find out by accessing our full research report, it’s free.
MSC Industrial (MSM) Q3 CY2026 highlights:
- Revenue: $1.08 billion vs analyst estimates of $1.07 billion (10.3% year-on-year growth, 0.6% beat)
- Adjusted EPS: $1.45 vs analyst estimates of $1.41 (3.1% beat)
- Operating Margin: 6.7%, down from 8.6% in the same quarter last year
- Free Cash Flow Margin: 5.9%, similar to the same quarter last year
- Market Capitalization: $7.42 billion
Company overview
Founded in NYC’s Little Italy, MSC Industrial Direct (NYSE: MSM) provides industrial supplies and equipment, offering vast and reliable selection for customers such as contractors
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, MSC Industrial’s sales grew at a sluggish 4.3% compounded annual growth rate over the last five years. This fell short of our benchmark for the industrials sector and is a rough starting point for our analysis.
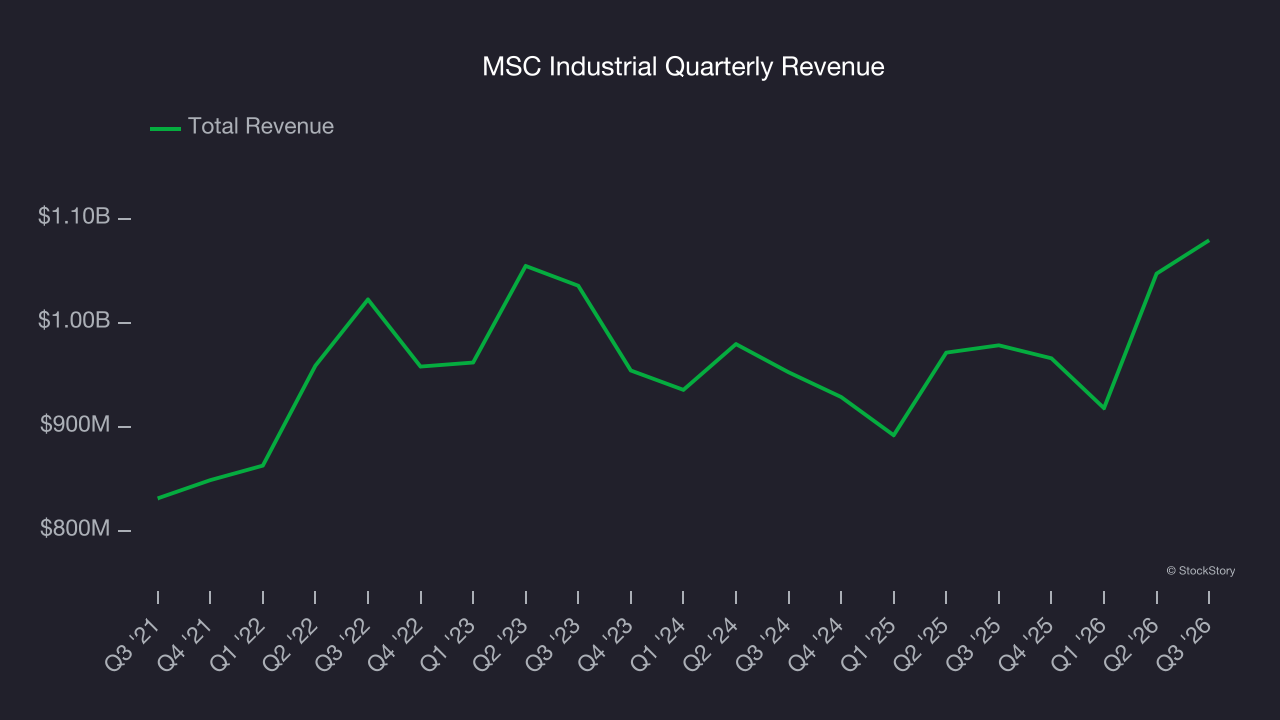
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. MSC Industrial’s recent performance shows its demand has slowed as its annualized revenue growth of 2.4% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 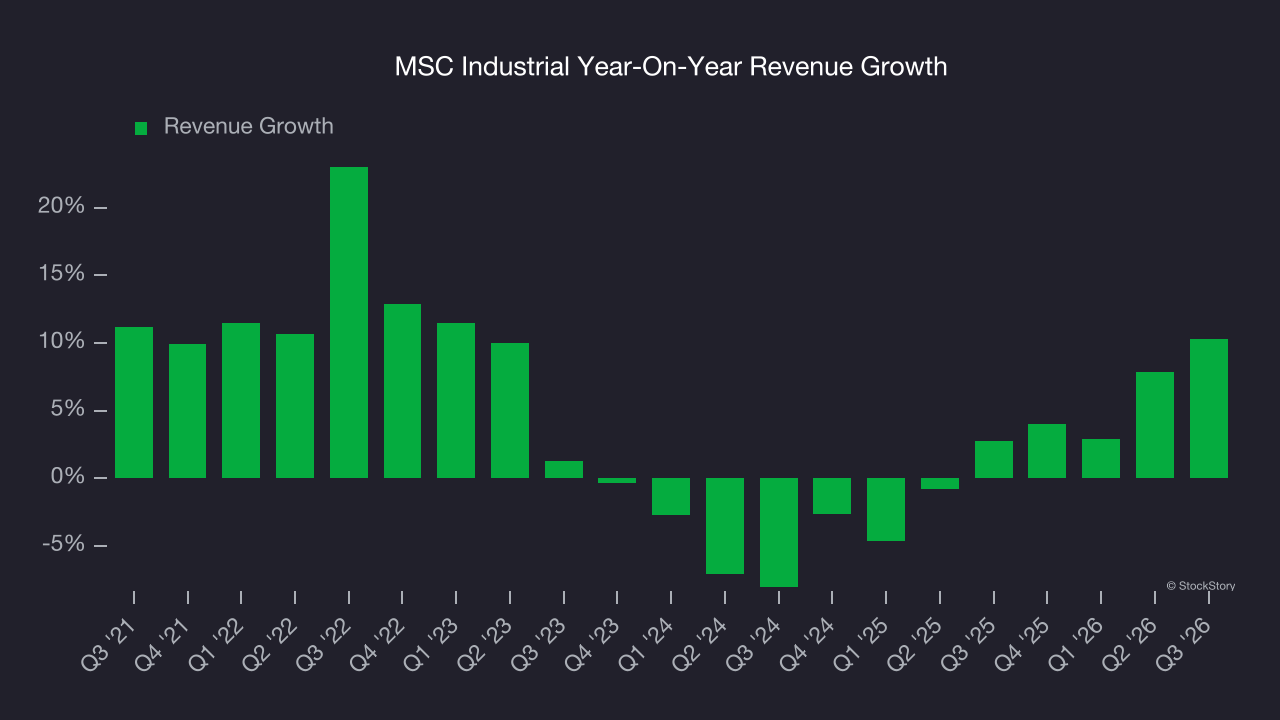
This quarter, MSC Industrial reported year-on-year revenue growth of 10.3%, and its $1.08 billion of revenue exceeded Wall Street’s estimates by 0.6%.
Looking ahead, sell-side analysts expect revenue to grow 7.1% over the next 12 months. While this projection suggests its newer products and services will catalyze better top-line performance, it is still below average for the sector.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating margin
MSC Industrial has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 10.2%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Looking at the trend in its profitability, MSC Industrial’s operating margin decreased by 4.7 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
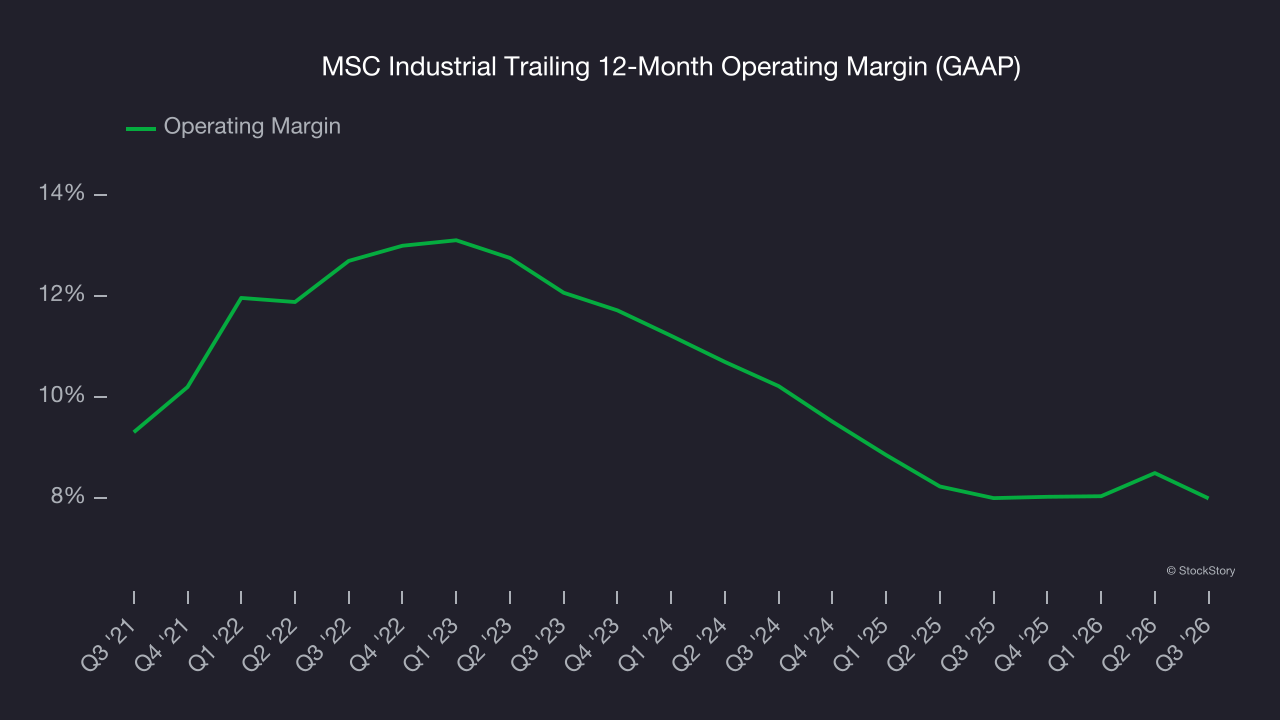
This quarter, MSC Industrial generated an operating margin profit margin of 6.7%, down 1.9 percentage points year on year. Since MSC Industrial’s operating margin decreased more than its gross margin, we can assume it was less efficient because expenses such as marketing, R&D, and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
MSC Industrial’s flat EPS over the last five years was below its 4.3% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
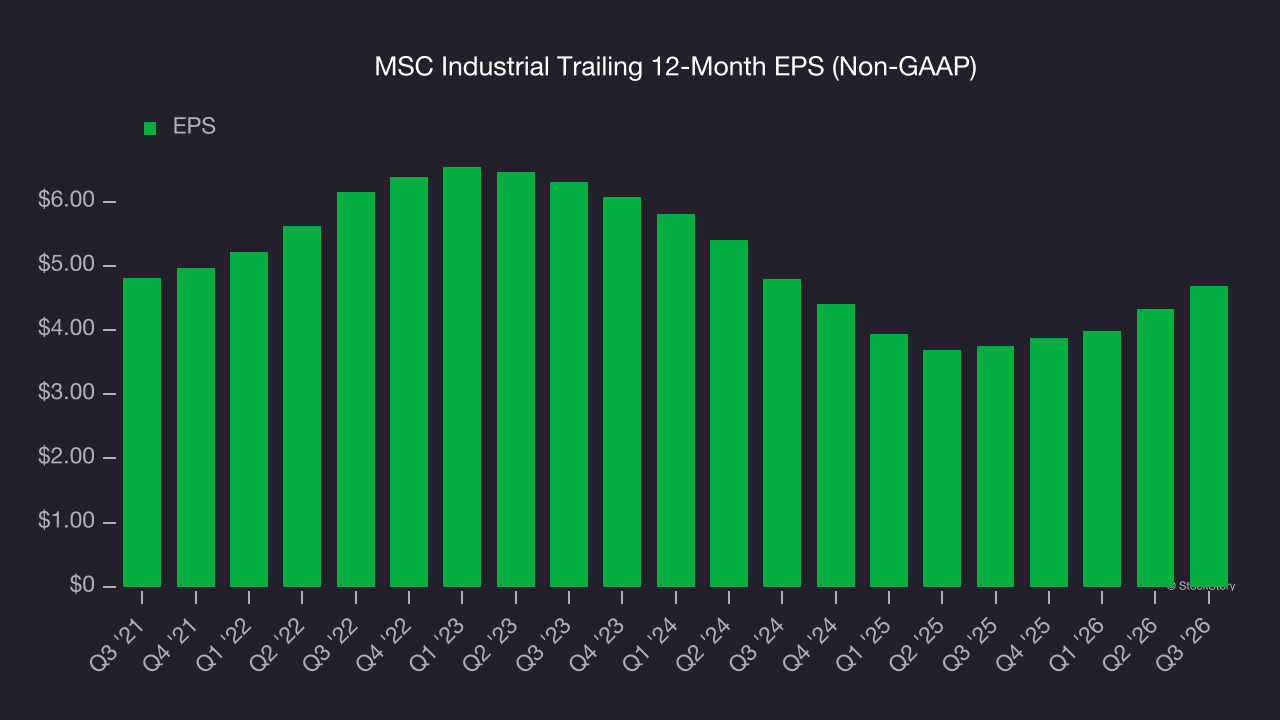
We can take a deeper look into MSC Industrial’s earnings to better understand the drivers of its performance. As we mentioned earlier, MSC Industrial’s operating margin declined by 4.7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For MSC Industrial, its two-year annual EPS declines of 1% are similar to its five-year trend. These results were bad no matter how you slice the data.
In Q3, MSC Industrial reported adjusted EPS of $1.45, up from $1.09 in the same quarter last year. This print beat analysts’ estimates by 3.1%. Over the next 12 months, Wall Street expects MSC Industrial’s full-year EPS to grow 18.2% from $4.69 to $5.54.
Key takeaways from MSC Industrial’s Q3 results
It was good to see MSC Industrial narrowly top analysts’ revenue expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $132.78 immediately after reporting.
Should you buy the stock or not? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).