Oilfield equipment manufacturer NOV (NYSE: NOV) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 2.3% year on year to $2.23 billion. Its GAAP profit of $0.25 per share was in line with analysts’ consensus estimates.
For more on NOV, read our free full research report.
NOV (NOV) Q3 2026 highlights:
- Revenue $2.23 billion vs S&P analysts’ consensus estimates of $2.19 billion (2.3% year-on-year growth, 1.5% beat)
- EPS (GAAP) $0.25 vs analysts’ consensus estimates of $0.25 (in line)
- Adjusted EBITDA $281 million vs analysts’ consensus estimates of $256.7 million (12.6% margin, 9.5% beat)
- Operating margin 6.4%, up from 4.9% in the same quarter last year
- Free cash flow -$47 million, down from $245 million in the same quarter last year
- Other production down -39.3% year on year
- Market capitalization $7.20 billion
“NOV delivered another strong quarter, building on the operational momentum established earlier this year,” said Jose Bayardo, Chairman, President, and CEO. “The solid sequential and year-over-year revenue growth reflects our continued focus on supporting customers in the Middle East and ramping manufacturing throughput against our growing backlog of capital equipment orders in our Energy Products and Services segment. Strong Adjusted EBITDA flowthrough, excluding tariff refund benefits, reflects disciplined execution, continued efficiency gains, and our efforts to better leverage NOV’s global platform.
Revenue growth
Cyclical industries such as energy can make mediocre companies look strong for a time, but a long-term view reveals which businesses can withstand and adapt to changing conditions. Over the last five years, NOV grew its revenue at a decent 10.3% compounded annual growth rate. Its growth was slightly above the average energy upstream and integrated energy company and shows its offerings resonate with customers.
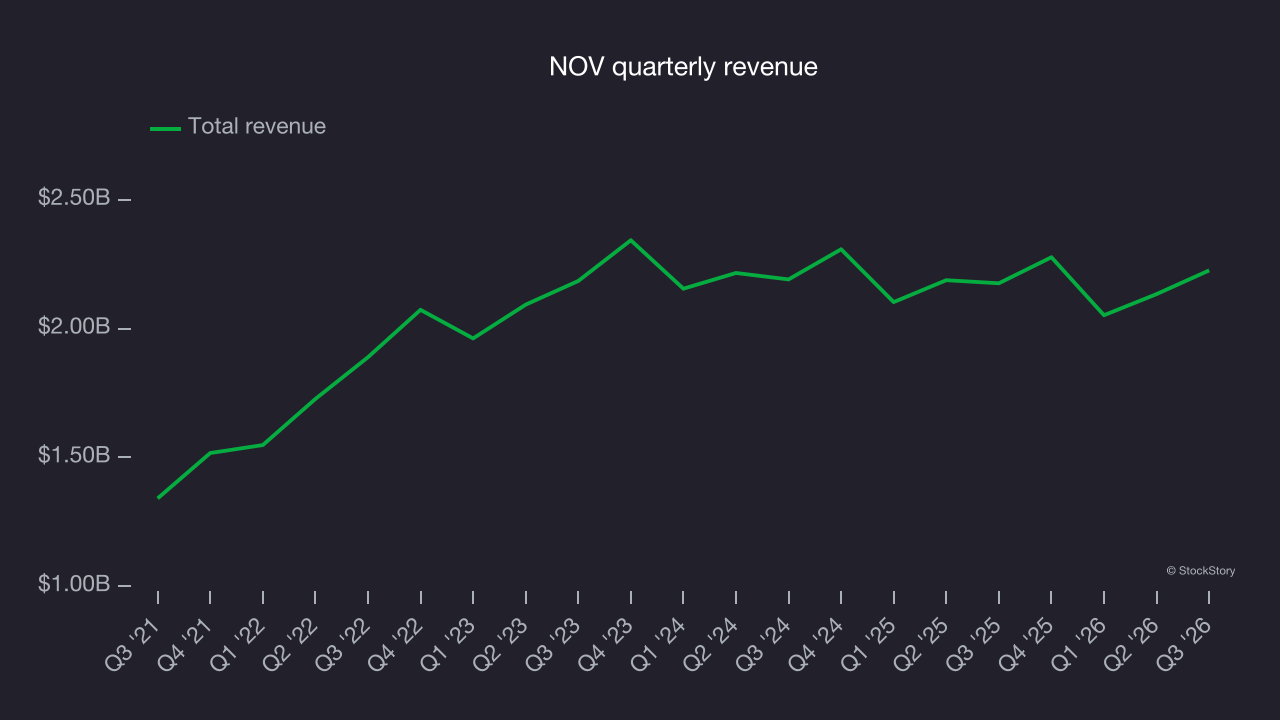
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. NOV’s annualized revenue growth of 0.5% over the last ten years is below its five-year trend, but the results were still respectable.
While looking at revenue is important, it can also introduce noise around commodity prices and M&A. Analyzing drivers of revenue, on the other hand, highlights what is happening inside the asset base and whether the economic footprint of a company is expanding. Over the last two years, NOV’s other production averaged 4% year-on-year declines.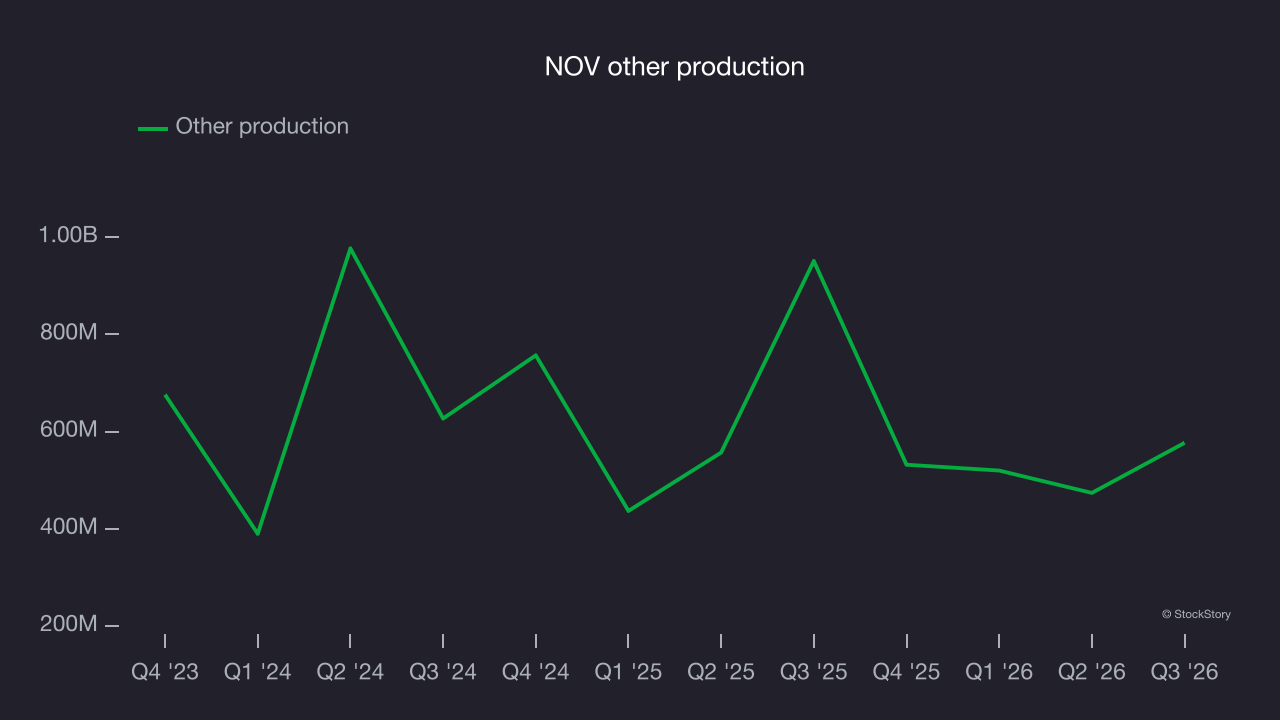
This quarter, NOV reported modest year-on-year revenue growth of 2.3% but beat Wall Street’s consensus estimates by 1.5%. NOV’s Other production fell by 39.3% year on year.
Adjusted EBITDA margin
NOV was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 11.2% was among the worst in the energy upstream and integrated energy sector.
On the positive side, NOV’s EBITDA margin rose by 3.9 percentage points over the last year.
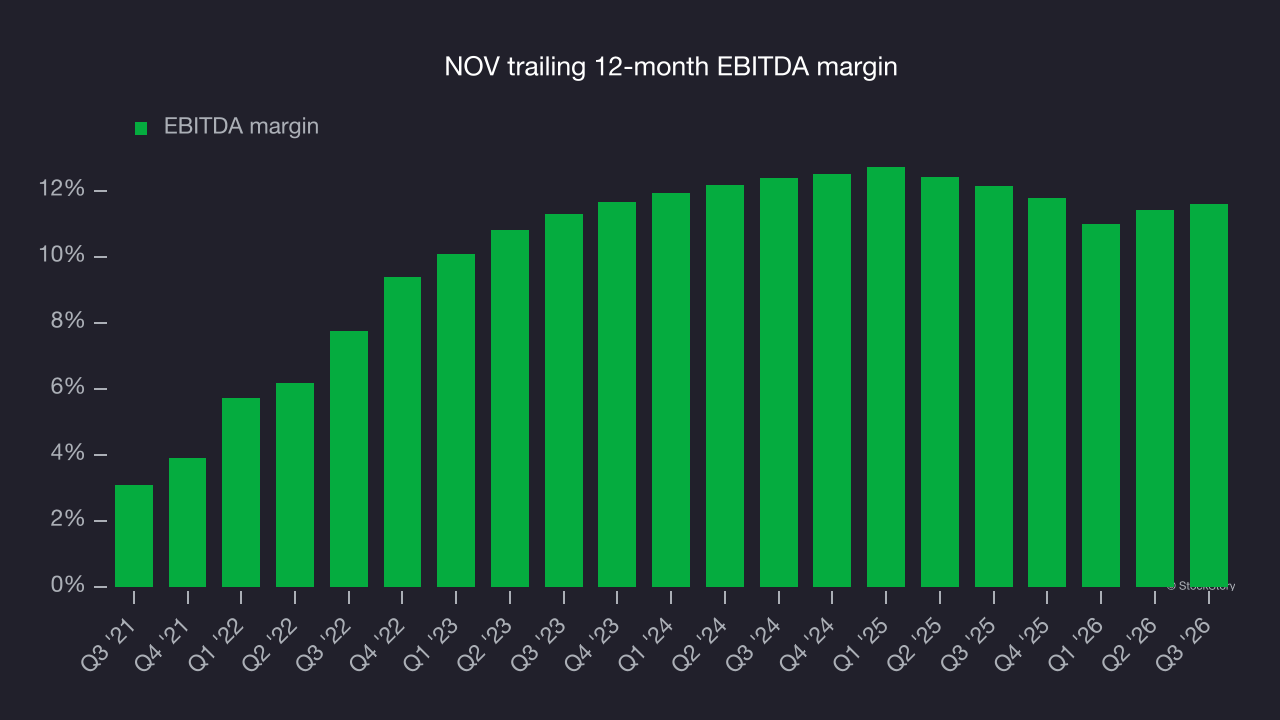
In Q3, NOV generated an EBITDA margin of 12.6%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable. Its adjusted EBITDA beat Wall Street’s consensus estimates by 9.5%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing “rock” is before financing and reinvestment, while free cash flow shows how much value remains after paying to replace those wells. Because production declines over time, strong EBITDA can coexist with weak FCF if drilling is expensive or declines are steep. FCF therefore captures both operating efficiency and the cost of sustaining production.
NOV has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.6%, below expectations for an upstream and integrated energy business.
While the level of free cash flow margins is important, their consistency matters just as much.
NOV’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 28.6 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why assess stability against commodity prices using free cash flow rather than comparing revenue or EBITDA to WTI crude prices in NOV’s case? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
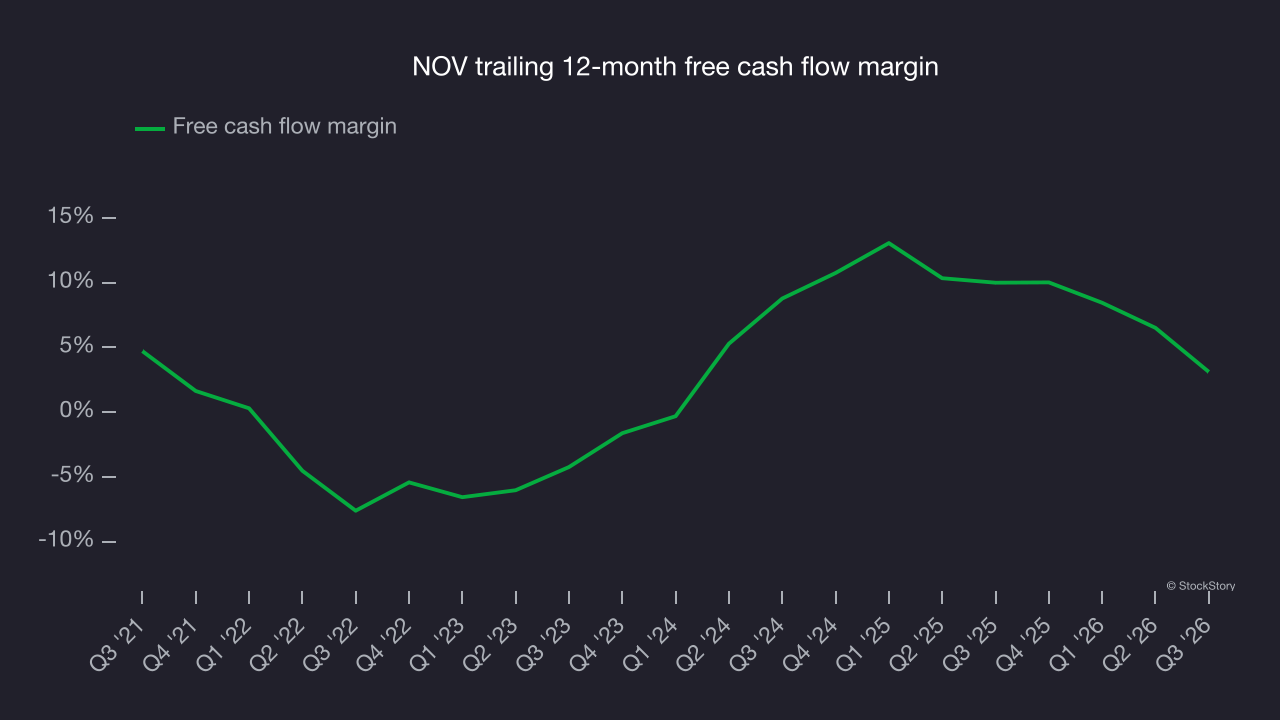
NOV used $47 million of cash in Q3, equivalent to a negative 2.1% margin. The company’s cash flow turned negative after being positive in the same quarter last year, warranting closer attention. Short-term fluctuations typically aren’t a major concern because investment needs can be seasonal, but whether the trend continues into future quarters bears watching.
Key takeaways from NOV’s Q3 results
NOV delivered a solid quarter, beating analysts’ consensus estimates for EBITDA and narrowly topping Wall Street’s revenue expectations. Those were positives, but the market seemed to be hoping for more. Shares fell 2.5% to $20.05 immediately after the report.
To assess whether to invest in NOV, consider its valuation, business quality and latest quarterly results. For more on these factors, read the full research report here (it’s free).