Grocery store chain Sprouts Farmers Market (NASDAQ: SFM) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 4.7% year on year to $2.30 billion. Its GAAP profit of $1.21 per share was 1.4% below analysts’ consensus estimates.
For more on Sprouts, read our free full research report.
Sprouts (SFM) Q3 2026 highlights:
- Revenue $2.30 billion vs S&P analysts’ consensus estimates of $2.33 billion (4.7% year-on-year growth, 1.3% miss)
- EPS (GAAP) $1.21 vs analysts’ consensus estimates of $1.23 (1.4% miss)
- Adjusted EBITDA $200.5 million vs analysts’ consensus estimates of $198.3 million (8.7% margin, 1.1% beat)
- GAAP EPS guidance $0.49 at the midpoint for Q4 2026, missing analysts’ consensus estimates
- Operating margin 6.6%, in line with the same quarter last year
- Free cash flow margin 4%, down from 5.1% in the same quarter last year
- Locations 504 at quarter end, up from 464 in the same quarter last year
- Same-store sales were flat year on year (5.9% in the same quarter last year)
- Market capitalization $6.01 billion
“While a challenging consumer environment and the cyclospora disruption affected the quarter, we recognize the need to improve our performance and are taking action to strengthen execution and drive traffic,” said Jack Sinclair, chief executive officer of Sprouts Farmers Market. “We are increasing investments to enhance affordability and deepen customer engagement, while building on the differentiated assortment and experience that define Sprouts. I want to thank our teams for their dedication, including opening a record 15 new stores during the quarter. The strong performance of our recent store vintages and continued momentum in unit growth reinforce our confidence in the significant opportunity ahead for Sprouts.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $9.11 billion in revenue over the past 12 months, Sprouts is a mid-sized retailer, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale. On the positive side, it can still achieve high growth rates because it’s working from a smaller revenue base.
Sprouts’s revenue grew at a decent 10.7% compounded annual growth rate over the last three years as it opened new stores and increased revenue at existing, established locations.
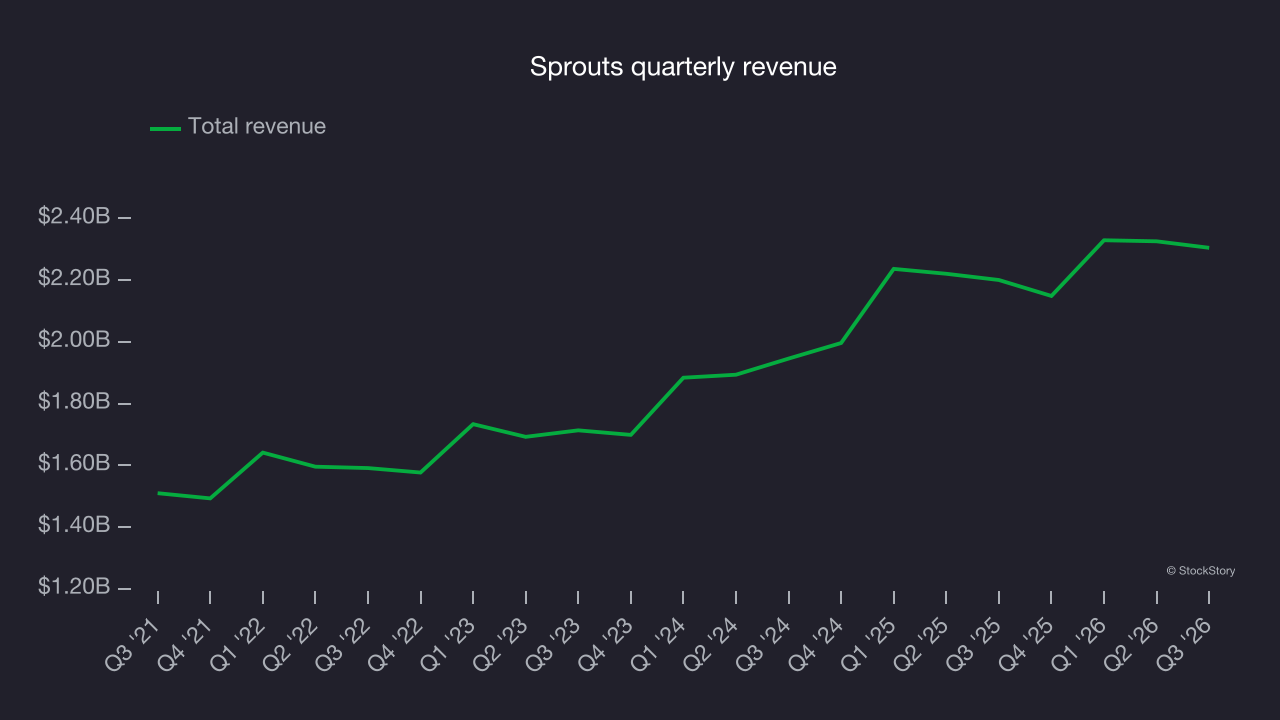
This quarter, Sprouts’s revenue grew by 4.7% year on year to $2.30 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 11.4% over the next 12 months, according to S&P, similar to its three-year rate. This strong growth projection implies the market expects its products to succeed.
Store performance
Number of stores
The number of stores a retailer operates is a critical driver of how quickly company-level revenue can grow.
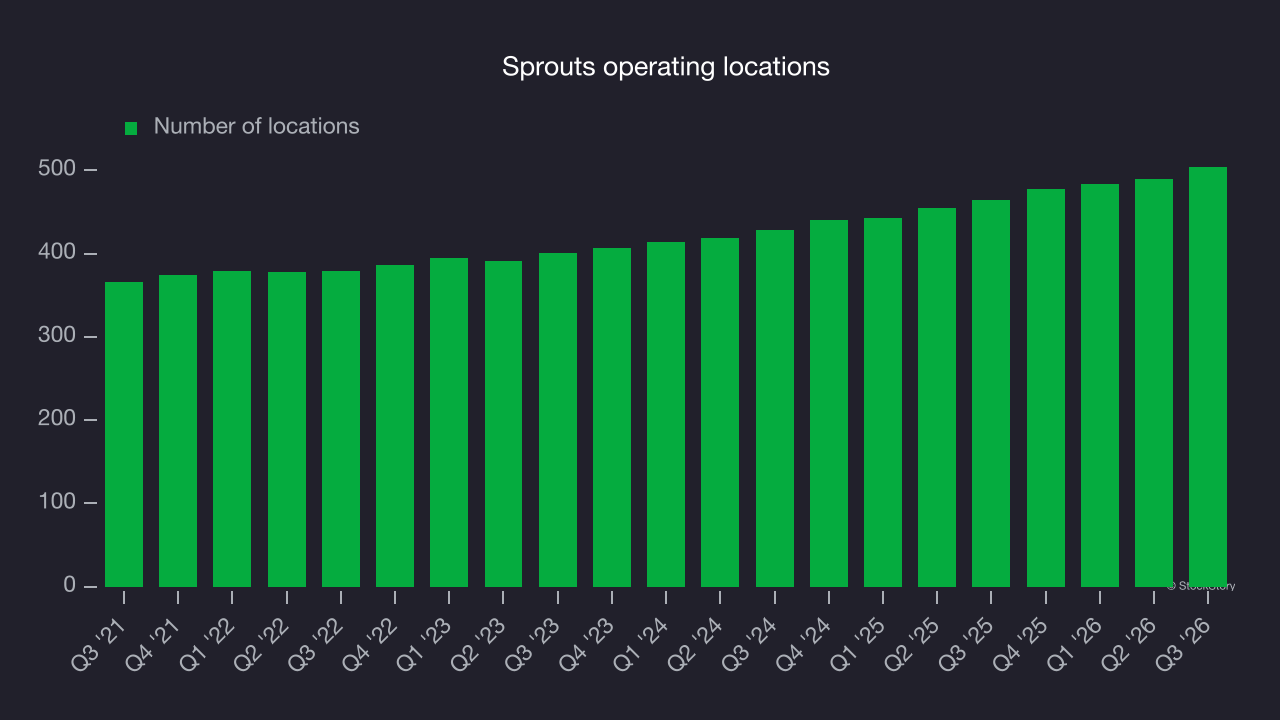
Sprouts operated 504 locations in the latest quarter. It has opened new stores at a rapid pace over the last two years, averaging 8.2% annual growth, much faster than the broader consumer retail sector. This gives it a chance to become a large-scale business over time.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-store sales
A company’s store base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. The same-store sales metric provides insight into this topic because it measures organic growth for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year.
Sprouts has been one of the most successful retailers over the last two years thanks to strong demand within its existing locations. On average, the company has posted strong year-on-year same-store sales growth of 4.7%. This performance suggests its rollout of new stores is beneficial for shareholders. This favorable backdrop gives Sprouts multiple avenues for revenue growth: new stores, e-commerce or increased foot traffic and higher revenue per customer at existing locations.
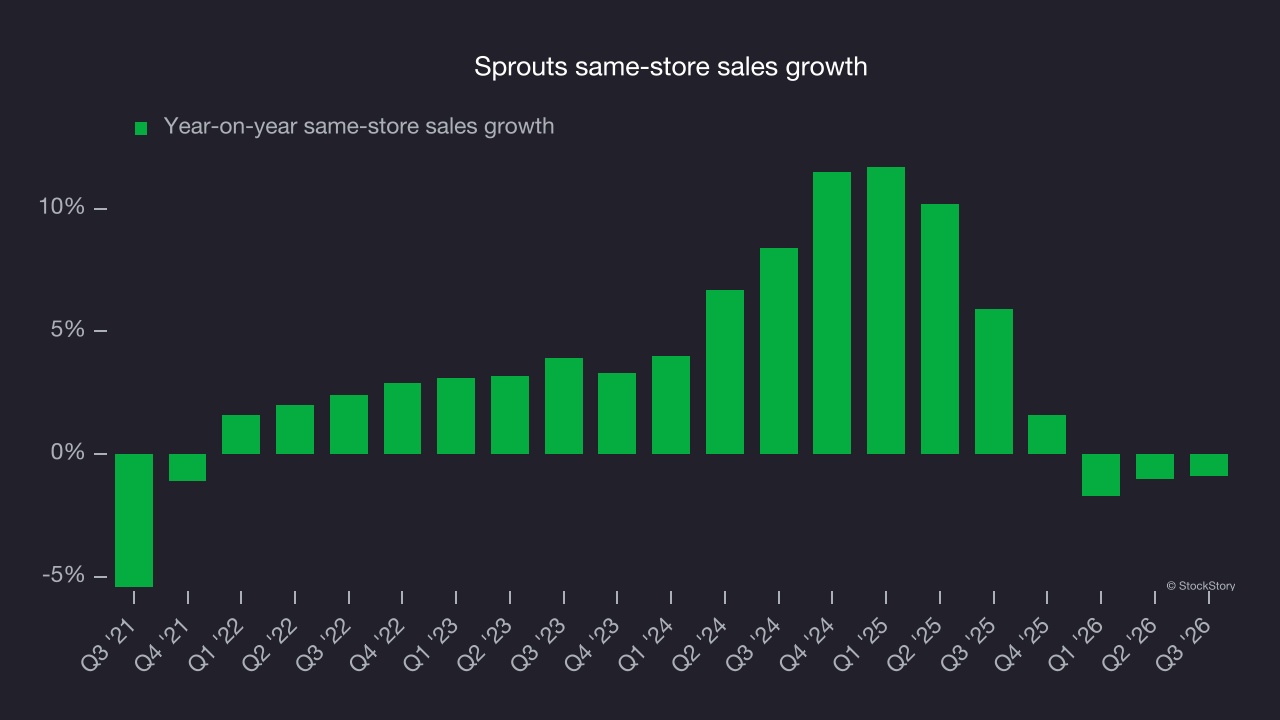
In the latest quarter, Sprouts’s year-on-year same-store sales were flat. This was a meaningful deceleration from its historical levels. The question now is whether Sprouts can reaccelerate growth.
Key takeaways from Sprouts’s Q3 results
Sprouts delivered a softer quarter, with revenue slightly below Wall Street’s consensus estimates and next-quarter EPS guidance also missing expectations. A narrow beat on analysts’ consensus EBITDA estimates was a positive, but the results were weaker overall. Shares plunged 16.9% to $51.66 immediately after the release.
Sprouts underperformed this quarter, but that alone does not determine whether the stock is worth buying. The latest results matter, but longer-term business quality and valuation are more important when deciding whether to invest. For more on Sprouts, read our full research report here (it’s free).