
As the craze of earnings season draws to a close, here’s a look back at some of the most exciting (and some less so) results from Q2. Today, we are looking at beauty and cosmetics retailer stocks, starting with Ulta (NASDAQ: ULTA).
Beauty and cosmetics retailers understand that beauty is in the eye of the beholder, but a little lipstick, nail polish, and glowing skin also help the cause. These stores—which mostly cater to consumers but can also garner the attention of salon pros—aim to be a one-stop personal care and beauty products shop with many brands across many categories. E-commerce is changing how consumers buy cosmetics, so these retailers are constantly evolving to meet the customer where and how they want to shop.
The 4 beauty and cosmetics retailer stocks we track reported a satisfactory Q2. As a group, revenues were in line with analysts’ consensus estimates.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Best Q2: Ulta (NASDAQ: ULTA)
Offering high-end prestige brands as well as lower-priced, mass-market ones, Ulta Beauty (NASDAQ: ULTA) is an American retailer that sells makeup, skincare, haircare, and fragrance products.
Ulta reported revenues of $3.04 billion, up 8.9% year on year. This print exceeded analysts’ expectations by 1.8%. Overall, it was a strong quarter for the company with a beat of analysts’ EPS estimates and full-year EPS guidance meeting analysts’ expectations.
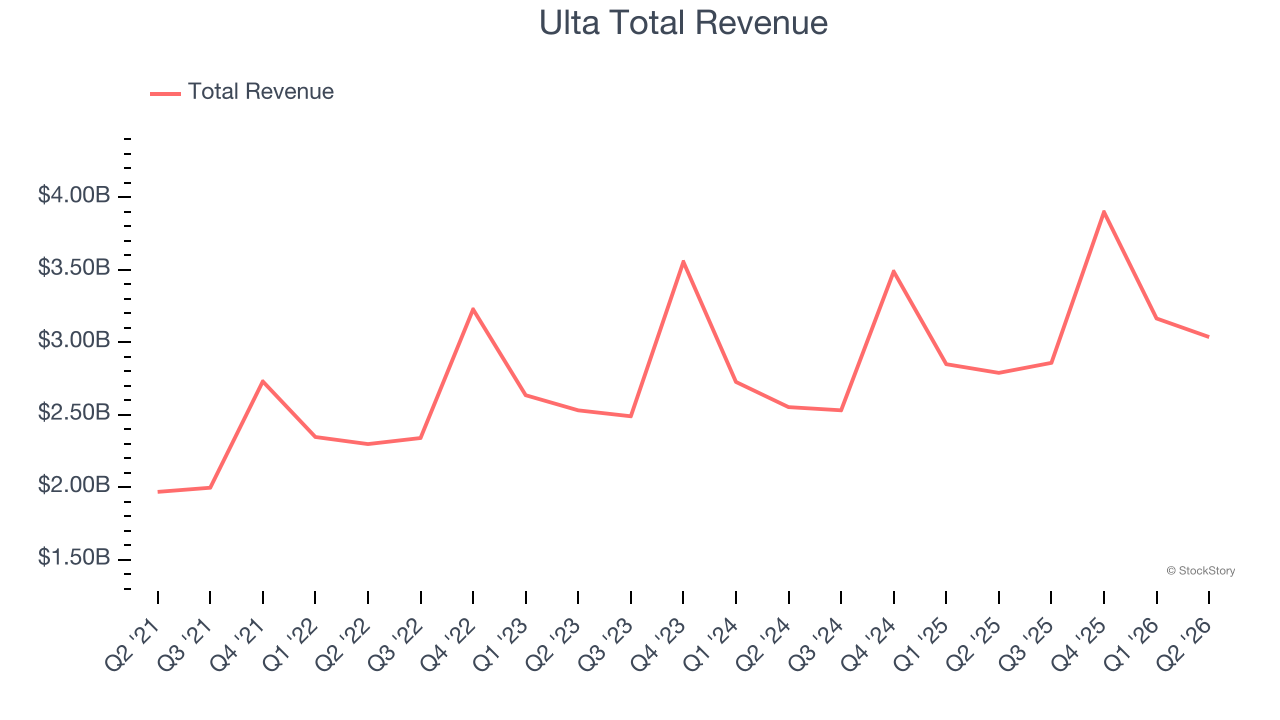
Ulta achieved the biggest analyst estimate beat among its peers. Unsurprisingly, the stock is up 1.3% since reporting and currently trades at $547.30.
We think Ulta is a good business, but is it a buy today? Read our full report here, it’s free.
Warby Parker (NYSE: WRBY)
Founded in 2010, Warby Parker (NYSE: WRBY) designs, manufactures, and sells eyewear, including prescription glasses, sunglasses, and contact lenses, through its e-commerce platform and physical retail locations.
Warby Parker reported revenues of $235.5 million, up 9.8% year on year, falling short of analysts’ expectations by 1%. However, the business still had a satisfactory quarter with a beat of analysts’ EPS estimates but a miss of analysts’ gross margin estimates.
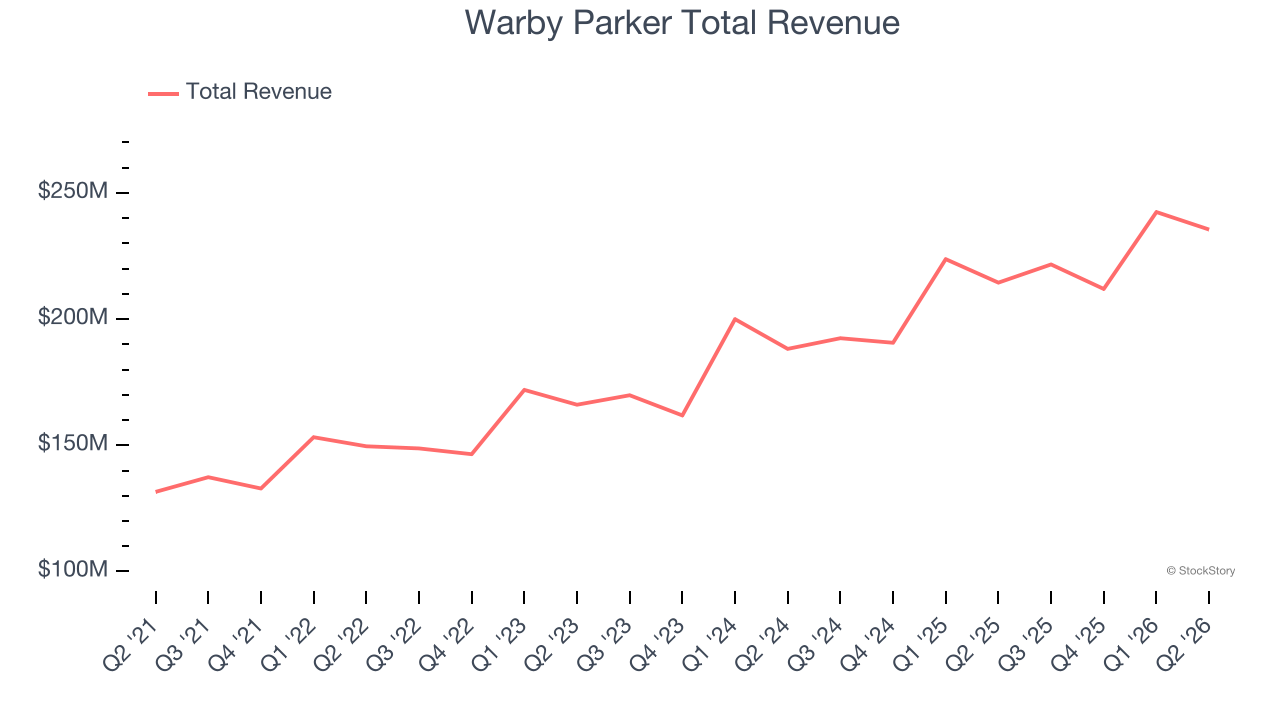
Warby Parker delivered the fastest revenue growth in the group. The company reported 2.71 million active customers, up 4.2% year on year. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 10.7% since reporting. It currently trades at $26.14.
Is now the time to buy Warby Parker? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: Sally Beauty (NYSE: SBH)
Catering to both everyday consumers as well as salon professionals, Sally Beauty (NYSE: SBH) is a retailer that sells salon-quality beauty products such as makeup and haircare products.
Sally Beauty reported revenues of $935.5 million, flat year on year, in line with analysts’ expectations. It was a mixed quarter as it posted a decent beat of analysts’ EBITDA estimates but full-year revenue guidance meeting analysts’ expectations.
Interestingly, the stock is up 9.8% since the results and currently trades at $16.44.
Read our full analysis of Sally Beauty’s results here.
Bath and Body Works (NYSE: BBWI)
Spun off from L Brands in 2020, Bath & Body Works (NYSE: BBWI) is a personal care and home fragrance retailer where consumers can find specialty shower gels, scented candles for the home, and lotions.
Bath and Body Works reported revenues of $1.51 billion, down 2.3% year on year. This number surpassed analysts’ expectations by 1.2%. Zooming out, it was a satisfactory quarter as it also produced a beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations significantly.
Bath and Body Works had the slowest revenue growth of the whole group. The stock is up 2.9% since reporting and currently trades at $18.09.
Read our full, actionable report on Bath and Body Works here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.