
Over the past six months, WeightWatchers has been a great trade, beating the S&P 500 by 21.5%. Its stock price has climbed to $15.46, representing a healthy 36.8% increase. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy WeightWatchers, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think WeightWatchers Will Underperform?
We’re happy investors have made money, but we don’t have much confidence in WeightWatchers. Here are three reasons why WW doesn’t excite us, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
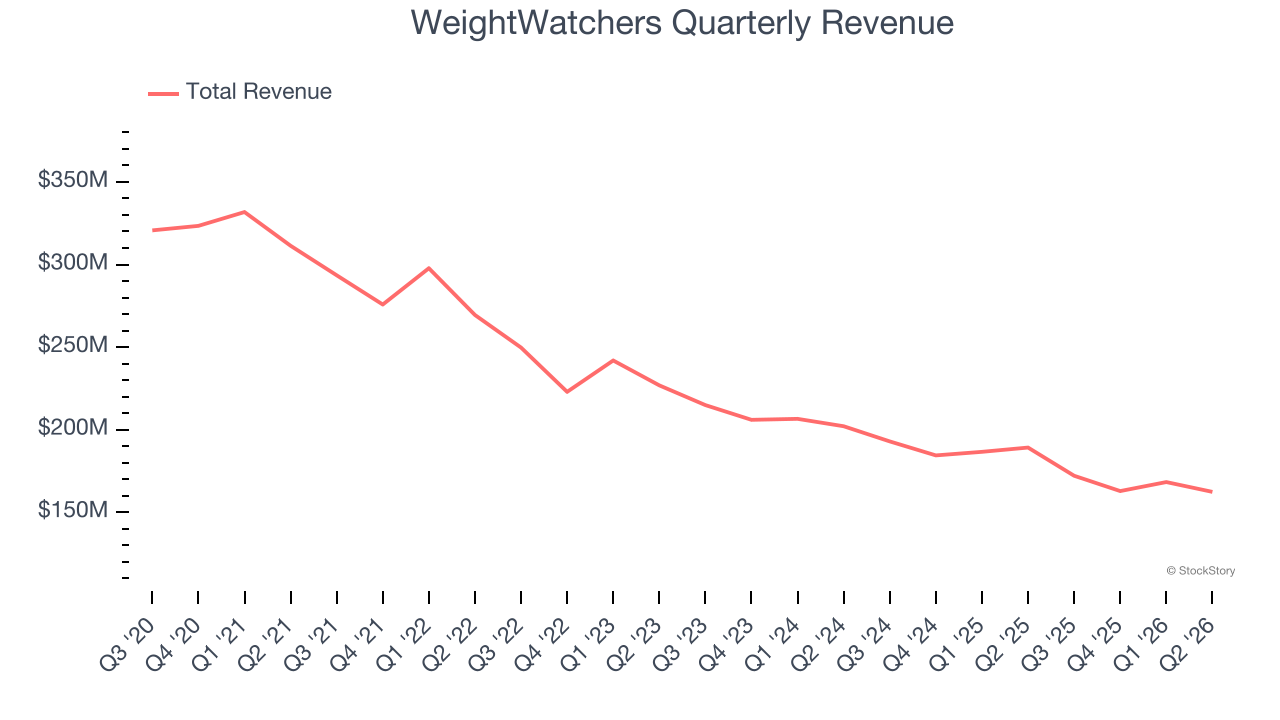
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. WeightWatchers struggled to consistently generate demand over the last five years as its sales dropped at a 12.4% annual rate. This was below our standards and is a sign of poor business quality.
2. Cash Burn Ignites Concerns
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
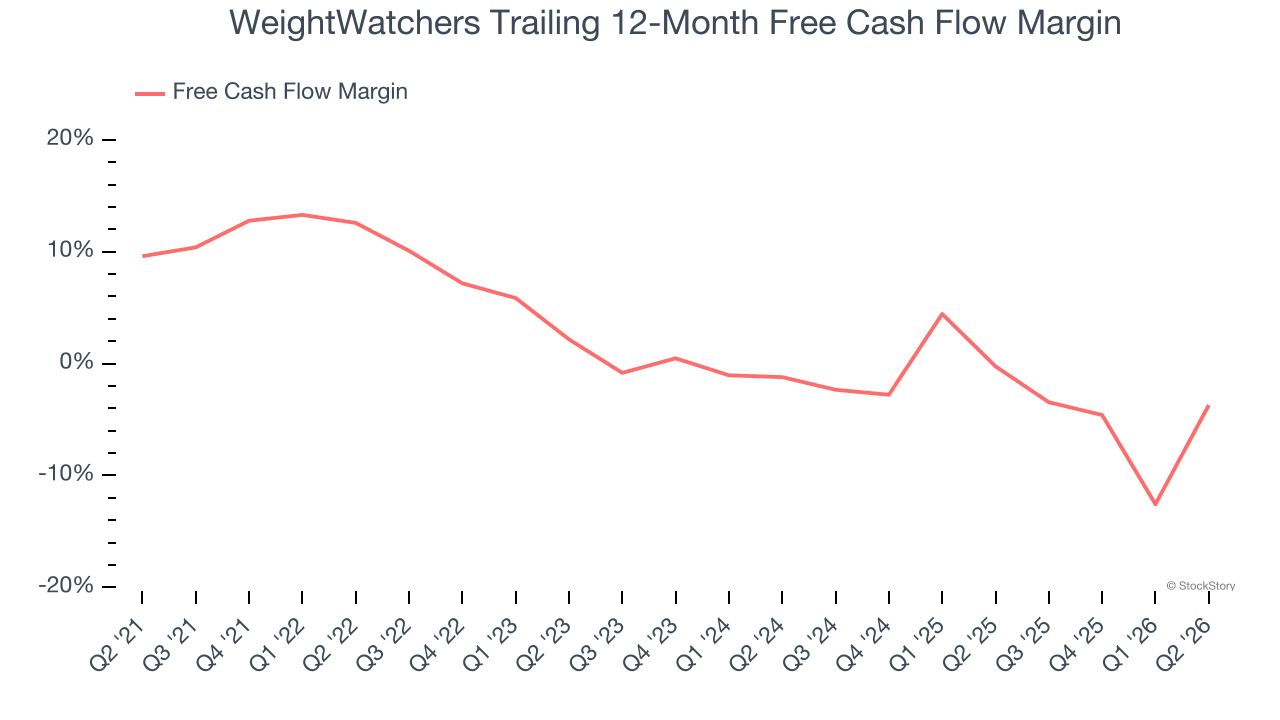
While WeightWatchers posted positive free cash flow this quarter, the broader story hasn’t been so clean. Over the last two years, WeightWatchers’s demanding reinvestments to stay relevant have drained its resources, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 1.9%, meaning it lit $1.87 of cash on fire for every $100 in revenue.
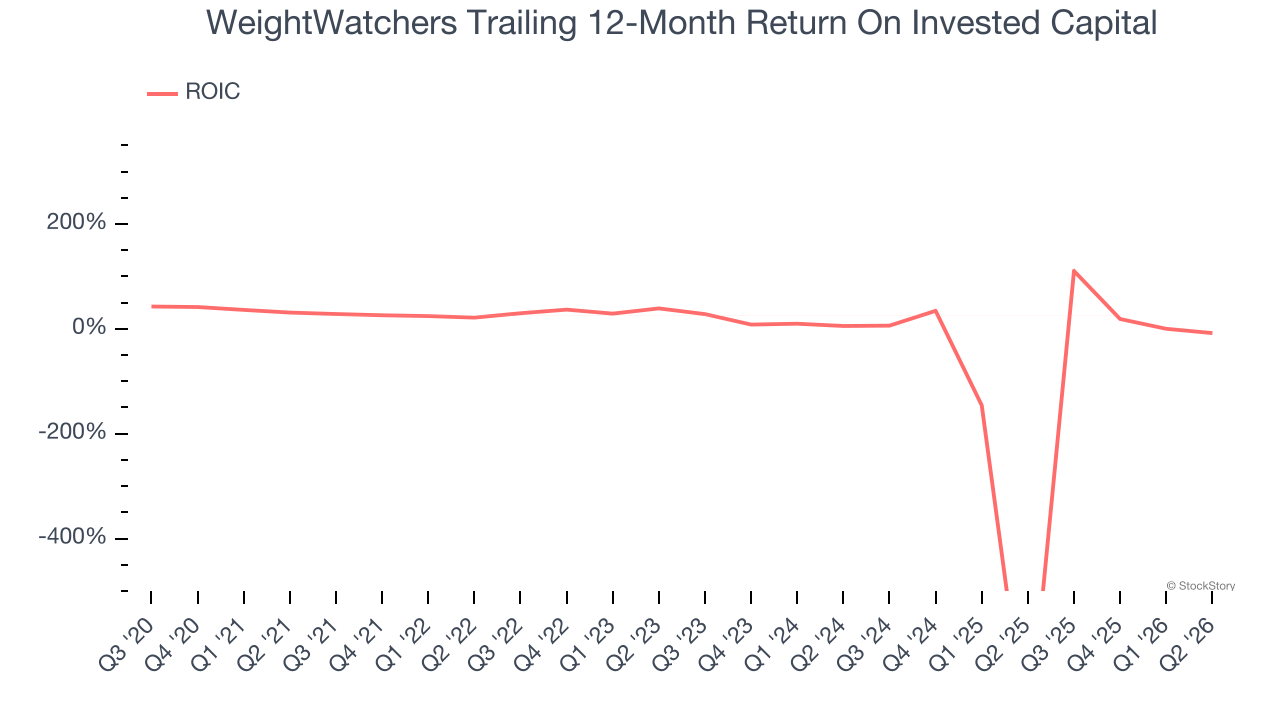
3. New Investments Fail to Bear Fruit as ROIC Declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, WeightWatchers’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
We see the value of companies helping consumers, but in the case of WeightWatchers, we’re out. With its shares topping the market in recent months, the stock trades at 4.1× forward EV-to-EBITDA (or $15.46 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are superior stocks to buy right now. Let us point you toward one of our top digital advertising picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.