Beverage company Keurig Dr Pepper (NASDAQ: KDP) met Wall Street’s revenue expectations in Q3 2026, with revenue up 70.6% year on year to $7.34 billion. On the other hand, the company’s full-year revenue guidance of $26.15 billion at the midpoint came in 0.6% below analysts’ consensus estimates. Its non-GAAP profit of $0.66 per share was 6.4% above analysts’ consensus estimates.
For more on Keurig Dr Pepper, read our free full research report.
Keurig Dr Pepper (KDP) Q3 2026 highlights:
- Revenue $7.34 billion vs S&P analysts’ consensus estimates of $7.33 billion (70.6% year-on-year growth, in line)
- Adjusted EPS $0.66 vs S&P analysts’ consensus estimates of $0.62 (6.4% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $26.15 billion at the midpoint
- Operating margin 18.2%, down from 23.1% in the same quarter last year
- Free cash flow margin 14%, up from 12.3% in the same quarter last year
- Market capitalization $50.11 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years.
With $23.13 billion in revenue over the past 12 months, Keurig Dr Pepper is one of the most widely recognized consumer staples companies. Its influence over consumers gives it negotiating leverage with distributors, enabling it to choose where it sells its products, an advantage many companies lack.
Keurig Dr Pepper’s revenue grew at a solid 16.2% compounded annual growth rate over the last three years as consumers bought more of its products.
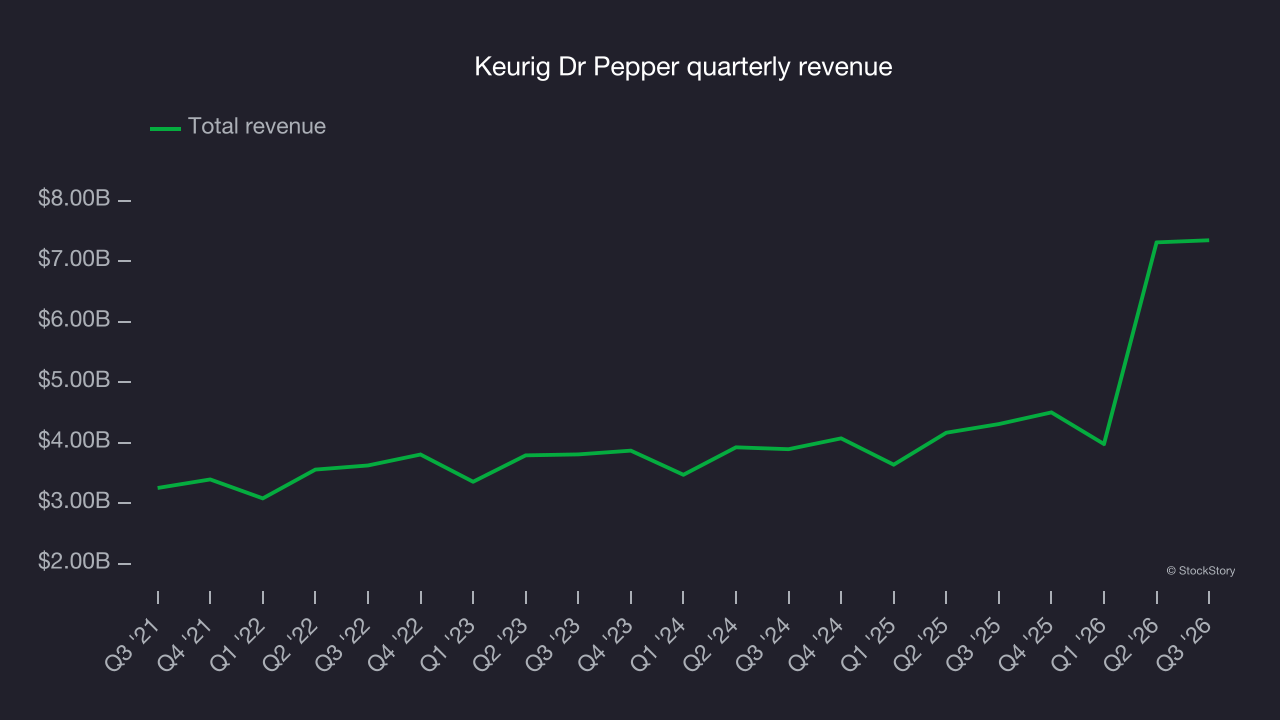
This quarter, Keurig Dr Pepper’s year-on-year revenue growth of 70.6% was strong, and its $7.34 billion in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 28.5% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is notable for a company of its scale and suggests its newer products will spur better revenue performance.
Cash flow
Earnings are valuable for assessing company performance, but cash is essential because accounting profits alone cannot pay the bills.
Keurig Dr Pepper has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 10.5% over the last two years, impressive for a consumer staples business.
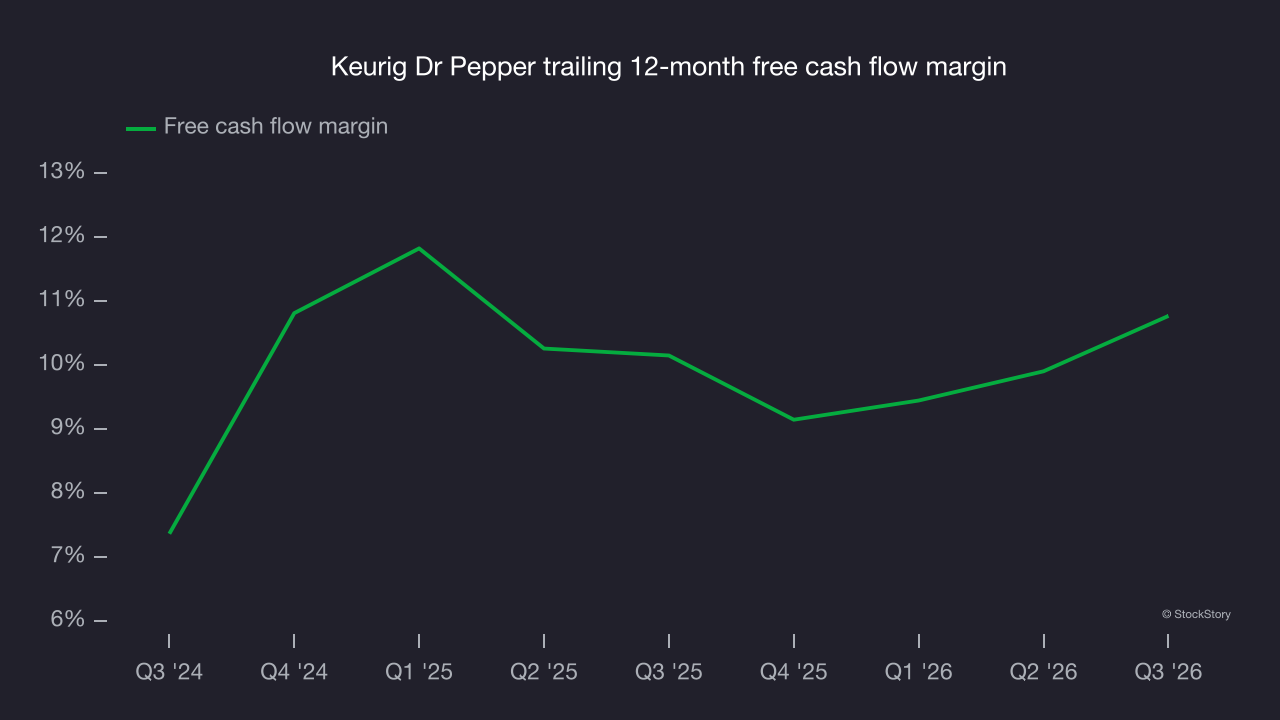
Keurig Dr Pepper generated $1.03 billion in free cash flow in Q3, equivalent to a 14% margin. This was a positive result, as its margin was 1.7 percentage points higher than in the same quarter last year. Its cash profitability was also above its two-year level.
Key takeaways from Keurig Dr Pepper’s Q3 results
Keurig Dr Pepper’s EPS beat analysts’ consensus estimates, but its full-year revenue guidance fell slightly short, leaving a mixed picture for the quarter. Investors were likely hoping for more: shares fell 4.3% to $35.38 immediately after the results.
Considering Keurig Dr Pepper at its current price? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to buy. Read more in our full research report here (it’s free).