Heating and cooling solutions company AAON (NASDAQ: AAON) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 84.1% year on year to $707.4 million. Its non-GAAP profit of $0.83 per share was 43.5% above analysts’ consensus estimates.
For more on AAON, read our free full research report.
AAON (AAON) Q3 2026 highlights:
- Revenue $707.4 million vs consensus estimates from S&P of $602.2 million (84.1% year-on-year growth, 17.5% beat)
- Adjusted EPS $0.83 vs consensus estimates from S&P of $0.58 (43.5% beat)
- Adjusted EBITDA $127.2 million vs analysts' consensus estimates of $92.66 million (18% margin, 37.3% beat)
- Operating margin 14.1%, up from 11.4% in the same quarter last year
- Free cash flow $51.11 million, up from -$33.3 million in the same quarter last year
- Backlog $1.85 billion at quarter end, up 40.5% year on year
- Market capitalization $4.72 billion
"We are encouraged by the sequential improvement in gross margin during the third quarter. Higher production volumes, better utilization, pricing actions, sourcing initiatives, and continued operational discipline are beginning to show more clearly in our results. While additional work remains, we expect continued progress in the fourth quarter and remain confident in the long-term earnings power and cash generation potential of the business."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, AAON grew its revenue at a strong 34.4% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
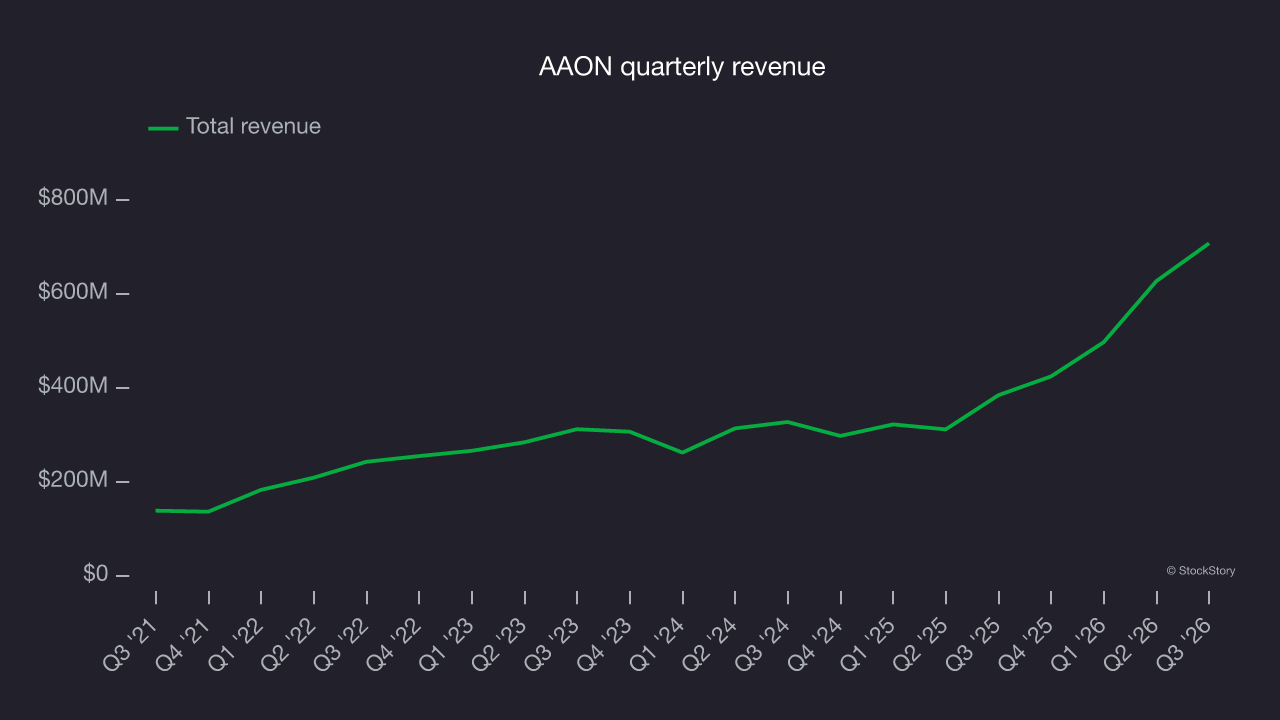
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. AAON’s annualized revenue growth of 36.6% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 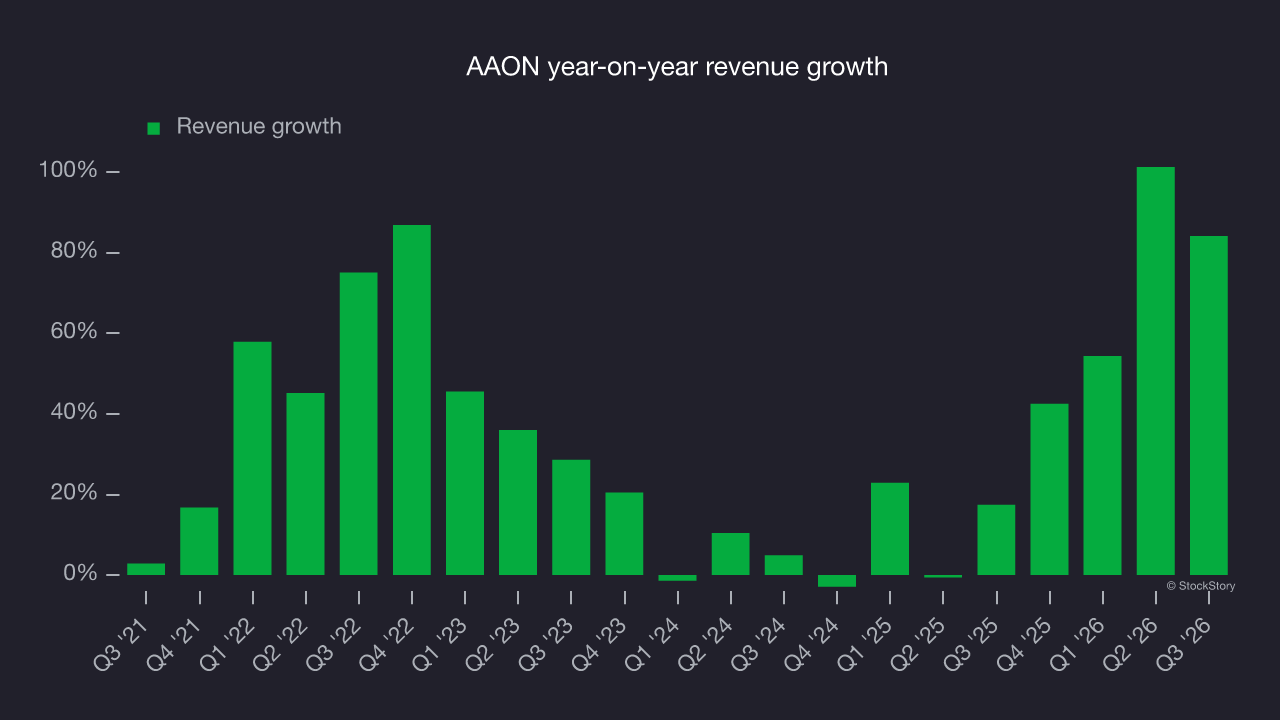
The company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, offers a closer look at its revenue dynamics. AAON’s backlog reached $1.85 billion in the latest quarter and averaged 84.7% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for AAON’s products and services but raises concerns about capacity constraints. 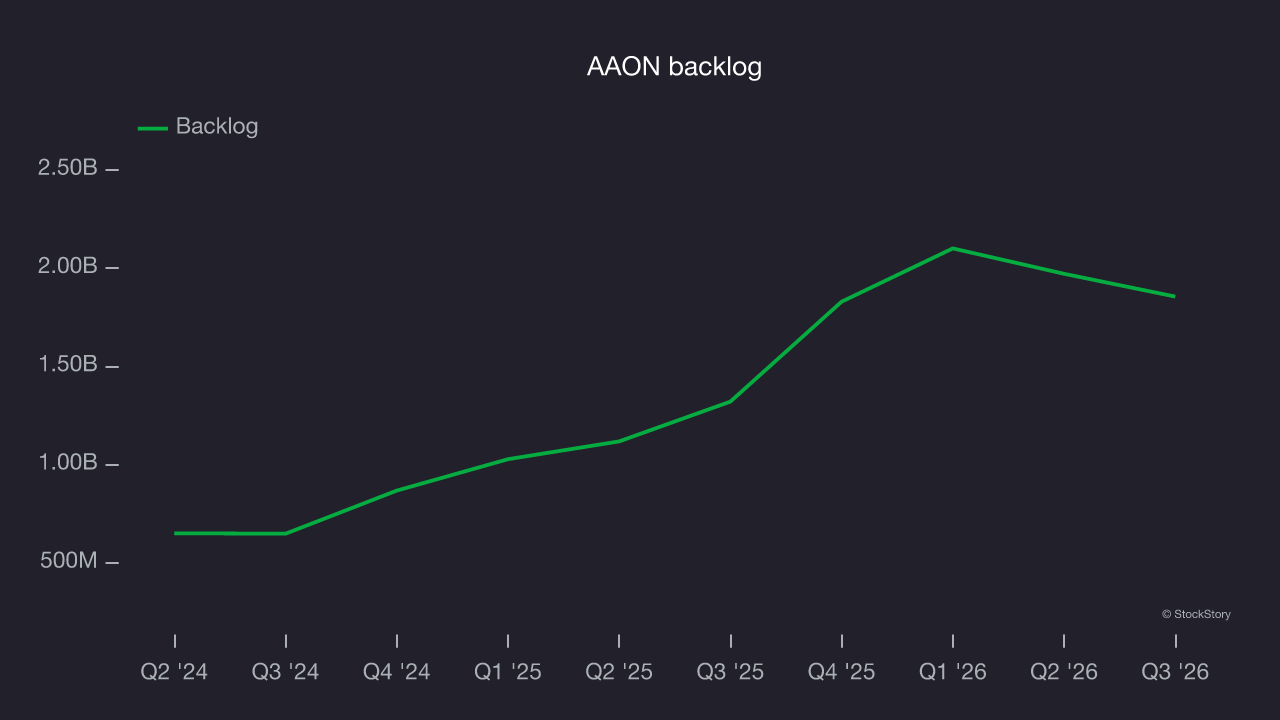
This quarter, AAON reported strong year-on-year revenue growth of 84.1%, and its $707.4 million of revenue beat Wall Street’s consensus estimates by 17.5%.
Looking ahead, sell-side analysts expect revenue to grow 15.7% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is healthy and indicates the market expects success for its products and services.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
AAON’s operating margin was broadly unchanged over the last five years. Its costs have broadly tracked its revenue, leaving its long-term profitability largely unchanged. Its trailing 12-month operating margin was 12%.
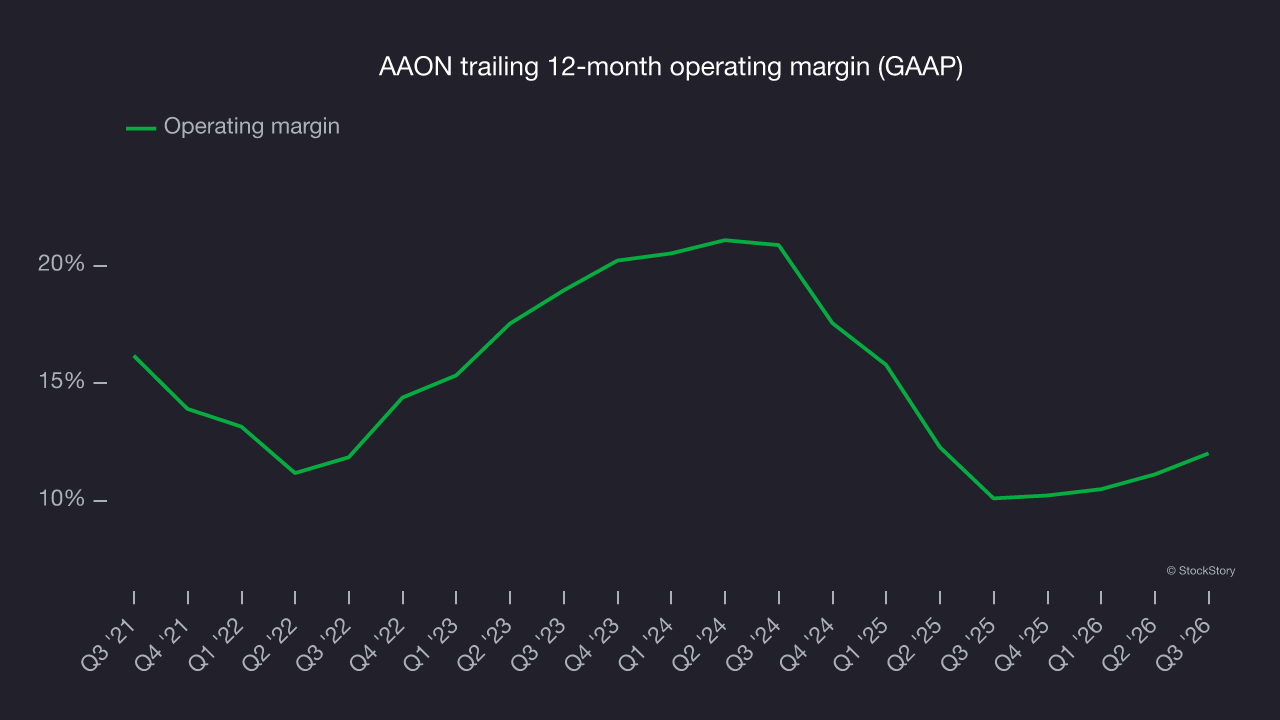
This quarter, AAON generated an operating profit margin of 14.1%, up 2.7 percentage points year on year. The increase was a positive sign and, with gross margin declining, suggests greater efficiency as operating expenses such as marketing, R&D and administrative overhead grew more slowly than revenue.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
AAON’s EPS grew at a strong 22.1% compounded annual growth rate over the last five years. However, this performance trailed its 34.4% annualized revenue growth, indicating the company became less profitable on a per-share basis as it expanded.
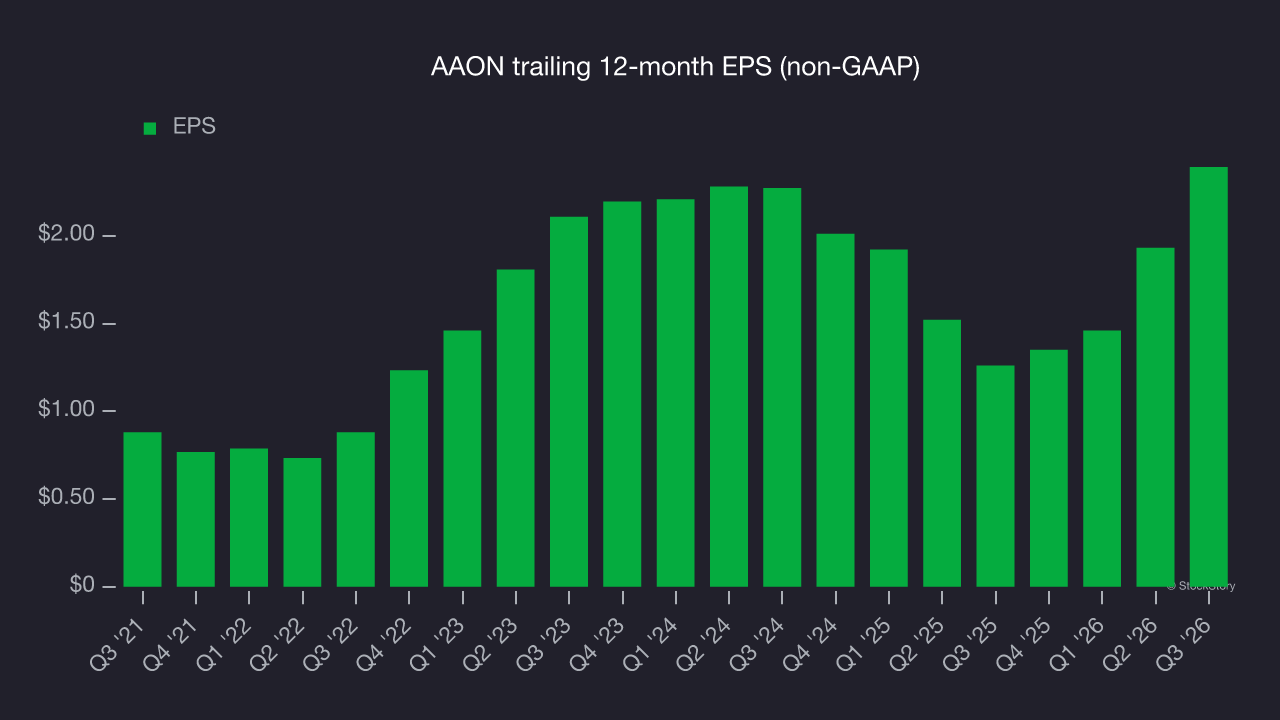
Diving into the nuances of AAON’s earnings can give us a better understanding of its performance. A five-year view shows AAON has diluted its shareholders, growing its share count by 4%. This has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 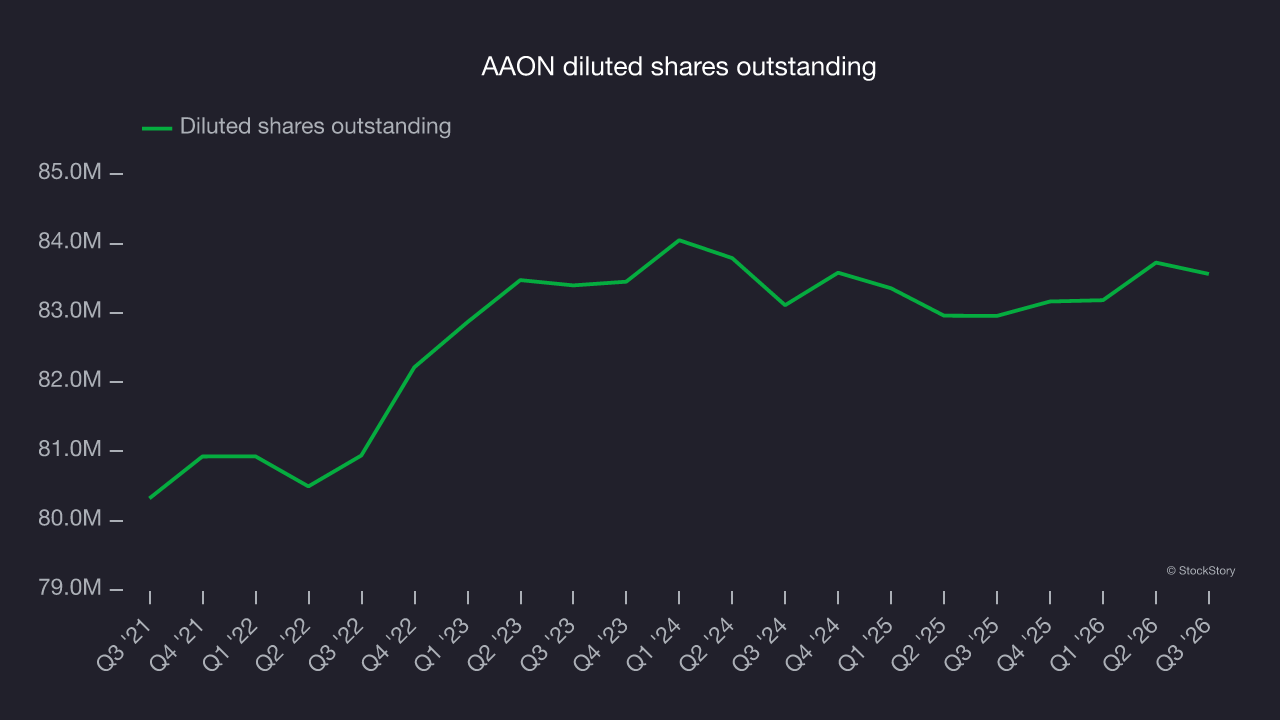
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For AAON, its two-year annual EPS growth of 2.6% was lower than its five-year trend. This was underwhelming, but the company performed well on other measures of financial health.
In Q3, AAON reported adjusted EPS of $0.83, up from $0.37 in the same quarter last year. This result easily beat analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects AAON’s full-year EPS to grow 34.8% from $2.39 to $3.22, according to S&P.
Key takeaways from AAON’s Q3 results
AAON delivered a strong Q3, with EBITDA topping Wall Street’s consensus estimates by a wide margin and EPS also beating analysts’ consensus expectations. Shares soared 14.6% to $72.00 immediately after the results.
AAON reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on AAON, read our full research report here (it’s free).