CECO Environmental trades at $73.39 and has moved in lockstep with the market. Its shares have returned 18.2% over the last six months while the S&P 500 has gained 16.9%.
Is there a buying opportunity in CECO Environmental, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is CECO Environmental Not Exciting?
We’re passing on CECO Environmental for now. Here are three reasons why CECO doesn’t excite us, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
With $903.2 million in revenue over the past 12 months, CECO Environmental is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels. On the bright side, it can grow faster because it has more room to expand.
2. Shrinking Adjusted Operating Margin
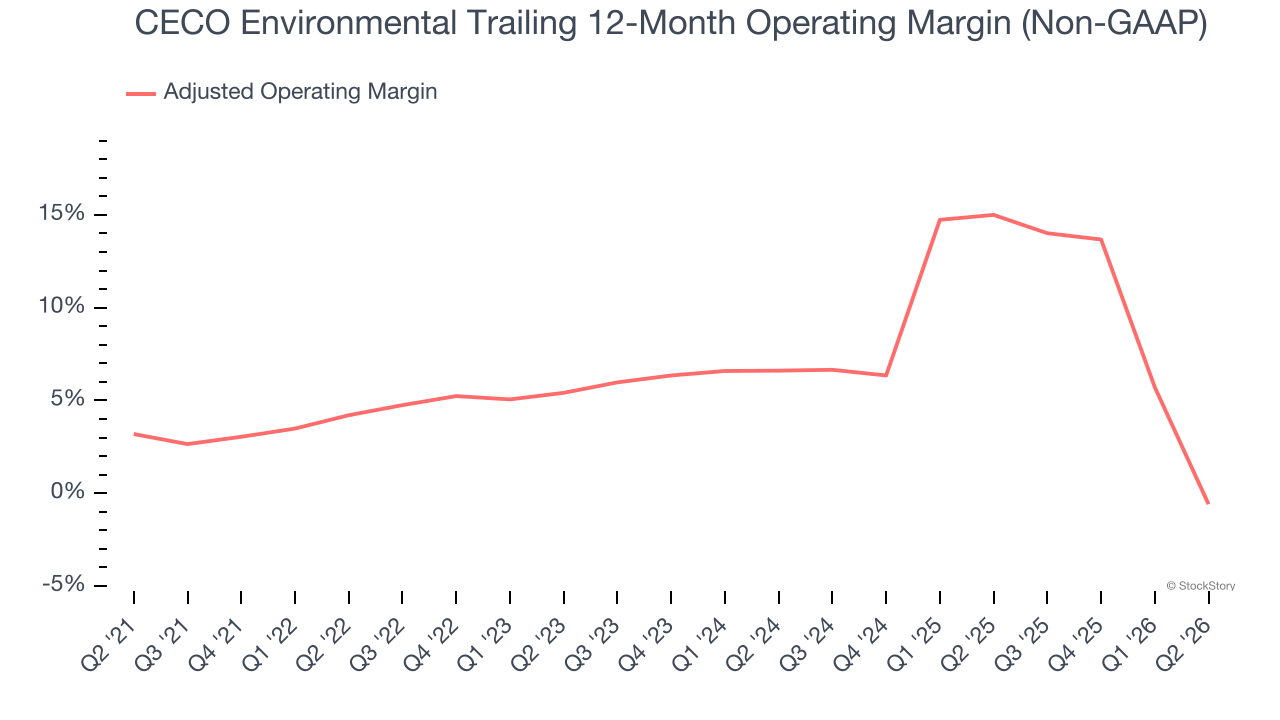
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Analyzing the trend in its profitability, CECO Environmental’s adjusted operating margin decreased by 4.8 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. CECO Environmental’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its adjusted operating margin for the trailing 12 months was breakeven.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
CECO Environmental’s $727.7 million of debt exceeds the $63.85 million of cash on its balance sheet. Furthermore, its 6× net-debt-to-EBITDA ratio (based on its EBITDA of $113.6 million over the last 12 months) shows the company is overleveraged.
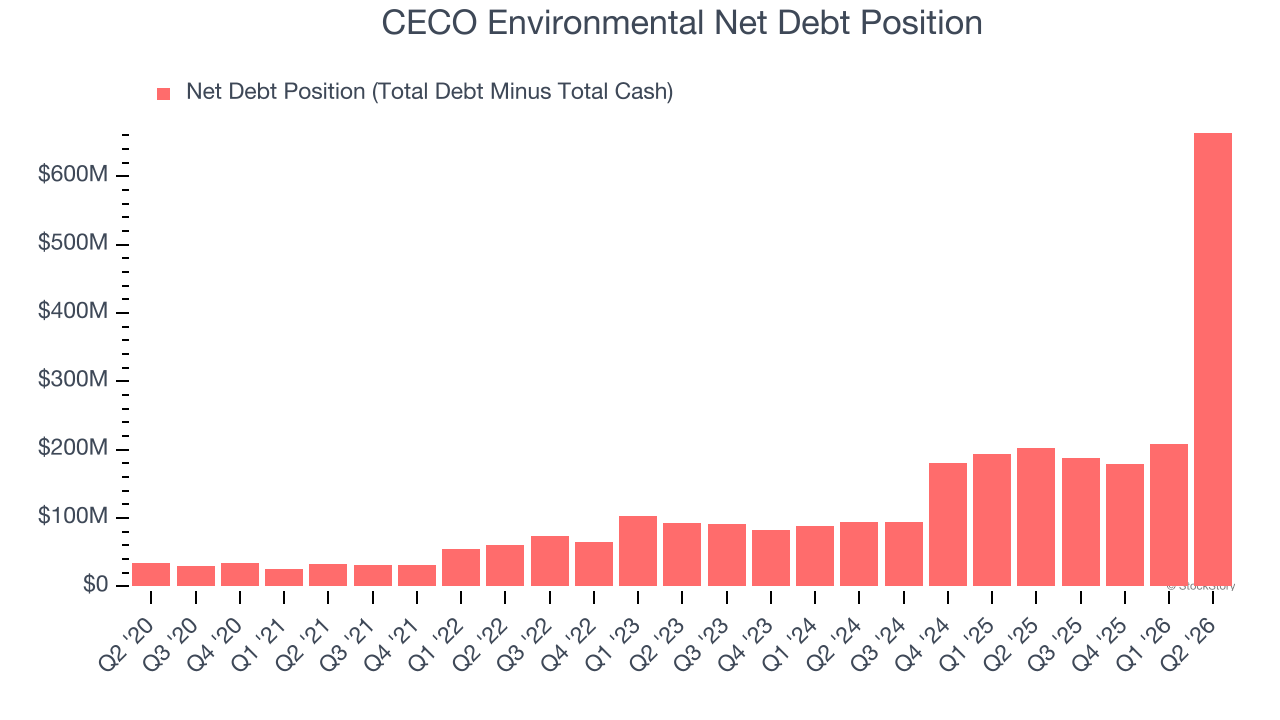
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. CECO Environmental could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope CECO Environmental can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
CECO Environmental isn’t a terrible business, but it doesn’t pass our quality test. That said, the stock currently trades at 28.3× forward P/E (or $73.39 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re fairly confident there are better stocks to buy right now. Let us point you toward a top digital advertising platform riding the creator economy.
Stocks We Like More Than CECO Environmental
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.