
Shareholders of Lemonade would probably like to forget the past six months even happened. The stock dropped 24.2% and now trades at $46.60. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in Lemonade, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Lemonade Not Exciting?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons why LMND doesn’t excite us, plus one stock we’d rather own.
1. EPS Barely Improving
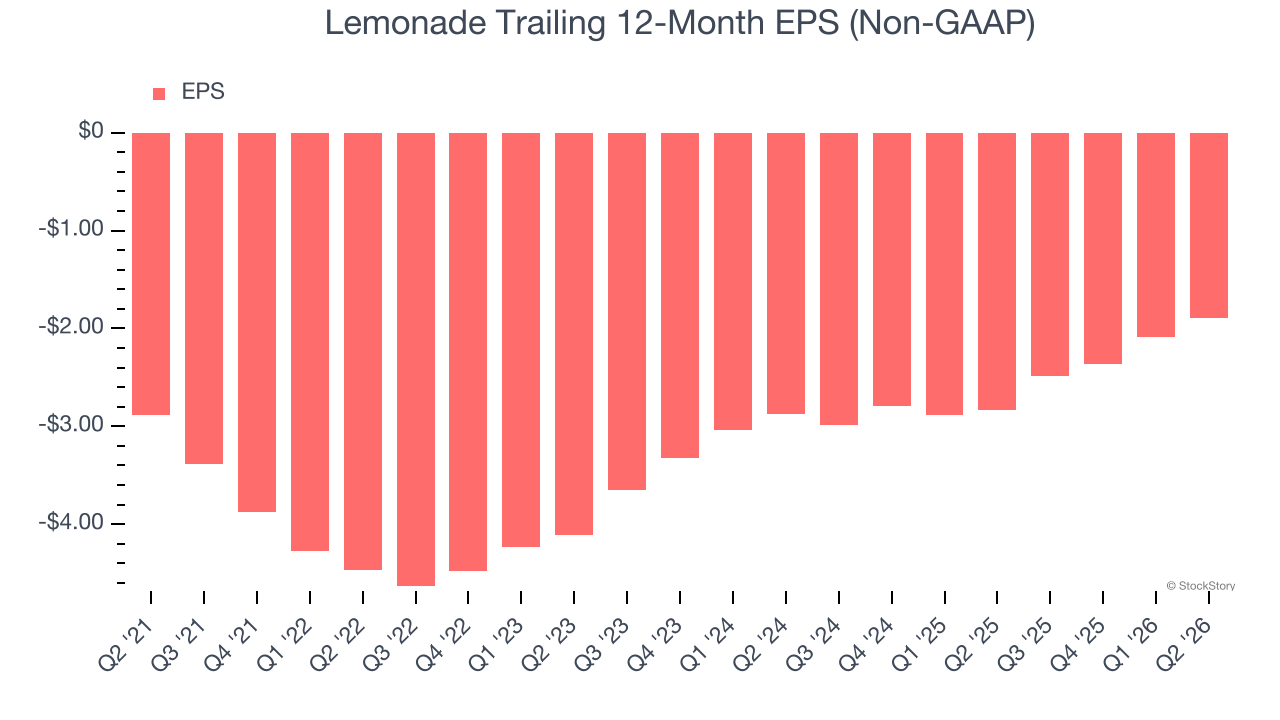
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Although Lemonade’s full-year earnings are still negative, it reduced its losses and improved its EPS by 8% annually over the last five years. The next few quarters will be critical for assessing its long-term profitability.
2. Declining BVPS Reflects Erosion of Asset Value
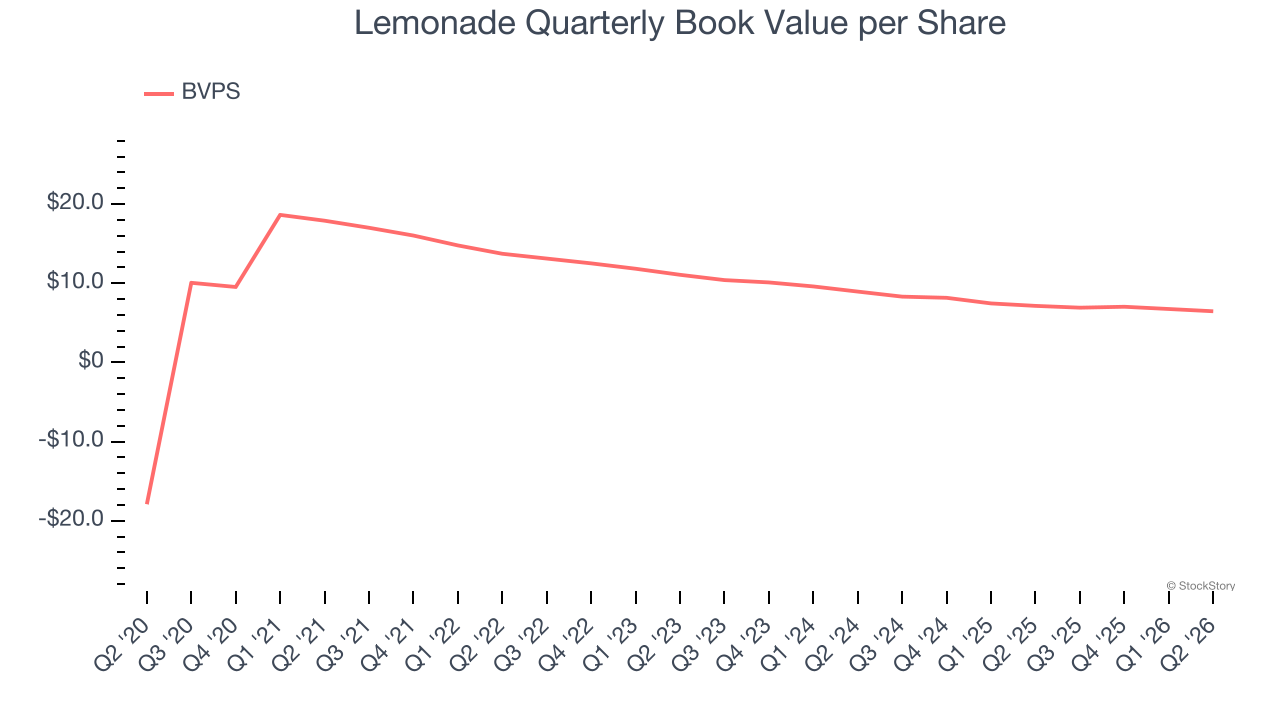
In the insurance industry, book value per share (BVPS) provides a clear picture of shareholder value, as it represents the total equity backing a company’s insurance operations and growth initiatives.
To the detriment of investors, Lemonade’s BVPS declined at a 15% annual clip over the last two years.
3. Previous Growth Initiatives Have Lost Money
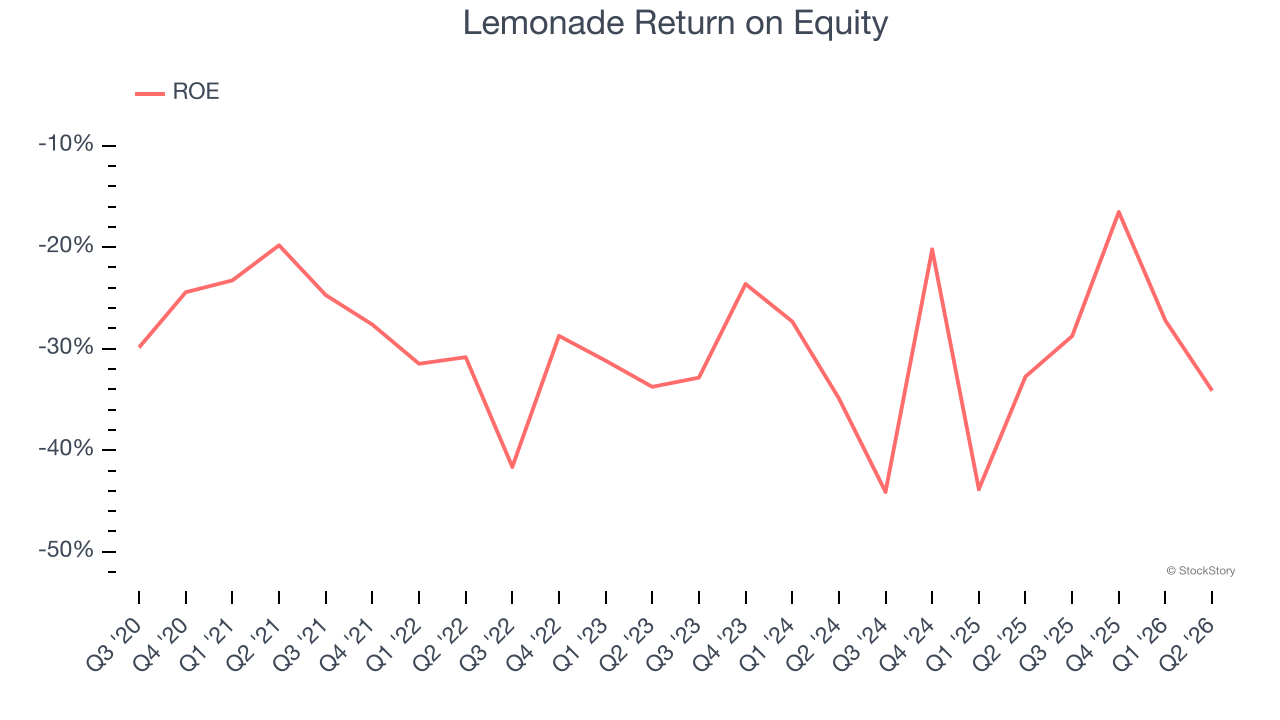
Return on Equity, or ROE, ties everything together and is a vital metric. It tells us how much profit the insurer generates for each dollar of shareholder equity entrusted to management. Over a long period, insurers with higher ROEs tend to compound shareholder wealth faster through retained earnings, buybacks, and dividends.
Over the last five years, Lemonade has averaged an ROE of negative 30.8%, a bad result not only in absolute terms but also relative to the majority of insurers putting up 20%+. It also shows that Lemonade has little to no competitive moat.
Final Judgment
Lemonade isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 7.2× forward P/B (or $46.60 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re fairly confident there are better investments elsewhere. We’d recommend looking at the Amazon and PayPal of Latin America.
Stocks We Like More Than Lemonade
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.