
Neogen’s 25.9% return over the past six months has outpaced the S&P 500 by 16.8%, and its stock price has climbed to $11.78 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Neogen, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why do we think Neogen will underperform?
We’re glad investors have benefited from the price increase, but we don’t have much confidence in Neogen. Here are three reasons we avoid NEOG, plus one stock we’d rather own.
1. Revenue tumbling downwards
We at StockStory place the most emphasis on long-term growth, but within healthcare, a stretched historical view may miss recent innovations or disruptive industry trends. Neogen’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 1.6% over the last two years. 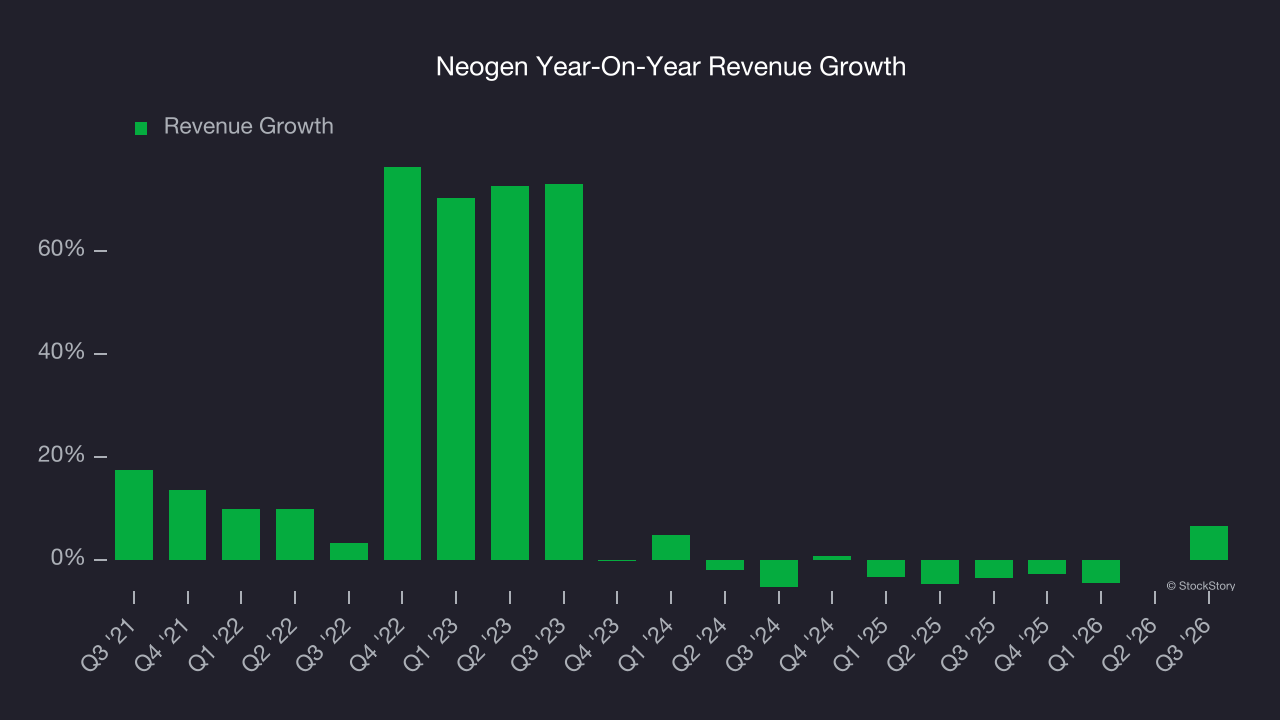
2. New investments fail to bear fruit as ROIC declines
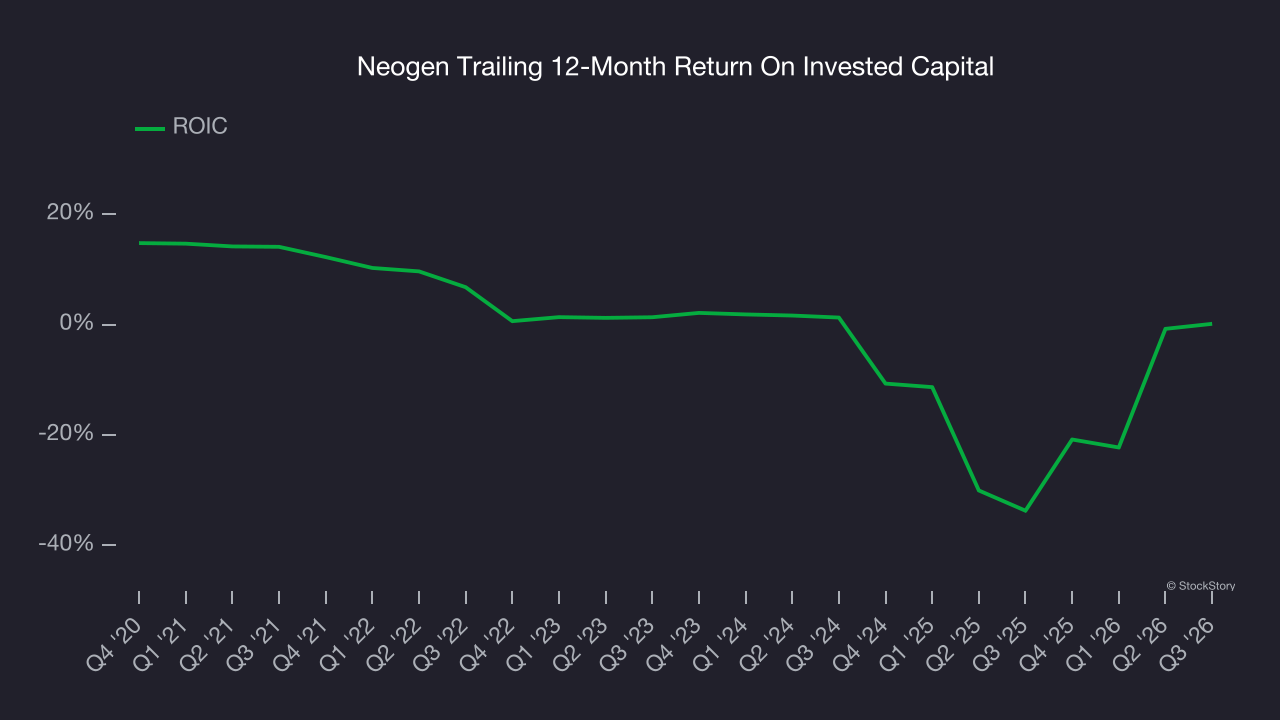
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Neogen’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
3. High debt levels increase risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Neogen’s $774.2 million of debt exceeds the $172 million of cash on its balance sheet. Furthermore, its 6× net-debt-to-EBITDA ratio (based on its EBITDA of $108.9 million over the last 12 months) shows the company is overleveraged.
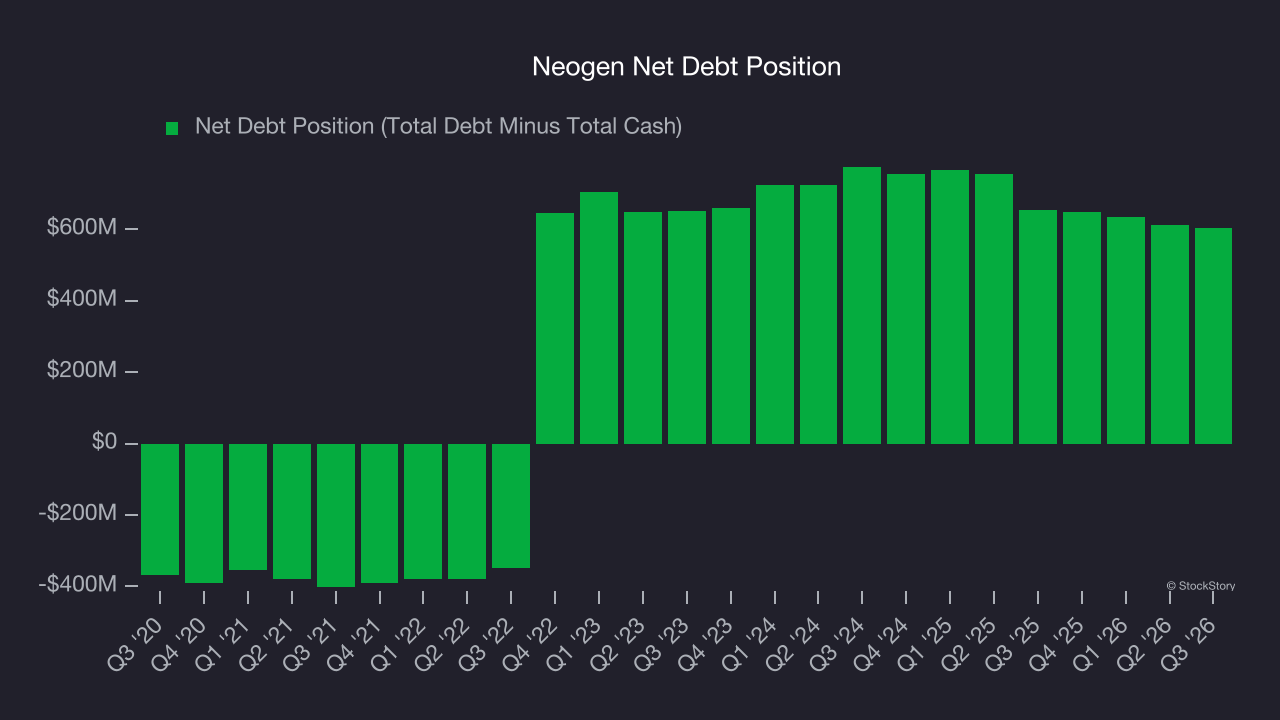
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Neogen could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Neogen can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final judgment
Neogen doesn’t pass our quality test. With its shares beating the market recently, the stock trades at 34.7× forward P/E (or $11.78 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at a top digital advertising platform riding the creator economy.
Stocks we like more than Neogen
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.