Investment banking firm Piper Sandler (NYSE: PIPR) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 2.7% year on year to $443 million. Its non-GAAP profit of $0.87 per share was 6.5% below analysts’ consensus estimates.
For more on Piper Sandler, read our full research report, available free.
Piper Sandler (PIPR) Q3 2026 highlights:
- Revenue $443 million vs S&P analysts’ consensus estimates of $464.9 million (8% year-on-year decline, 4.7% miss)
- Pre-tax profit $66.63 million (15% margin)
- Adjusted EPS $0.87 vs S&P analysts’ consensus estimates of $0.93 (6.5% miss)
- Market capitalization $4.62 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Piper Sandler’s revenue grew at a sluggish 3.1% compounded annual growth rate over the last five years, falling short of the financials sector standard.
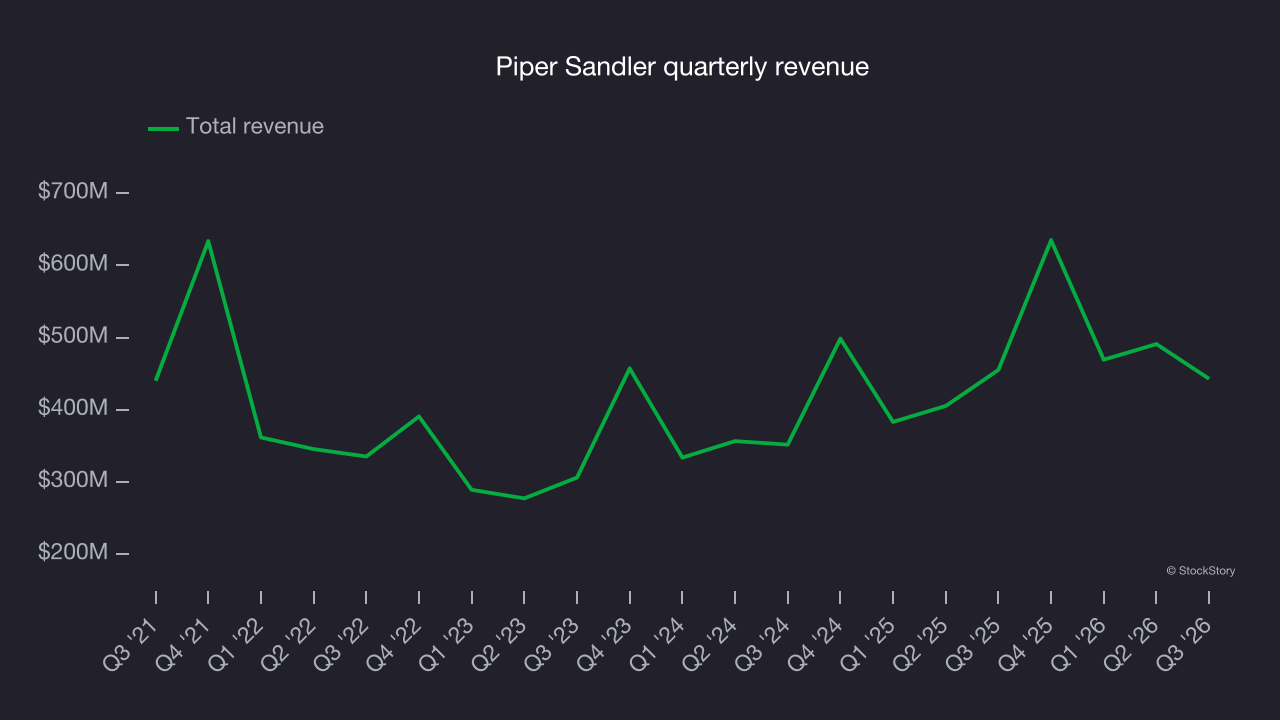
This quarter, Piper Sandler missed Wall Street’s consensus estimates and reported an uninspiring 8% year-on-year revenue decline, generating $443 million of revenue.
Key takeaways from Piper Sandler’s Q3 results
Piper Sandler’s revenue and EPS both fell short of Wall Street’s consensus estimates, leaving few positives in a weaker quarter. Shares tumbled 5.6% to $64.87 immediately after the results.
Piper Sandler’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though. To assess whether the stock is a buy at the current price, the latest quarter matters, but not as much as longer-term business quality and valuation. For more on Piper Sandler, read our full research report here (it’s free).