

Security systems manufacturer Napco (NASDAQ: NSSC) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027) as revenue rose just 1.7% year on year to $49.98 million. Its GAAP profit of $0.36 per share was 3.7% below analysts’ consensus estimates.
For more on Napco, read our free full research report.
Napco (NSSC) Q3 CY2026 highlights:
- Revenue $49.98 million vs S&P analysts’ consensus estimates of $52.07 million (1.7% year-on-year growth, 4% miss)
- EPS (GAAP) $0.36 vs analysts’ consensus estimates of $0.37 (3.7% miss)
- Adjusted EBITDA $15.51 million vs analysts’ consensus estimates of $16.04 million (31% margin, 3.3% miss)
- Operating margin 28.2%, in line with the same quarter last year
- Free cash flow margin 4.6%, down from 23.3% in the same quarter last year
- Market capitalization $1.41 billion
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $203.1 million in revenue over the past 12 months, Napco is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels. On the positive side, it can grow faster because it has more room to expand.
Napco’s revenue grew at an impressive 10.8% compounded annual growth rate over the last five years, showing its demand was higher than that of many business services companies.
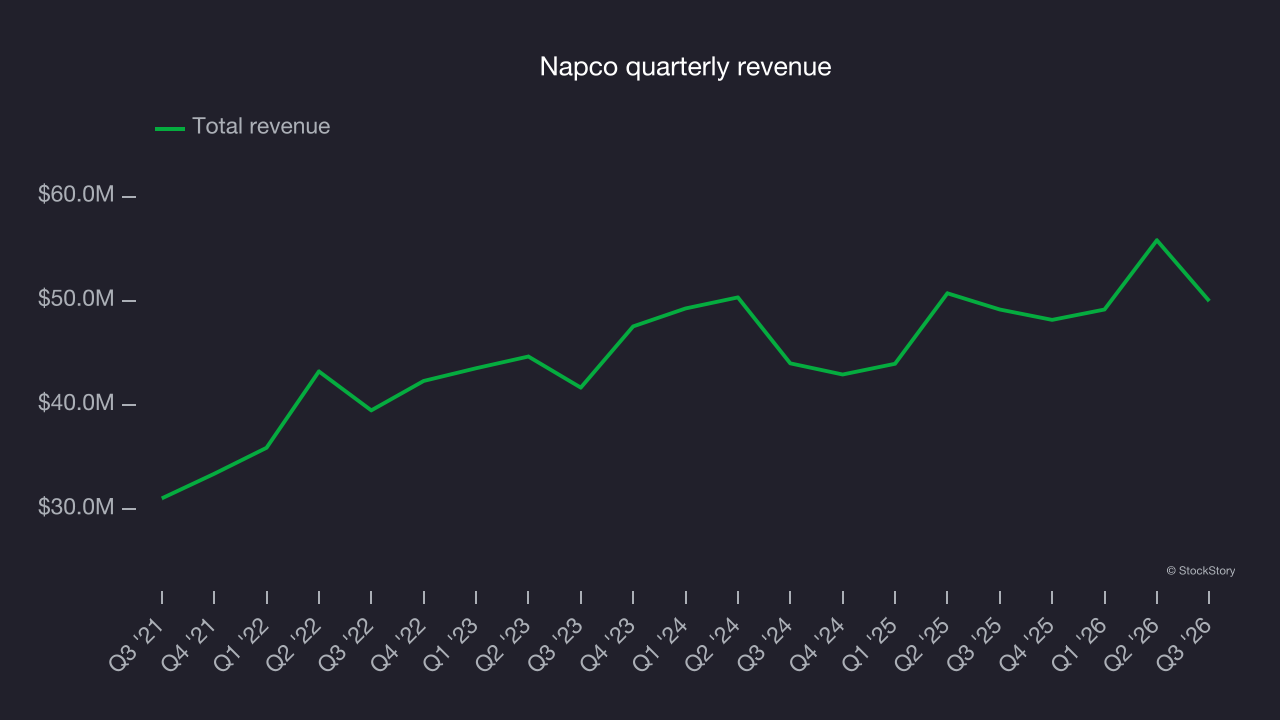
Long-term growth matters the most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Napco’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 3.1% over the last two years was well below its five-year trend. 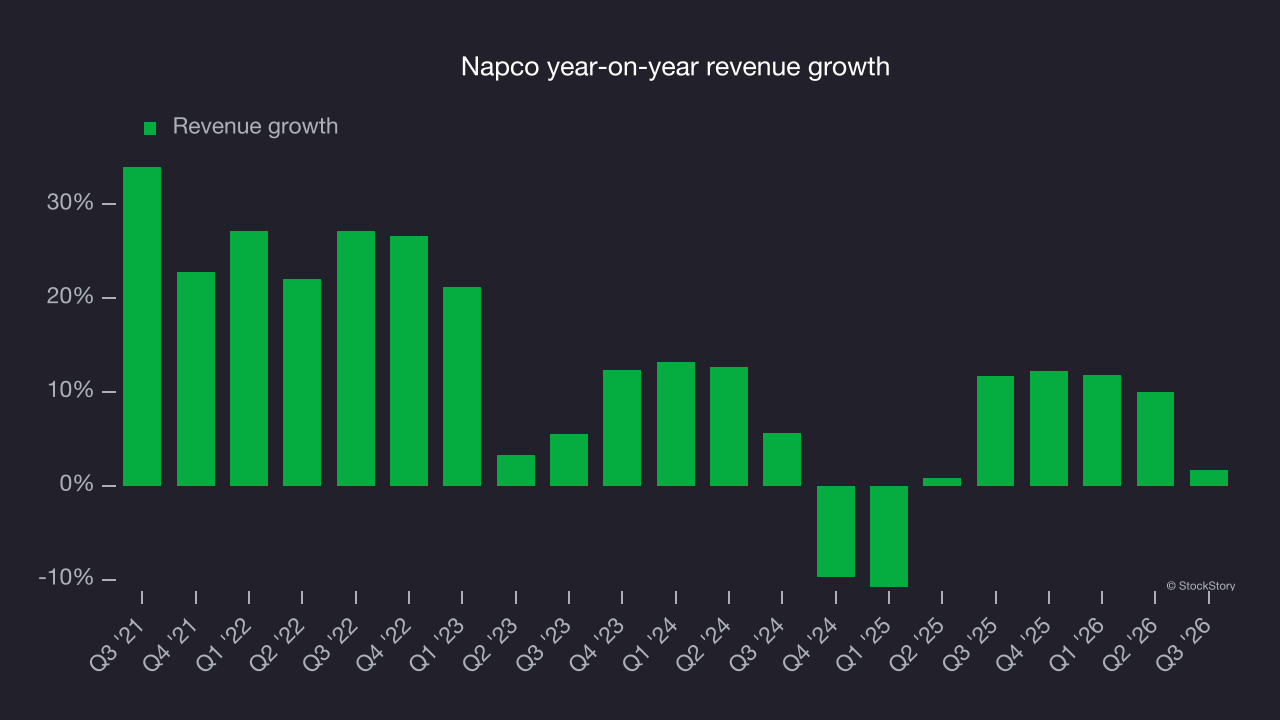
This quarter, Napco’s revenue grew by 1.7% year on year to $49.98 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 9.9% over the next 12 months, according to S&P, an improvement versus the last two years. This is a strong projection and suggests its newer products and services will fuel better revenue performance.
Adjusted operating margin
Napco has operated efficiently over the last five years. It demonstrated high profitability for a business services company, with an average adjusted operating margin of 25.4%.
Looking at the trend in its profitability, Napco’s adjusted operating margin rose by 17.1 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
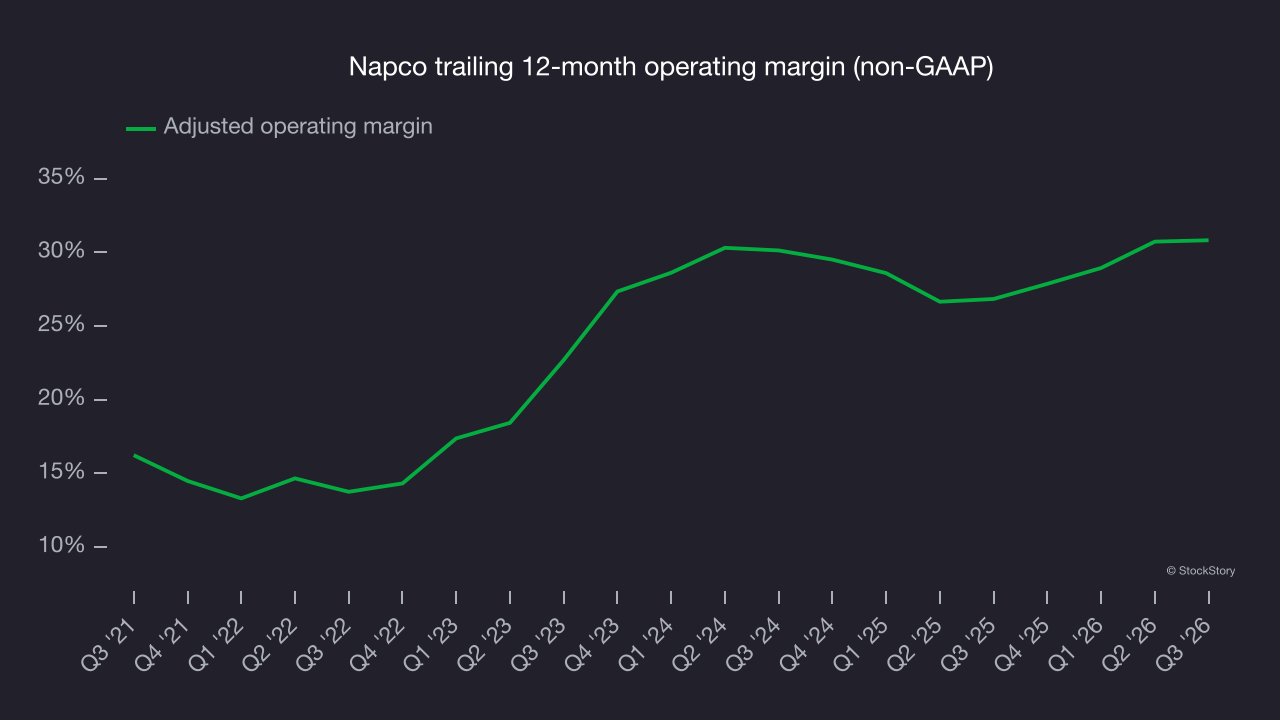
In Q3, Napco generated an adjusted operating margin of 28.8%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Napco’s EPS grew at a 17.5% compounded annual growth rate over the last five years, higher than its 10.8% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
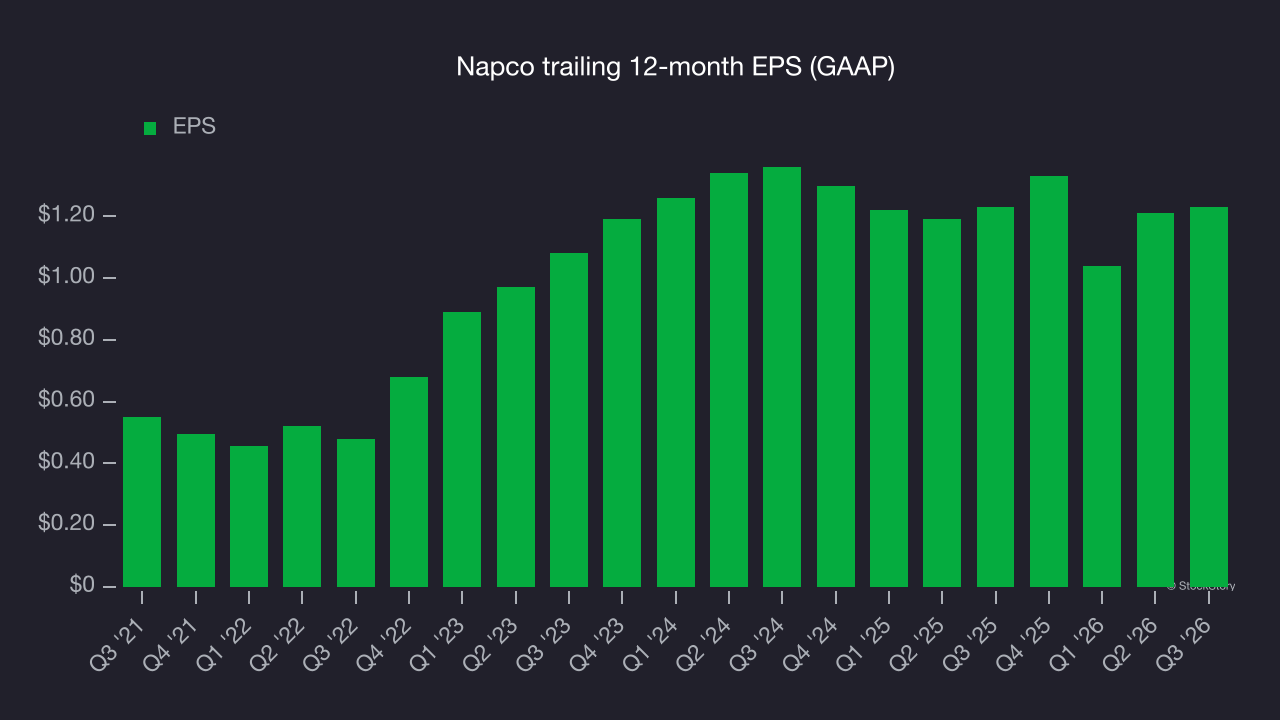
A closer look at Napco’s earnings helps explain the drivers of its performance. As mentioned earlier, Napco’s adjusted operating margin was flat this quarter but expanded by 17.1 percentage points over the last five years. Its share count also shrank by 2.6%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 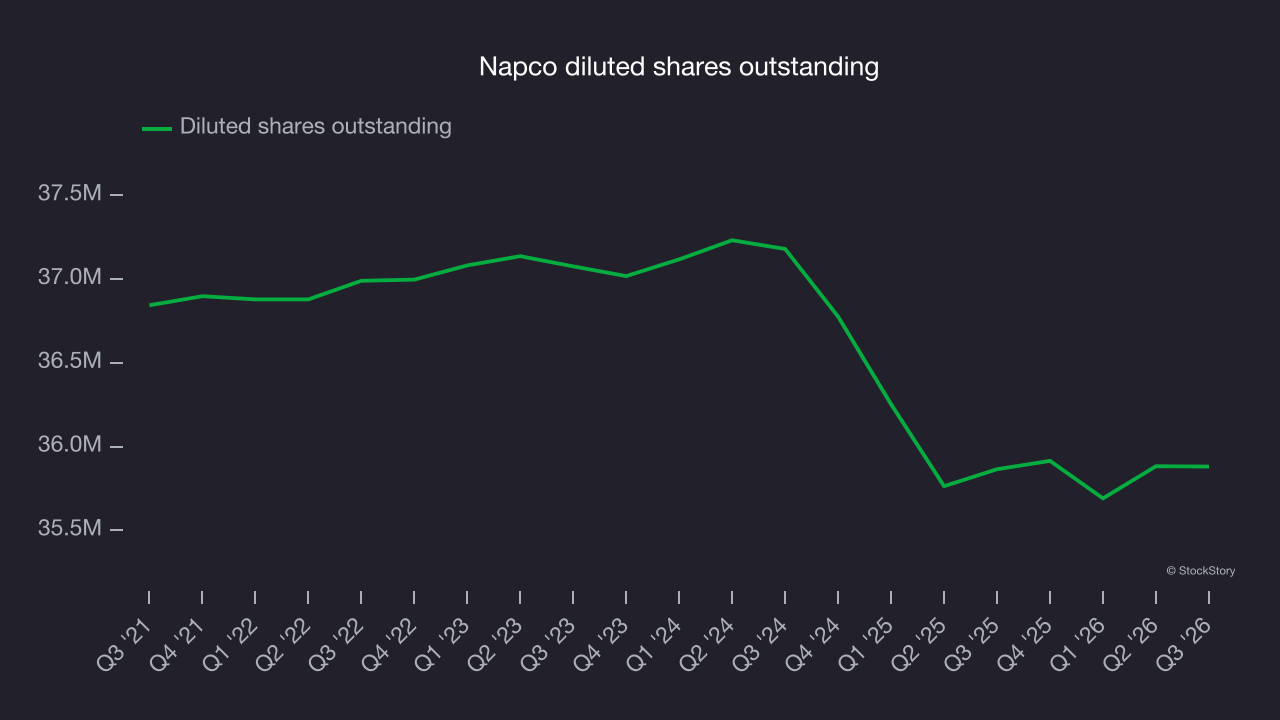
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
Napco’s two-year annual EPS declines of 4.9% mark a reversal from its seemingly healthy five-year trend. These shorter-term results weren’t ideal, but its success on other measures of financial health suggests a return to earnings growth is possible.
In Q3, Napco reported EPS of $0.36, up from $0.34 in the same quarter last year. Despite growing year on year, this result missed analysts’ consensus estimates, but long-term EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects Napco’s full-year EPS to grow 35.6% from $1.23 to $1.67, according to S&P.
Key takeaways from Napco’s Q3 results
Napco’s revenue and EPS both fell short of Wall Street’s consensus estimates, leaving few positives in a quarter that could have been better. Shares plunged 15% to $33.43 immediately after the results.
Napco’s earnings report left more to be desired. Assessing whether this quarter has created an investment opportunity requires considering its valuation, business quality and latest results. For more on Napco, read our full research report here (it’s free).




