

Electric vehicle charging company EVgo (NASDAQ: EVGO) fell short of the market’s revenue expectations in Q3 2026, with revenue flat year on year at $91.42 million. The company’s full-year revenue guidance of $387.5 million at the midpoint came in 4.9% below analysts’ consensus estimates. Its GAAP loss of $0.14 per share was 14% below analysts’ consensus estimates.
For more on EVgo, read our free full research report.
EVgo (EVGO) Q3 2026 highlights:
- Revenue $91.42 million vs. S&P consensus estimates of $93.9 million (flat year on year, 2.6% miss)
- EPS (GAAP) -$0.14 vs. analysts’ consensus estimates of -$0.12 (14% miss)
- Adjusted EBITDA -$3.53 million (-3.9% margin, 29% year-on-year growth)
- Revenue guidance The company dropped its revenue guidance for the full year to $387.5 million at the midpoint from $415 million, a 6.6% decrease
- EBITDA guidance -$22.5 million at the midpoint for the full year, below analysts’ consensus estimates of -$19.98 million
- Adjusted EBITDA margin -3.9%, up from -5.4% in the same quarter last year
- Free cash flow -$50.07 million compared to -$48.86 million in the same quarter last year
- Market capitalization $259.3 million
LOS ANGELES, Nov. 09, 2026 (GLOBE NEWSWIRE) – EVgo Inc. (Nasdaq: EVGO) (“EVgo” or the “Company”), one of the nation’s largest providers of public fast charging infrastructure for electric vehicles (EVs), announced results for the third quarter ended September 30, 2026. Management will host a webcast on Nov. 9 at 9 a.m. ET / 6 a.m. PT to discuss EVgo’s results and other business highlights.
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. EVgo’s revenue grew at a strong 83.6% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
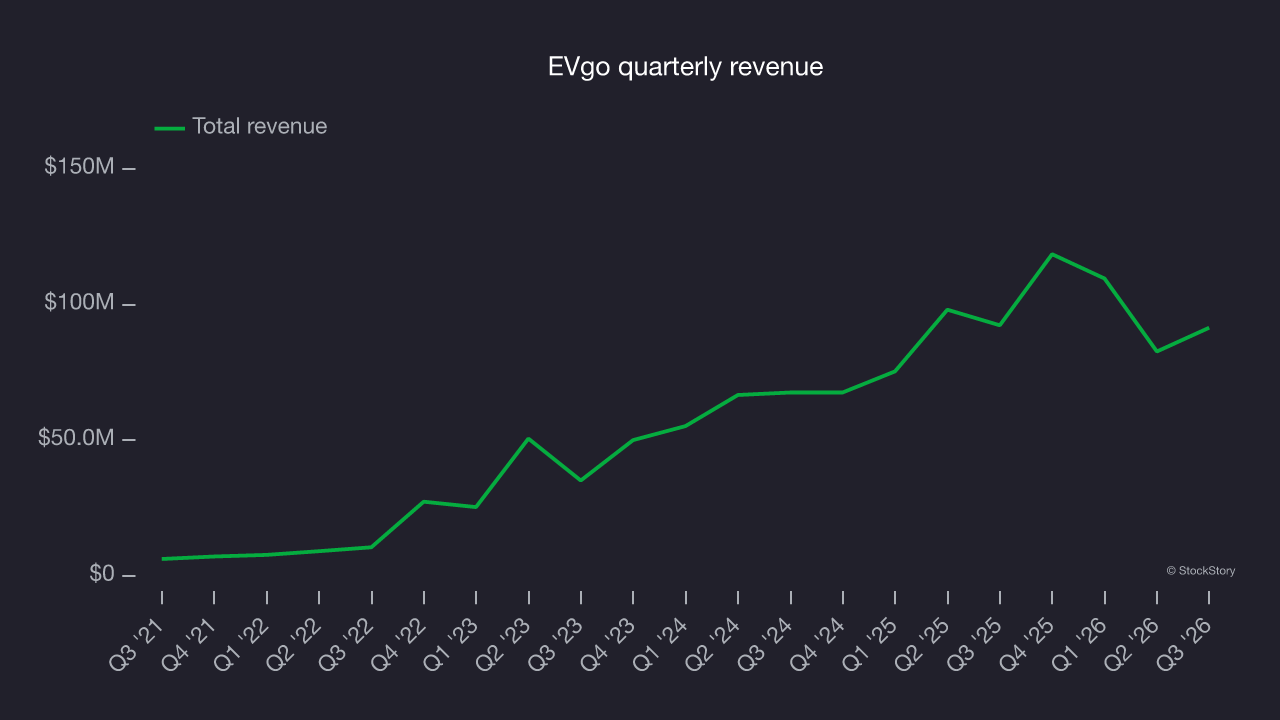
Long-term growth matters the most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. EVgo’s annualized revenue growth of 29.6% over the last two years is below its five-year trend, but the results still suggest healthy demand. 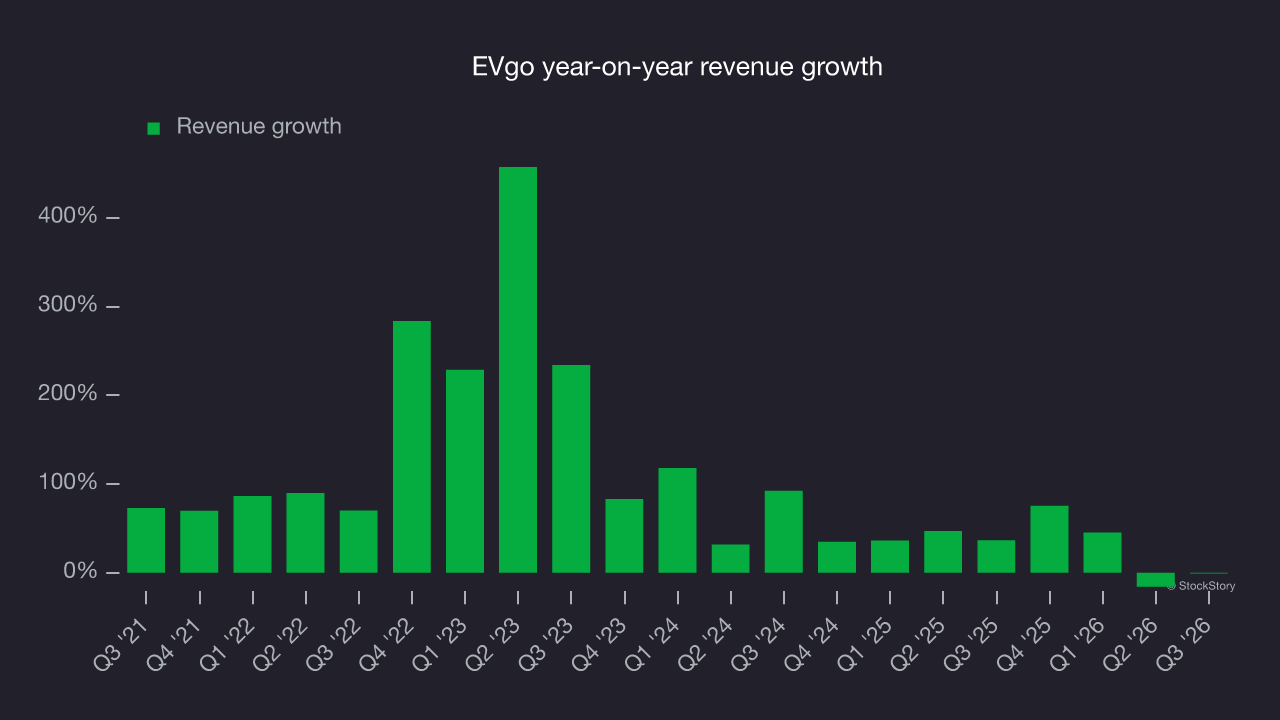
This quarter, EVgo’s $91.42 million of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 23.6% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is noteworthy and implies the market expects success for its products and services.
Operating margin
Over the last five years, EVgo’s operating margin rose by 364.3 percentage points. This improvement shows its costs declined relative to revenue. Its trailing 12-month operating margin was negative 34.4%.
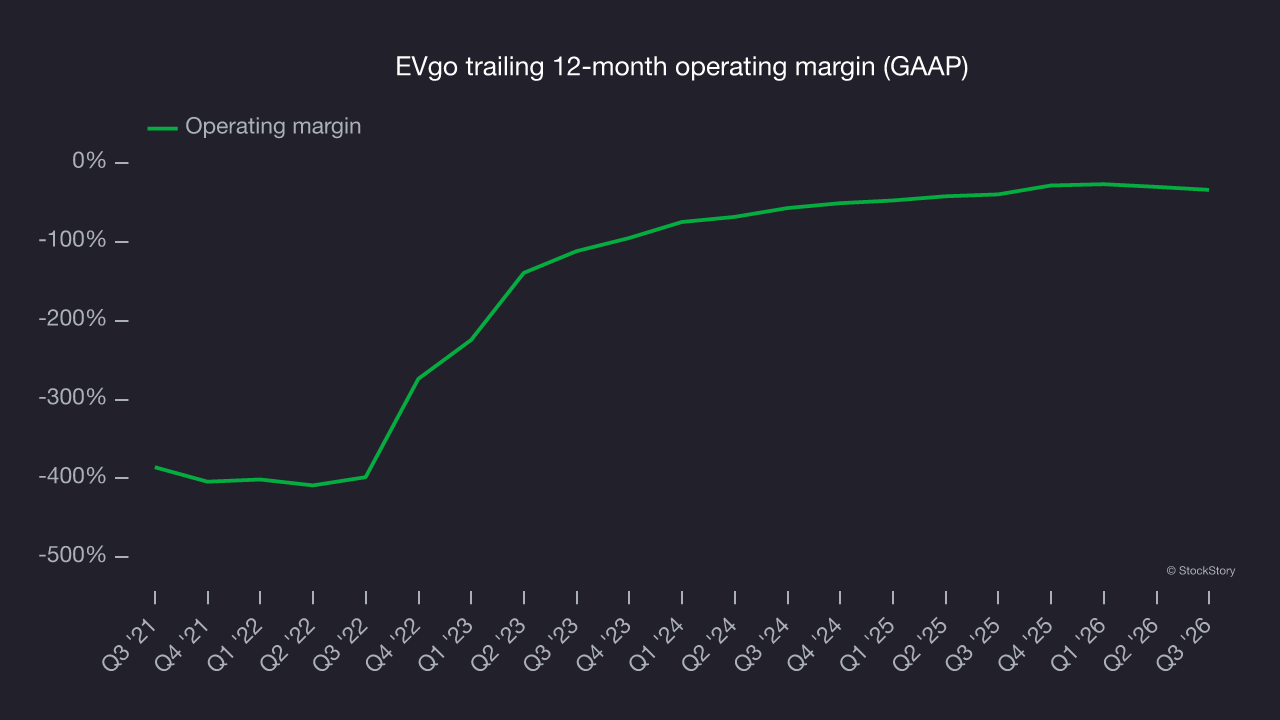
This quarter, EVgo generated a negative 54.1% operating margin.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
EVgo’s losses deepened over the last five years as its EPS dropped 29% annually. Diminishing earnings could imply changing secular trends and preferences.
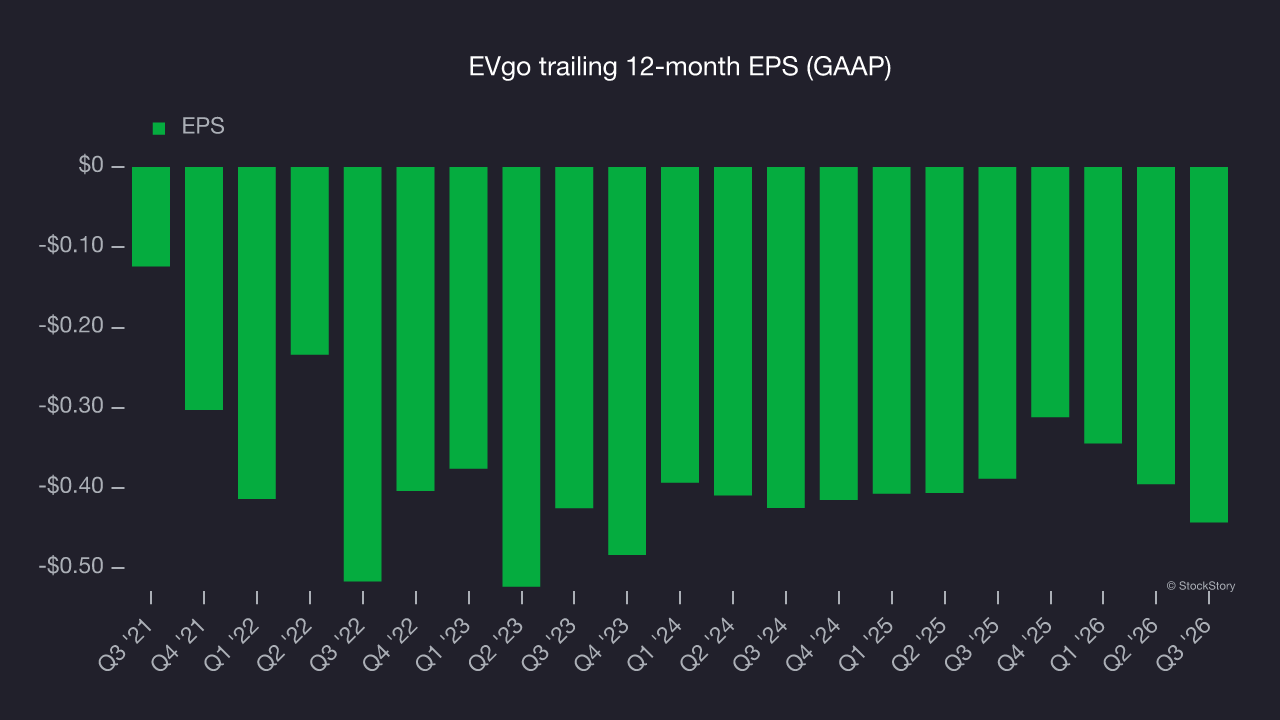
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For EVgo, its two-year annual EPS declines of 2.1% show it’s still underperforming. These results were poor, but its success on other measures of financial health suggests potential for future earnings growth.
In Q3, EVgo reported EPS of negative $0.14, down from negative $0.09 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects EVgo to perform poorly. Analysts forecast its full-year EPS will decline from negative $0.44 to negative $0.53, according to S&P.
Key takeaways from EVgo’s Q3 results
EVgo’s quarterly EBITDA came in well ahead of analysts’ consensus estimates, but its full-year outlook was softer: Both revenue and EBITDA guidance fell short of Wall Street’s consensus. Those guidance misses made this a softer quarter overall. Shares fell 2.7% to $1.78 immediately after the report.
EVgo underperformed this quarter. When deciding whether to invest in the stock, the latest results matter, but longer-term business quality and valuation matter more. Read our free full research report for more on EVgo.




