The past six months have been a windfall for Connection’s shareholders. The company’s stock price has jumped 49.2%, setting a new 52-week high of $87.13 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Connection, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Connection Not Exciting?
Despite the momentum, we’re sitting this one out for now. Here are three reasons you should be careful with CNXN, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
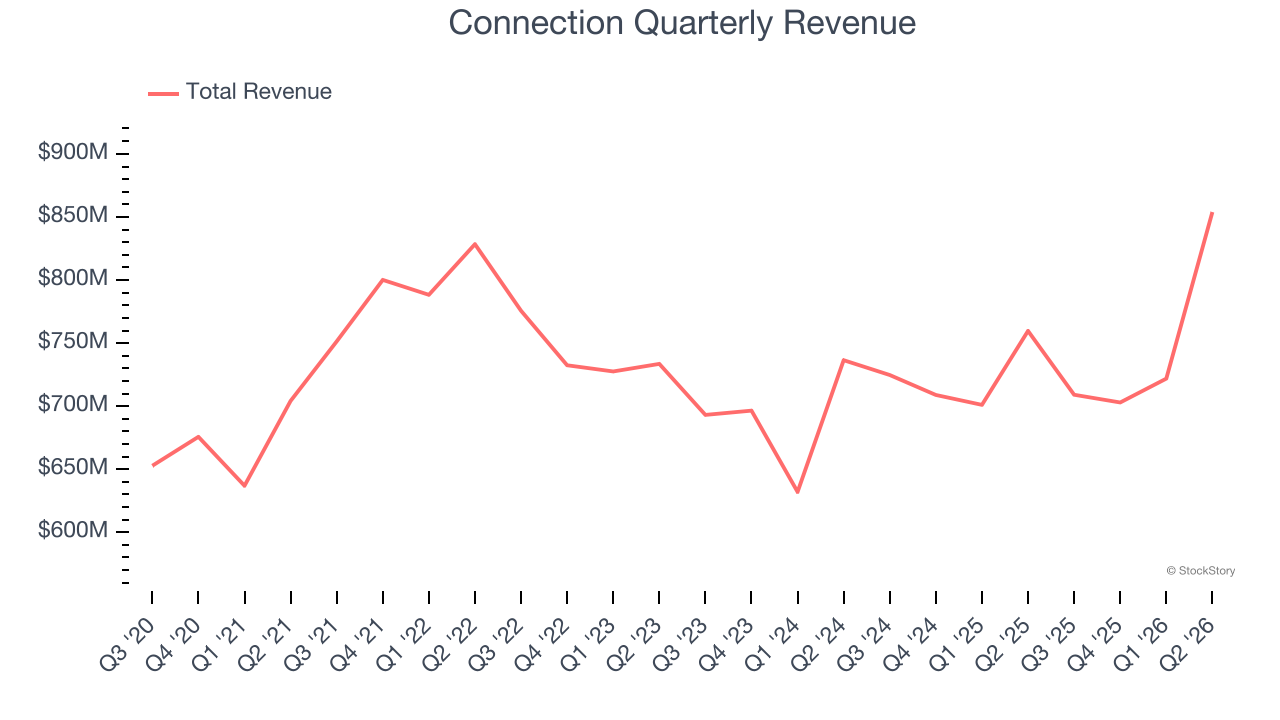
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Regrettably, Connection’s sales grew at a sluggish 2.3% compounded annual growth rate over the last five years. This fell short of our benchmarks.
2. Recent EPS Growth Below Our Standards
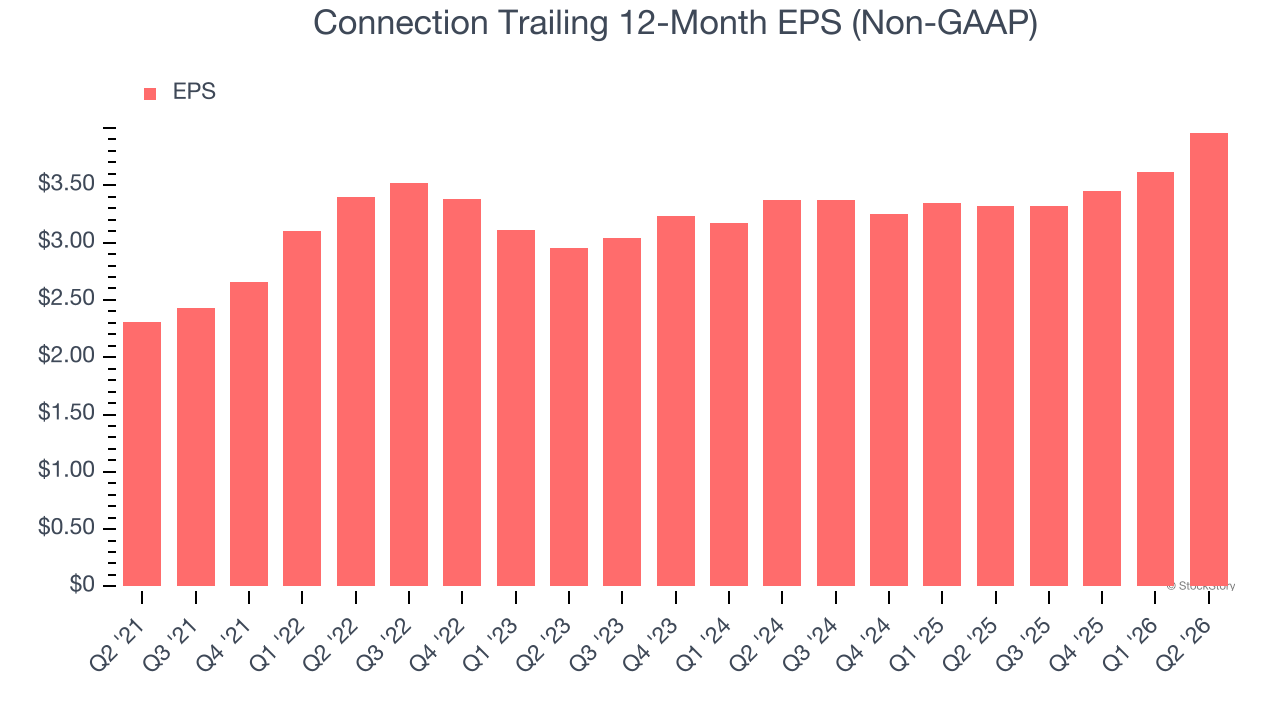
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
Connection’s EPS grew at an unimpressive 8.4% compounded annual growth rate over the last two years. On the bright side, this performance was higher than its 4.1% annualized revenue growth and tells us the company became more profitable on a per-share basis as it expanded.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
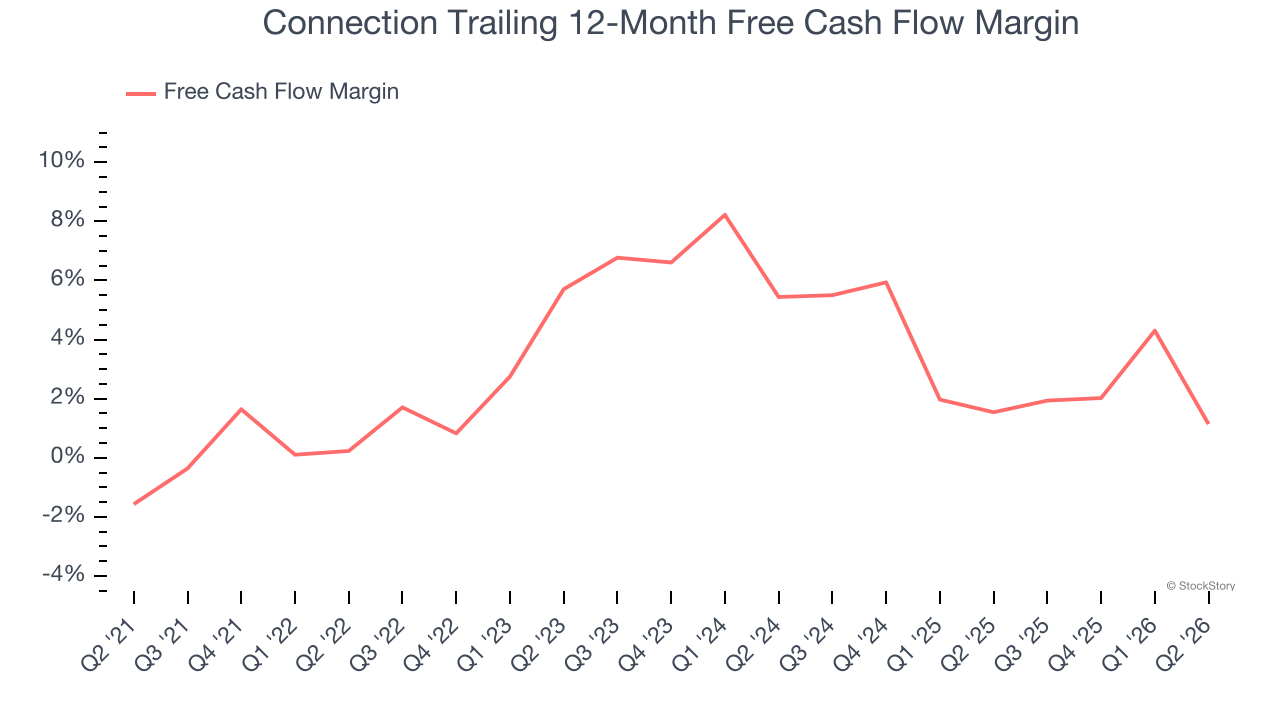
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Connection has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.7%, below what we’d expect for a business services business.
Final Judgment
Connection isn’t a terrible business, but it isn’t one of our picks. Following the recent surge, the stock trades at 19.7× forward P/E (or $87.13 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Connection
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.