
Valmont has followed the market’s trajectory closely, rising in tandem with the S&P 500 over the past six months. The stock has climbed by 21.6% to $466.89 per share while the index has gained 21.4%.
Is VMI a buy right now? Find out in our full research report, it’s free.
Why Does Valmont Spark Debate?
Credited with an invention in the 1950s that improved crop yields, Valmont (NYSE: VMI) provides engineered products and infrastructure services for the agricultural industry.
Two Things to Like:
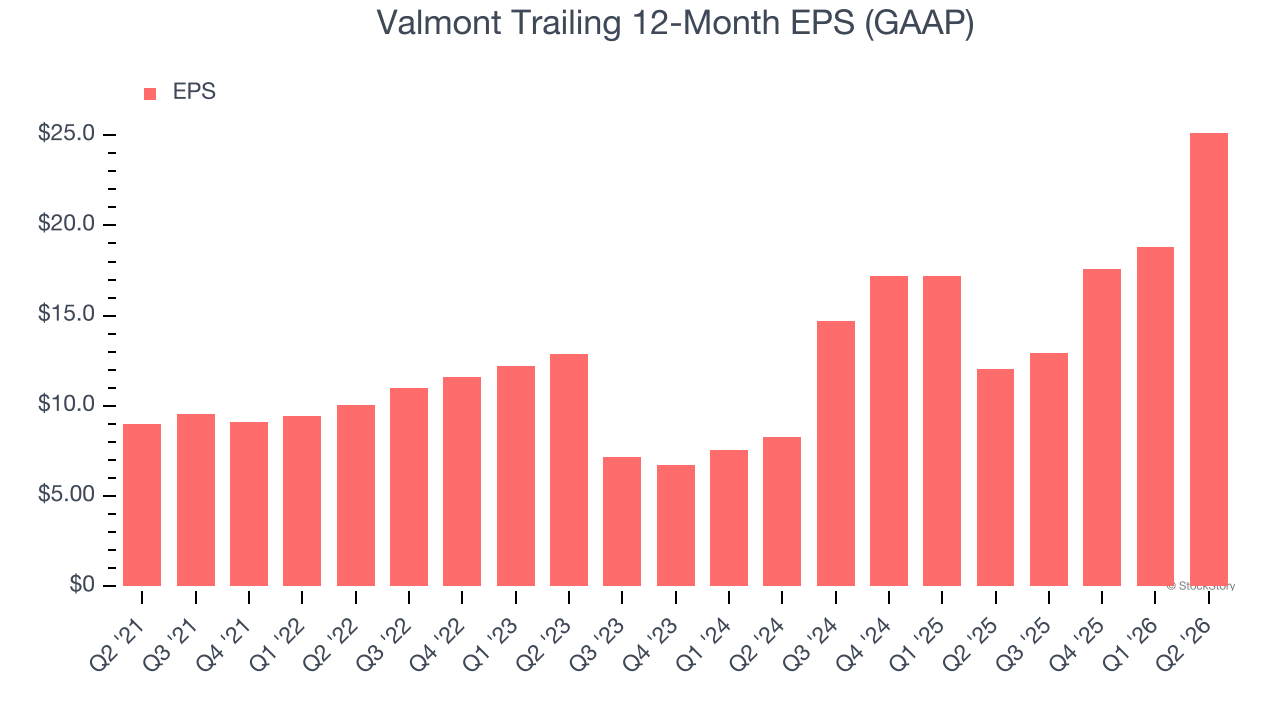
1. Outstanding Long-Term EPS Growth
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Valmont’s EPS grew at 22.9% compounded annual growth rate over the last five years, higher than its 5.7% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
2. Increasing Free Cash Flow Margin Juices Financials
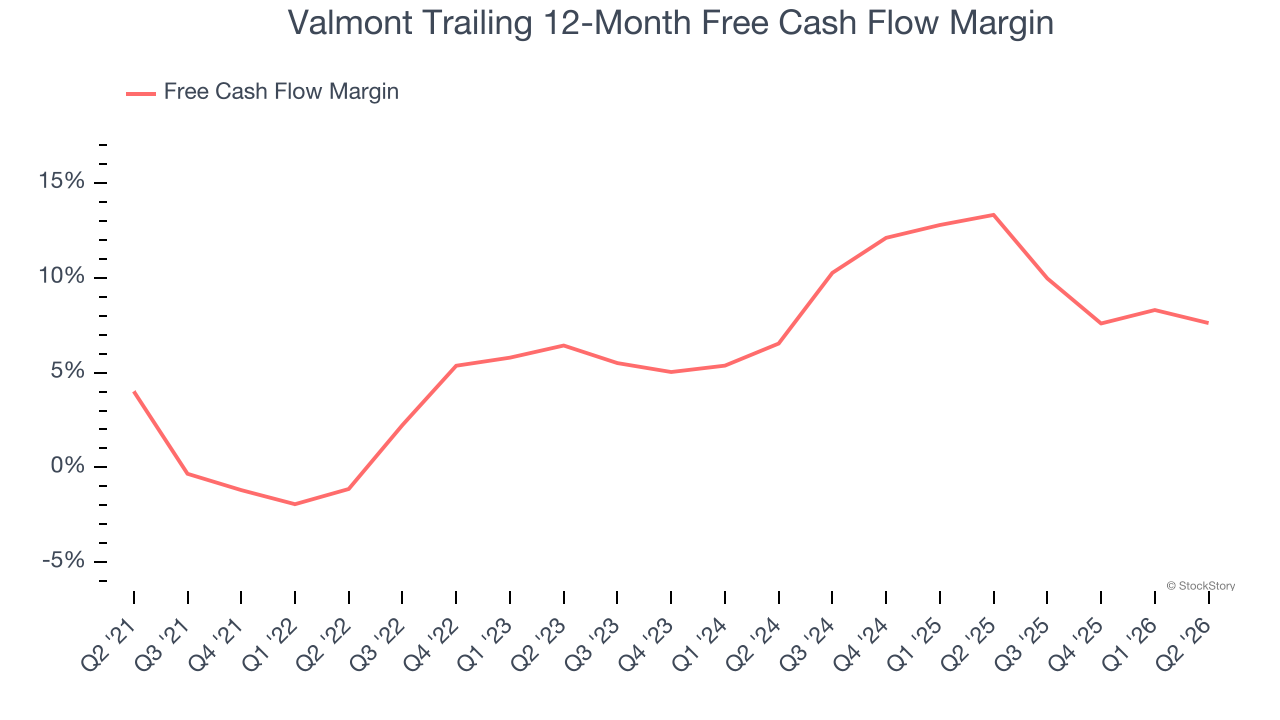
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Valmont’s margin expanded by 8.7 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Valmont’s free cash flow margin for the trailing 12 months was 7.6%.
One Reason to Be Careful:
Long-Term Revenue Growth Disappoints
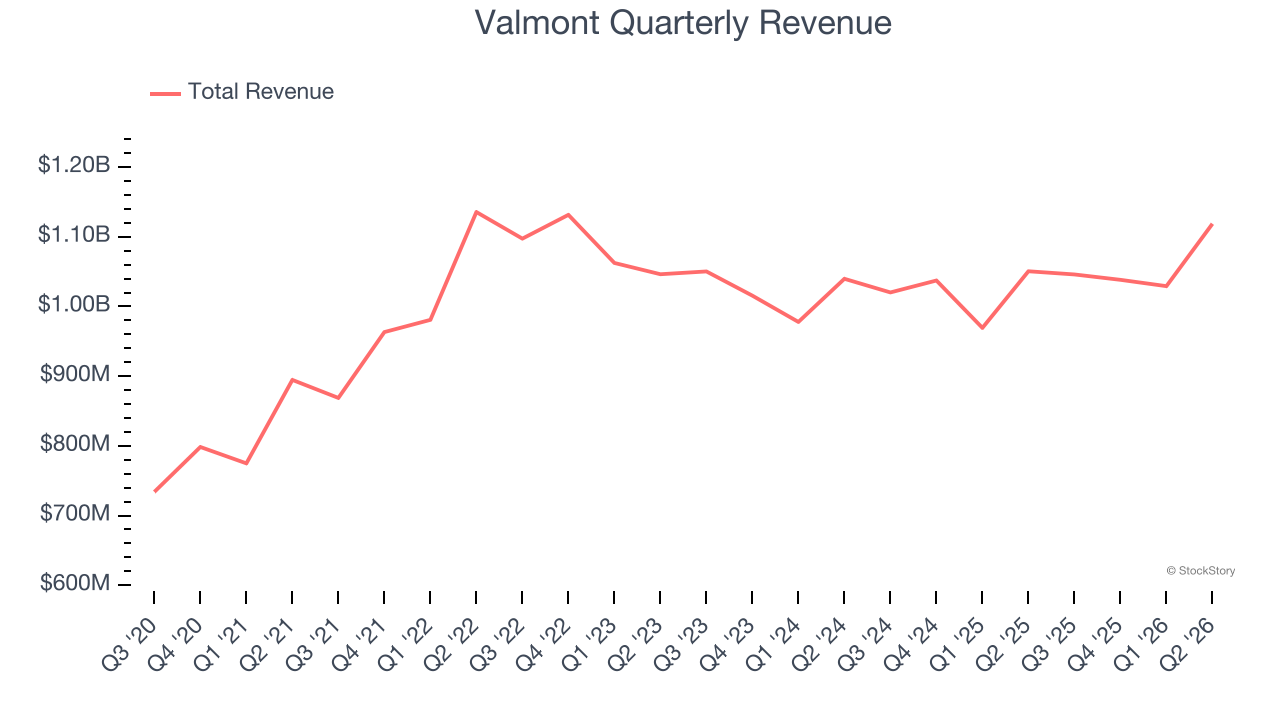
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Valmont grew its sales at a tepid 5.7% compounded annual growth rate. This wasn’t a great result compared to the rest of the industrials sector, but there are still things to like about Valmont.
Final Judgment
Valmont has huge potential even though it has some open questions. At $466.89 per share (or a forward price-to-sales ratio of 2×), is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.