Over the last six months, Clorox’s shares have sunk to $83.72, producing a disappointing 19% loss - a stark contrast to the S&P 500’s 12.8% gain. This might have investors contemplating their next move.
Is now the time to buy Clorox, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Clorox Not Exciting?
Even though the stock has become cheaper, we’re cautious about Clorox. Here are three reasons you should be careful with CLX, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
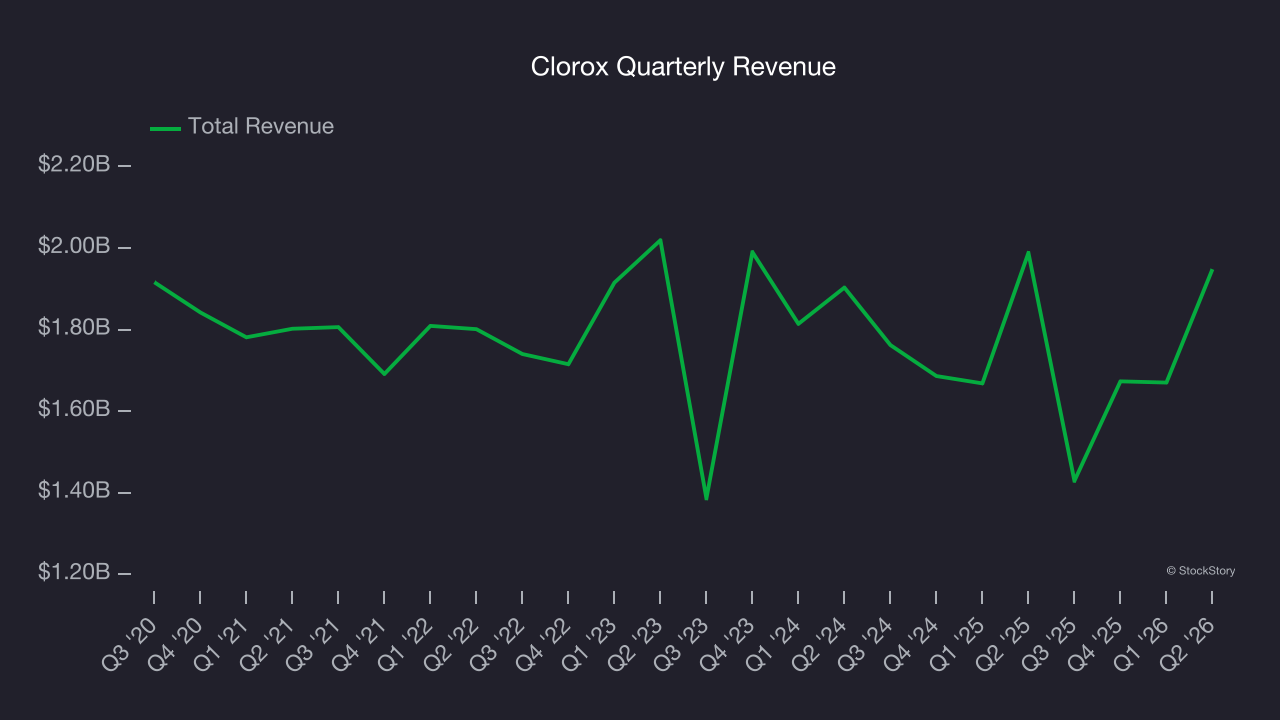
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Clorox’s demand was weak over the last three years as its sales fell at a 3.1% annual rate. This was below our standards and is a sign of lacking business quality.
2. Slow Organic Growth Suggests Waning Demand In Core Business
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
The demand for Clorox’s products has been stable over the last eight quarters but fell behind the broader sector. On average, the company has posted feeble year-on-year organic revenue growth of 1.7%. 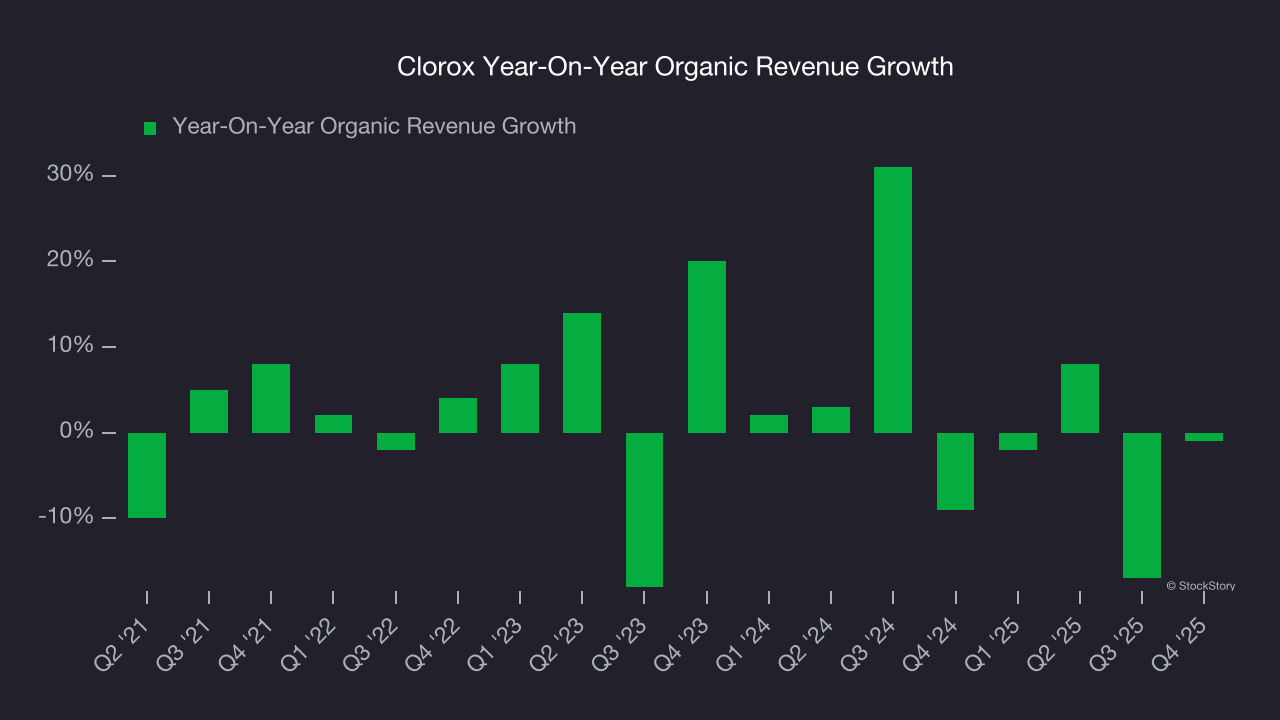
3. Free Cash Flow Margin Dropping
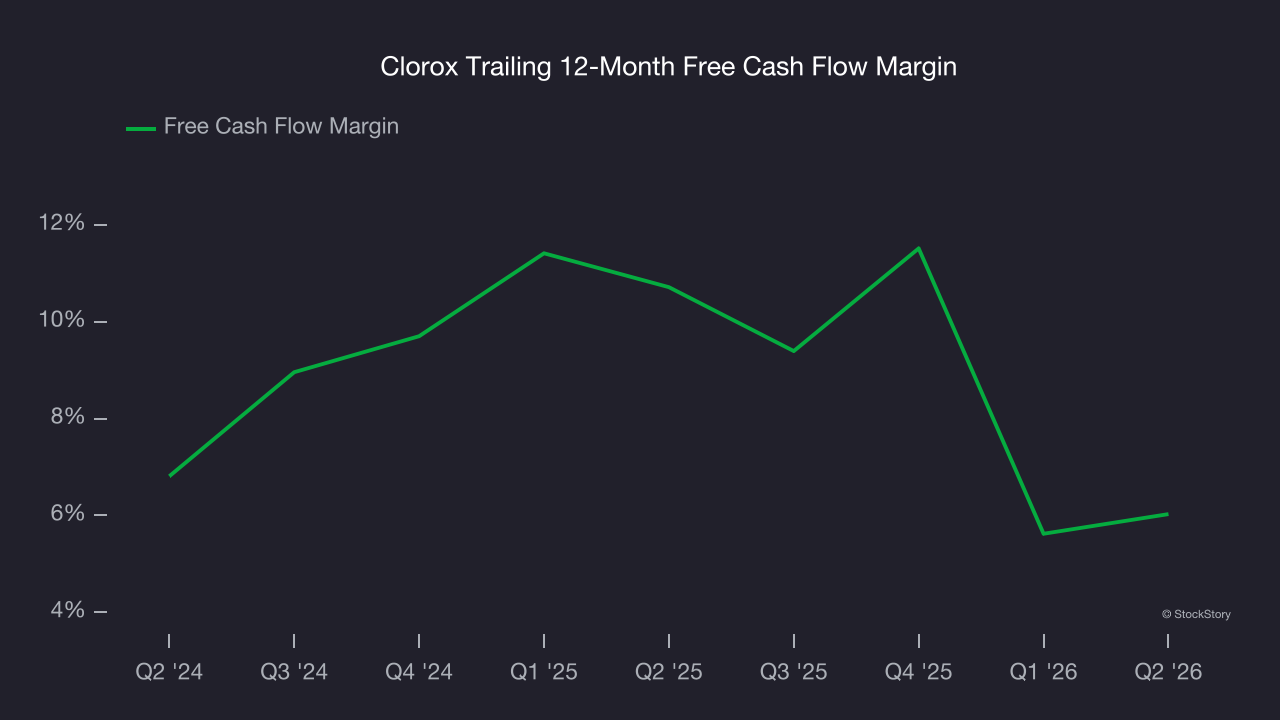
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Clorox’s margin dropped by 4.7 percentage points over the last year. If its declines continue, it could signal increasing investment needs and capital intensity. Clorox’s free cash flow margin for the trailing 12 months was 6%.
Final Judgment
Clorox’s business quality ultimately falls short of our standards. Following the recent decline, the stock trades at 14.6× forward P/E (or $83.72 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at our favorite semiconductor picks and shovels play.
Stocks We Like More Than Clorox
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.