Estée Lauder has been on fire lately. In the past six months alone, the company’s stock price has rocketed 40%, reaching $108.25 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Estée Lauder, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Estée Lauder not exciting?
Despite the momentum, we’re passing on Estée Lauder for now. Here are three reasons you should be careful with EL, plus one stock we’d rather own.
1. Core business falling behind as organic sales decline
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
Estée Lauder’s demand has been falling over the last eight quarters, and on average, its organic sales have declined by 2.4% year on year. 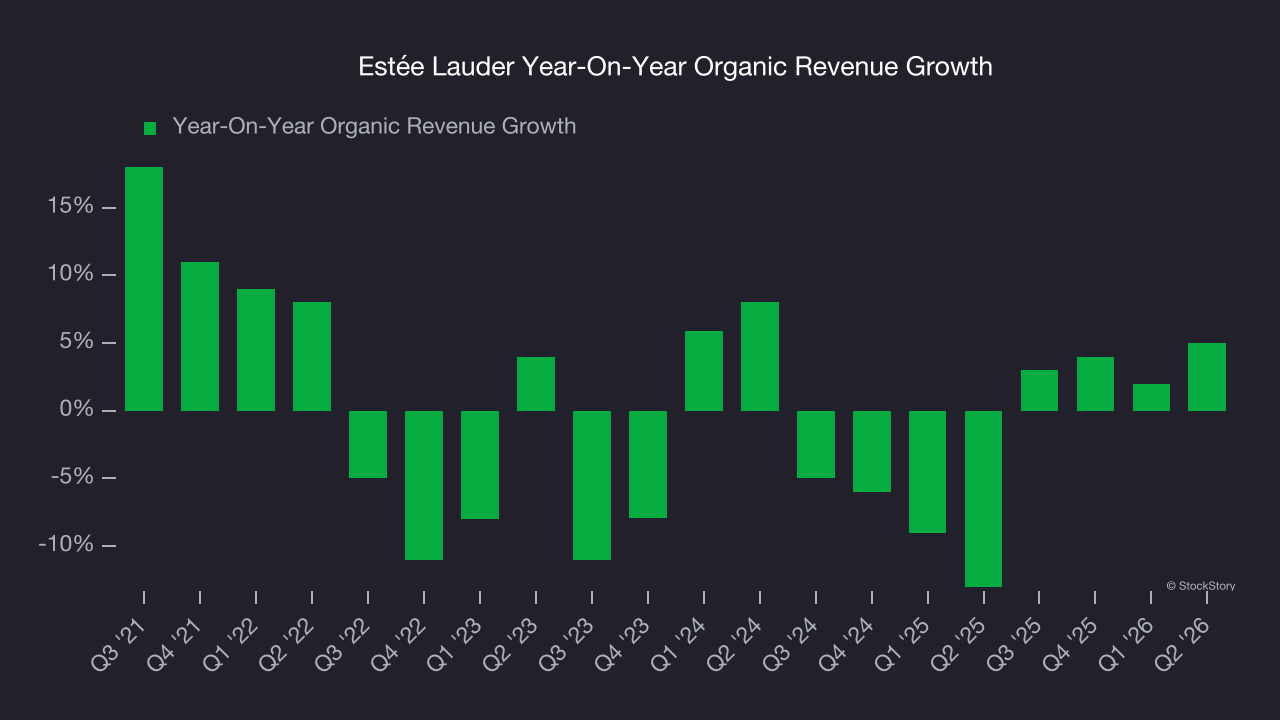
2. Breakeven operating margin raises questions
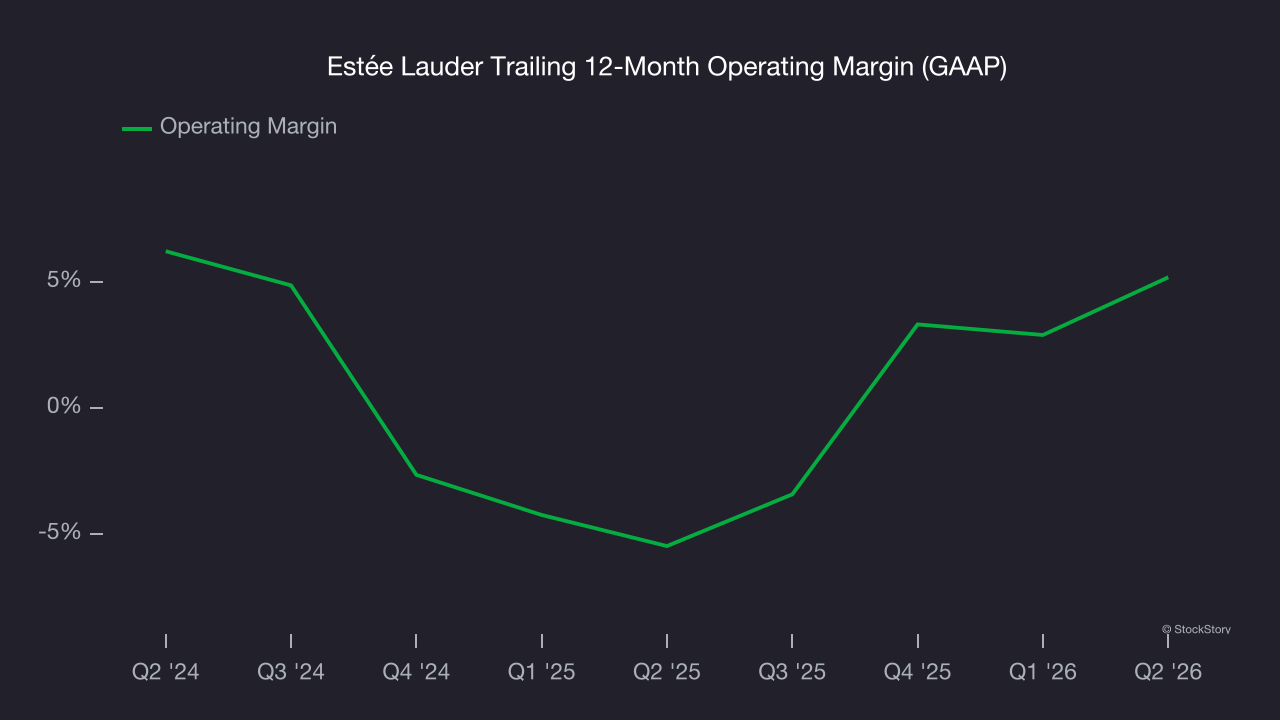
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Estée Lauder was roughly breakeven when averaging the last two years of quarterly operating profits, lousy for a consumer staples business. This result is surprising given its high gross margin as a starting point.
3. EPS trending down
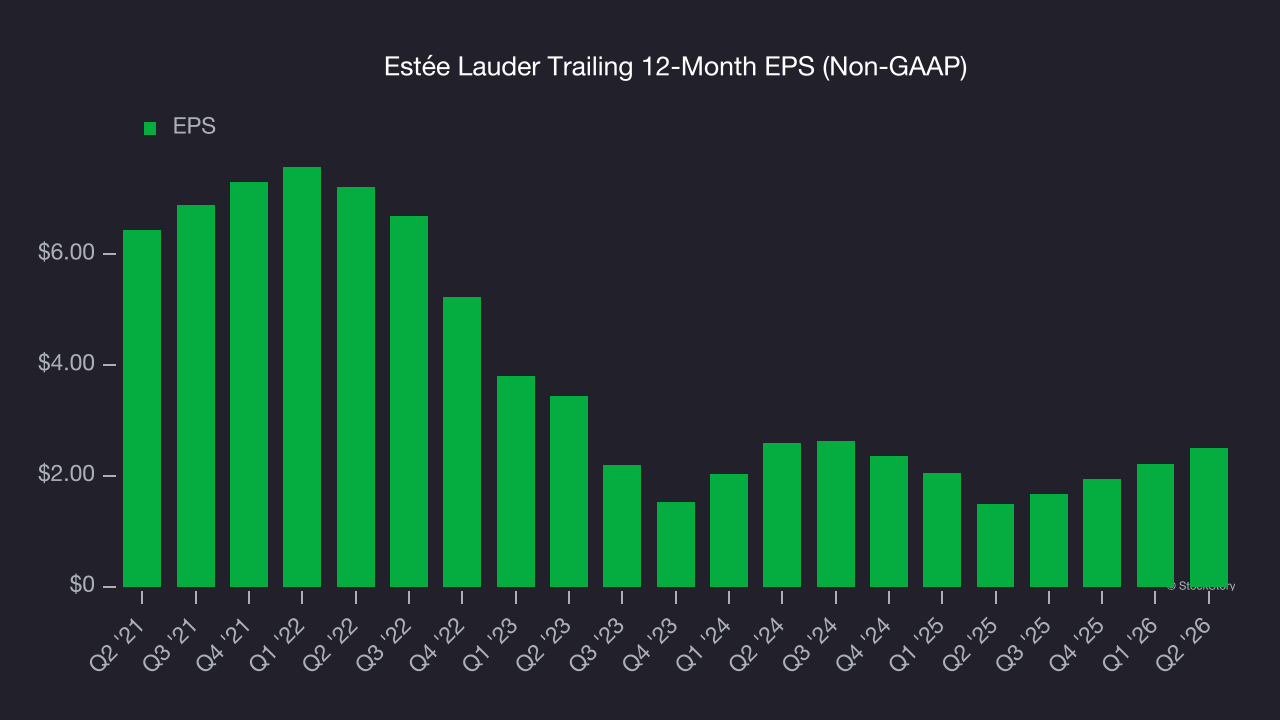
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Estée Lauder, its EPS declined by 10.1% annually over the last three years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
Final judgment
Estée Lauder isn’t a terrible business, but it isn’t one of our picks. Following the recent surge, the stock trades at 32.4× forward P/E (or $108.25 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better stocks to buy right now. Let us point you toward a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks we would buy instead of Estée Lauder
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.