Agricultural and farm machinery company AGCO (NYSE: AGCO) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 8.6% year on year to $2.26 billion. The company’s full-year revenue guidance of $9.9 billion at the midpoint came in 2.7% below analysts’ consensus estimates. Its non-GAAP profit of $1.05 per share was 21.5% above analysts’ consensus estimates.
For more on AGCO, read our free full research report.
AGCO (AGCO) Q3 2026 highlights:
- Revenue $2.26 billion vs S&P analysts’ consensus estimates of $2.33 billion (8.6% year-on-year decline, 2.7% miss)
- Adjusted EPS $1.05 vs S&P analysts’ consensus estimates of $0.86 (21.5% beat)
- Revenue guidance The company lowered its revenue guidance for the full year to $9.9 billion at the midpoint from $10.15 billion, a 2.5% decrease
- Adjusted EPS guidance $5.50 at the midpoint for the full year, missing analysts’ consensus estimates by 1.6%
- Operating margin 5.1%, in line with the same quarter last year
- Free cash flow -$488.8 million, down from $2.1 million in the same quarter last year
- Market capitalization $7.15 billion
"AGCO delivered resilient third-quarter results in what is the weakest global industry demand environment in more than a decade," said Eric Hansotia, AGCO's Chairman, President and CEO. "While elevated input costs and uncertainty around commodity markets and the trade environment pushed industry demand below the last cyclical trough, we aligned production with demand, managed dealer inventories and maintained cost discipline. We also advanced our Farmer-First strategy by strengthening the market position of our premium brands and expanding precision agriculture solutions that help farmers automate tasks, address labor constraints and get more from their equipment."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. AGCO struggled to consistently generate demand over the last five years as its revenue dropped at a 1.1% annual rate, falling short of our standards and suggesting poor business quality.
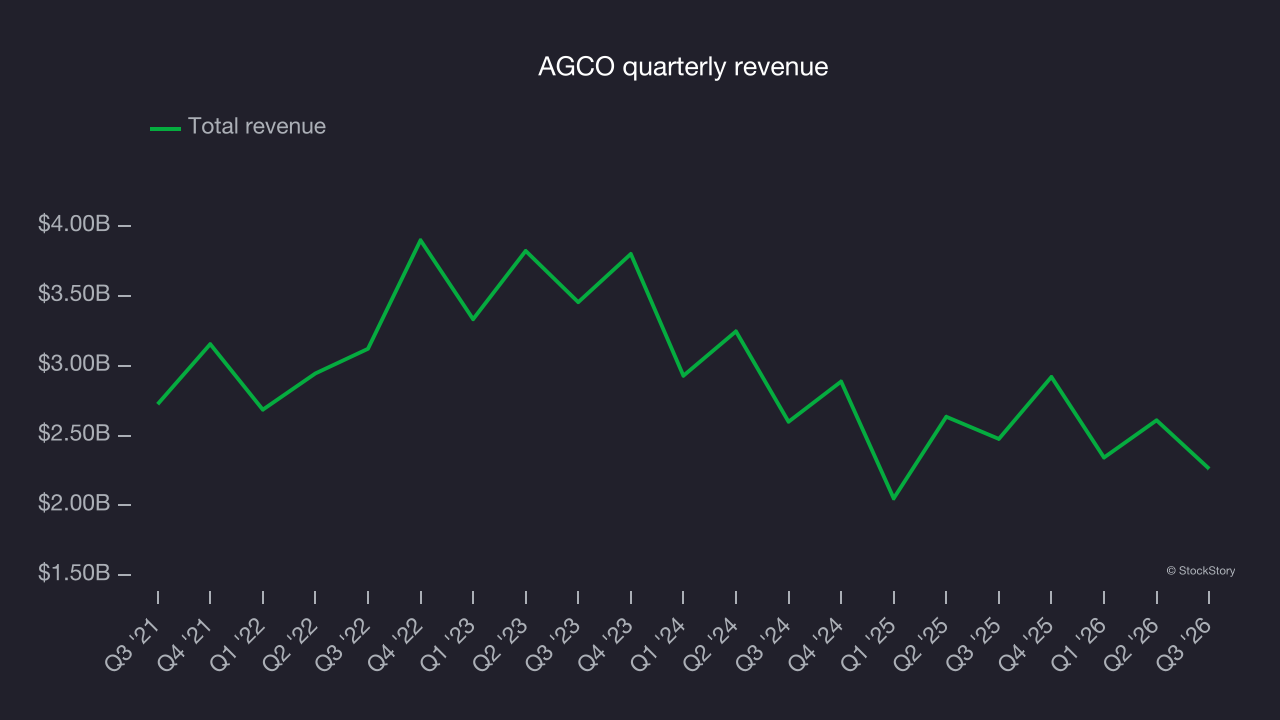
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. AGCO’s recent performance shows its demand remained suppressed as its revenue has declined by 10.2% annually over the last two years. 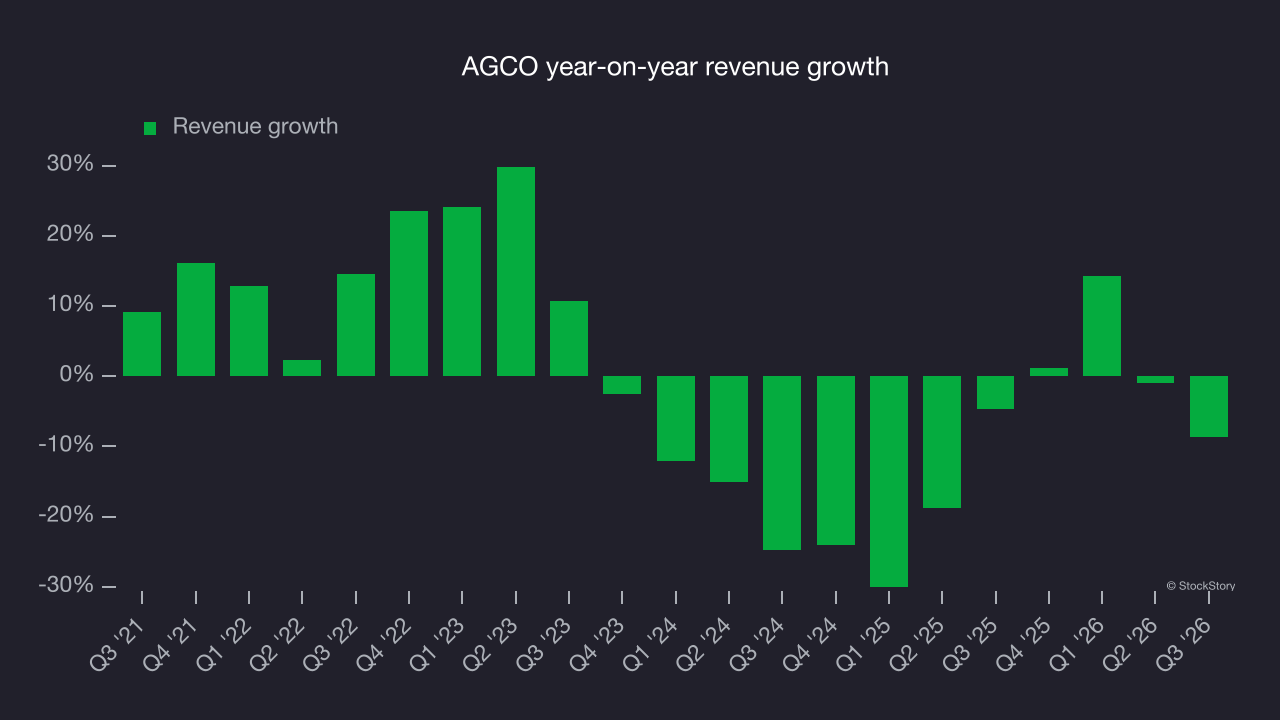
This quarter, AGCO missed Wall Street’s consensus estimates and reported an uninspiring 8.6% year-on-year revenue decline, generating $2.26 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 4.5% over the next 12 months, according to S&P. While this projection implies its newer products and services will spur better top-line performance, it is still below average for the sector.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
AGCO was profitable over the last five years but held back by its large cost base. Its average operating margin of 6.8% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
Looking at the trend in its profitability, AGCO’s operating margin decreased by 3.3 percentage points over the last five years. That poor performance shows that costs were rising and it couldn’t pass them on to its customers.
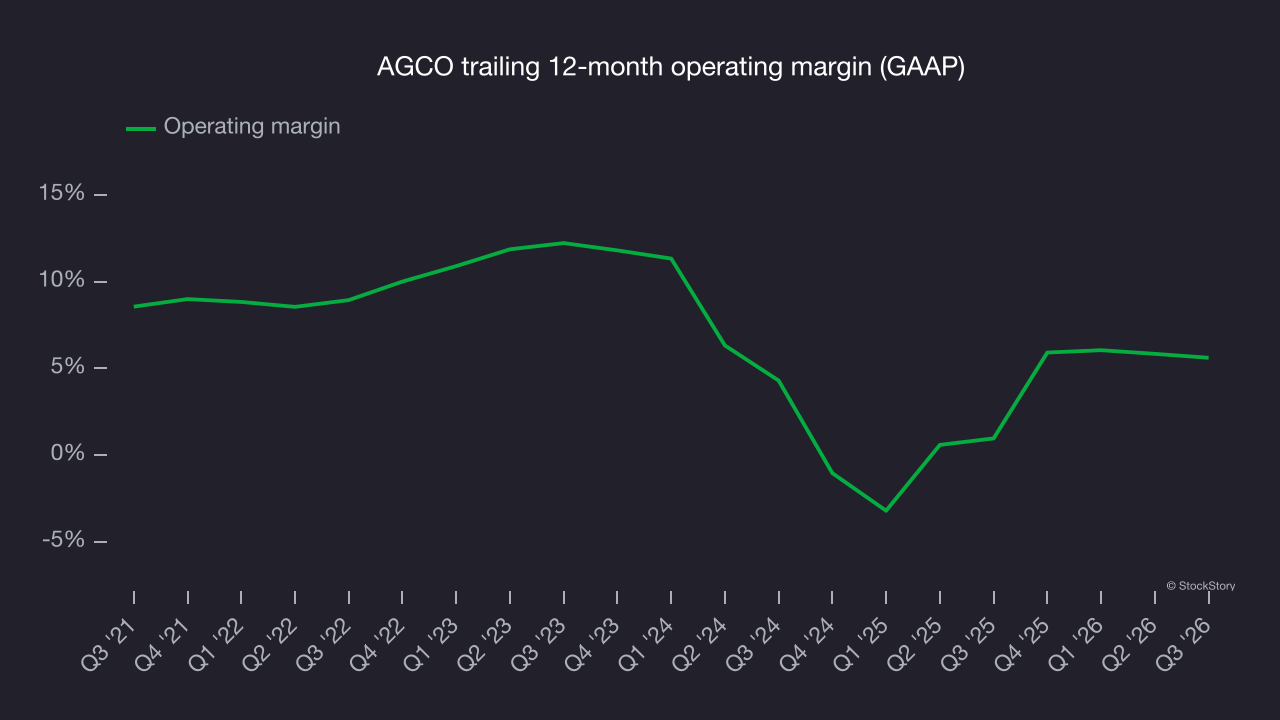
This quarter, AGCO generated an operating margin of 5.1%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
AGCO’s EPS declined by 8.7% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
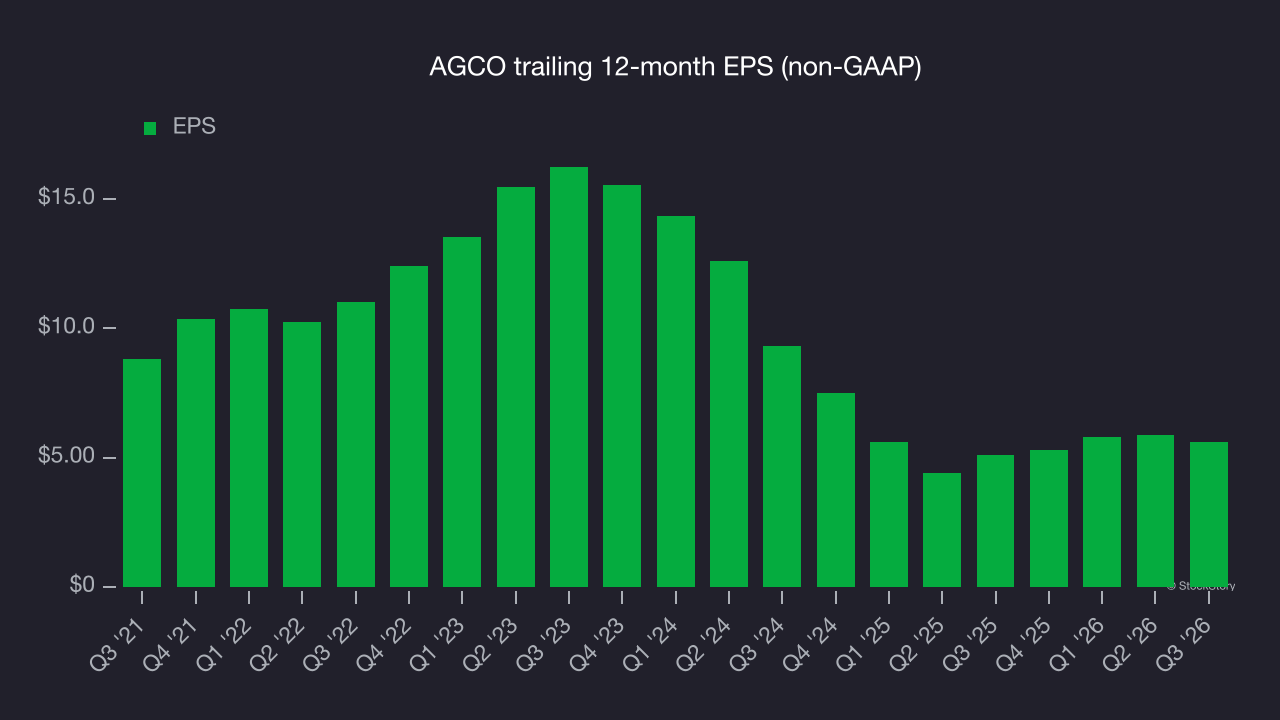
A closer look at AGCO’s earnings helps explain its performance. As mentioned earlier, AGCO’s operating margin was flat this quarter but declined by 3.3 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For AGCO, its two-year annual EPS declines of 22.5% show it’s continued to underperform. These results were poor across the periods examined.
In Q3, AGCO reported adjusted EPS of $1.05, down from $1.35 in the same quarter last year. Despite falling year on year, the result comfortably exceeded analysts’ consensus estimates. Over the next 12 months, Wall Street expects AGCO’s full-year EPS to grow 24.1% from $5.59 to $6.94, according to S&P.
Key takeaways from AGCO’s Q3 results
AGCO’s EPS beat analysts’ consensus estimates, but the revenue picture was weaker: quarterly revenue missed expectations and full-year revenue guidance fell short of Wall Street’s consensus. Those shortfalls made this a weaker quarter overall. Shares fell 3.4% to $98.73 immediately after the report.
AGCO underperformed this quarter. In deciding whether that creates an investment opportunity, the latest results matter less than longer-term business quality and valuation. For more on those factors, read the full research report here (it’s free).