A company that generates cash isn’t automatically a winner. Some businesses stockpile cash but fail to reinvest wisely, limiting their ability to expand.
Luckily for you, we built StockStory to help you separate the good from the bad. That said, here is one cash-producing company that excels at turning cash into shareholder value and two best left off your watchlist.
Two Stocks to Sell:
American Outdoor Brands (AOUT)
Trailing 12-Month Free Cash Flow Margin: 9.7%
Spun off from Smith and Wesson in 2020, American Outdoor Brands (NASDAQ: AOUT) is an outdoor and recreational products company that offers outdoor and shooting sports products but does not sell firearms themselves.
Why Are We Out on AOUT?
- Sales tumbled by 7.1% annually over the last five years, showing consumer trends are working against it
- Low free cash flow margin of 5% for the last two years gives it little breathing room, constraining its ability to self-fund growth or return capital to shareholders
- Returns on capital are increasing as management makes relatively better investment decisions
American Outdoor Brands is trading at $16.22 per share, or 27x forward P/E. To fully understand why you should be careful with AOUT, check out our full research report (it’s free).
West Pharmaceutical Services (WST)
Trailing 12-Month Free Cash Flow Margin: 13.1%
Founded in 1923 and serving as a critical link in the pharmaceutical supply chain, West Pharmaceutical Services (NYSE: WST) manufactures specialized packaging, containment systems, and delivery devices for injectable drugs and healthcare products.
Why Is WST Not Exciting?
- Annual revenue growth of 5.7% over the last five years was below our standards for the healthcare sector
- Costs have risen faster than its revenue over the last five years, causing its adjusted operating margin to decline by 5.3 percentage points
- Waning returns on capital imply its previous profit engines are losing steam
At $375.45 per share, West Pharmaceutical Services trades at 39.3x forward P/E. Dive into our free research report to see why there are better opportunities than WST.
One Stock to Buy:
Nextpower (NXT)
Trailing 12-Month Free Cash Flow Margin: 15.1%
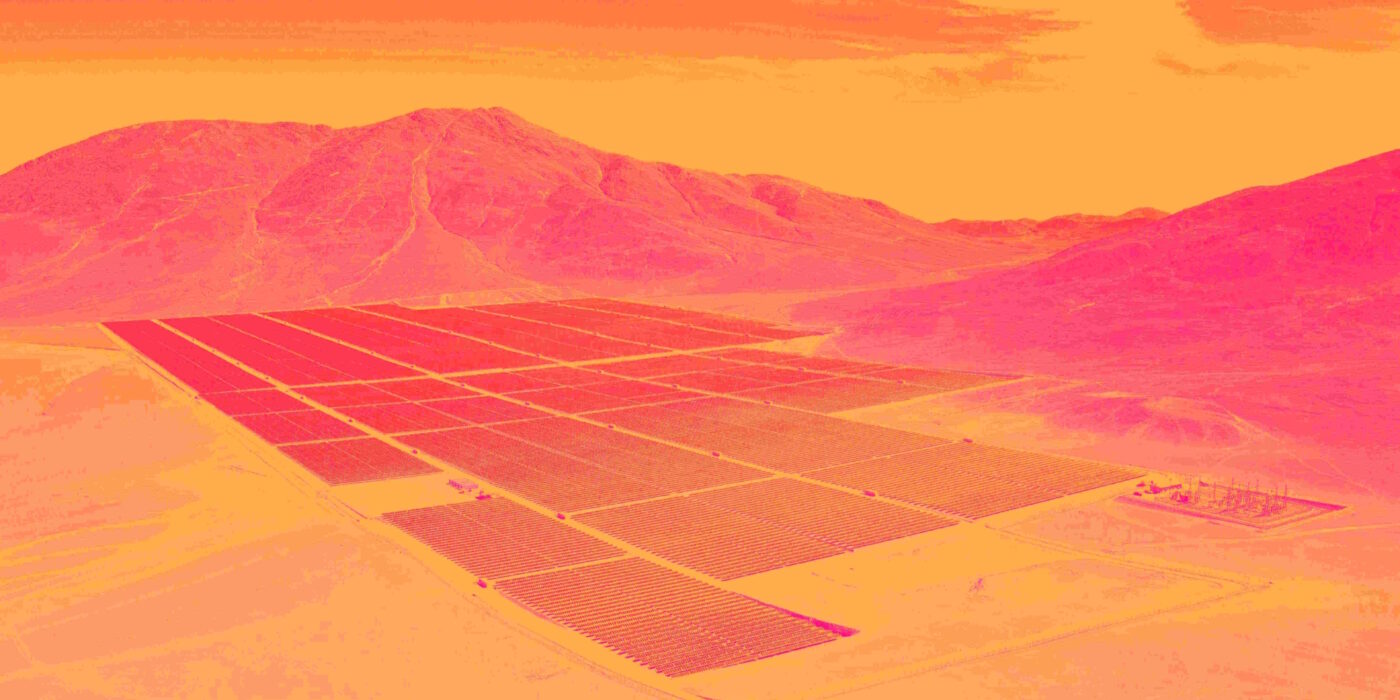
With its technology playing a key role in the massive 1.2 gigawatt Noor Abu Dhabi solar farm project, Nextpower (NASDAQ: NXT) is a provider of solar tracker systems that help solar panels follow the sun.
Why Will NXT Outperform?
- Annual revenue growth of 15.1% over the last two years was superb and indicates its market share increased during this cycle
- Free cash flow margin grew by 23.4 percentage points over the last five years, giving the company more chips to play with
- Returns on capital are growing as management capitalizes on its market opportunities
Nextpower’s stock price of $84.57 implies a valuation ratio of 16.4x forward P/E. Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.