Since April 2026, Texas Roadhouse has been in a holding pattern, posting a small loss of 4.2% while floating around $156.38. The stock also fell short of the S&P 500’s 15.9% gain during that period.
Is now the time to buy TXRH? Or does the price properly account for its business quality and fundamentals? Find out in our full research report, it’s free.
Why Does Texas Roadhouse Spark Debate?
With locations often featuring Western-inspired decor, Texas Roadhouse (NASDAQ: TXRH) is an American restaurant chain specializing in Southern-style cuisine and steaks.
Two Positive Attributes:
1. Restaurant Growth Signals an Offensive Strategy
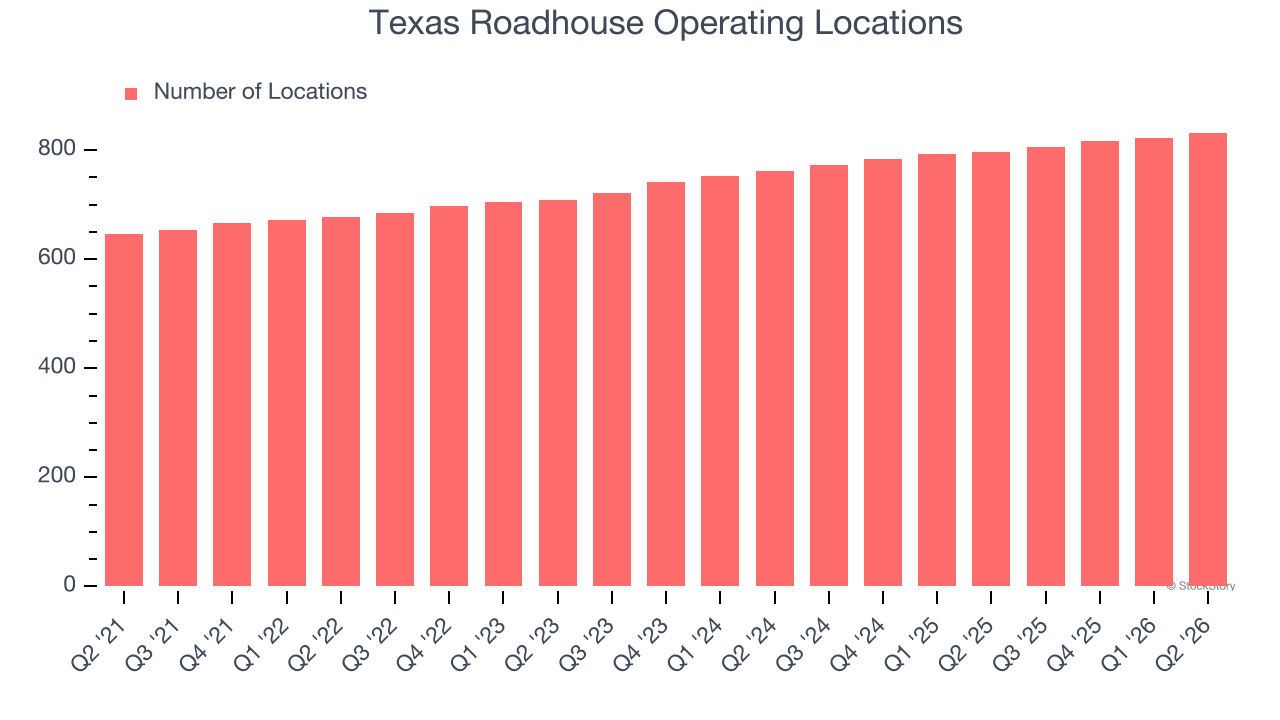
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
Texas Roadhouse operated 832 locations in the latest quarter. It has opened new restaurants at a rapid clip over the last two years, averaging 4.9% annual growth, much faster than the broader restaurant sector.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
2. Surging Same-Store Sales Show Increasing Demand
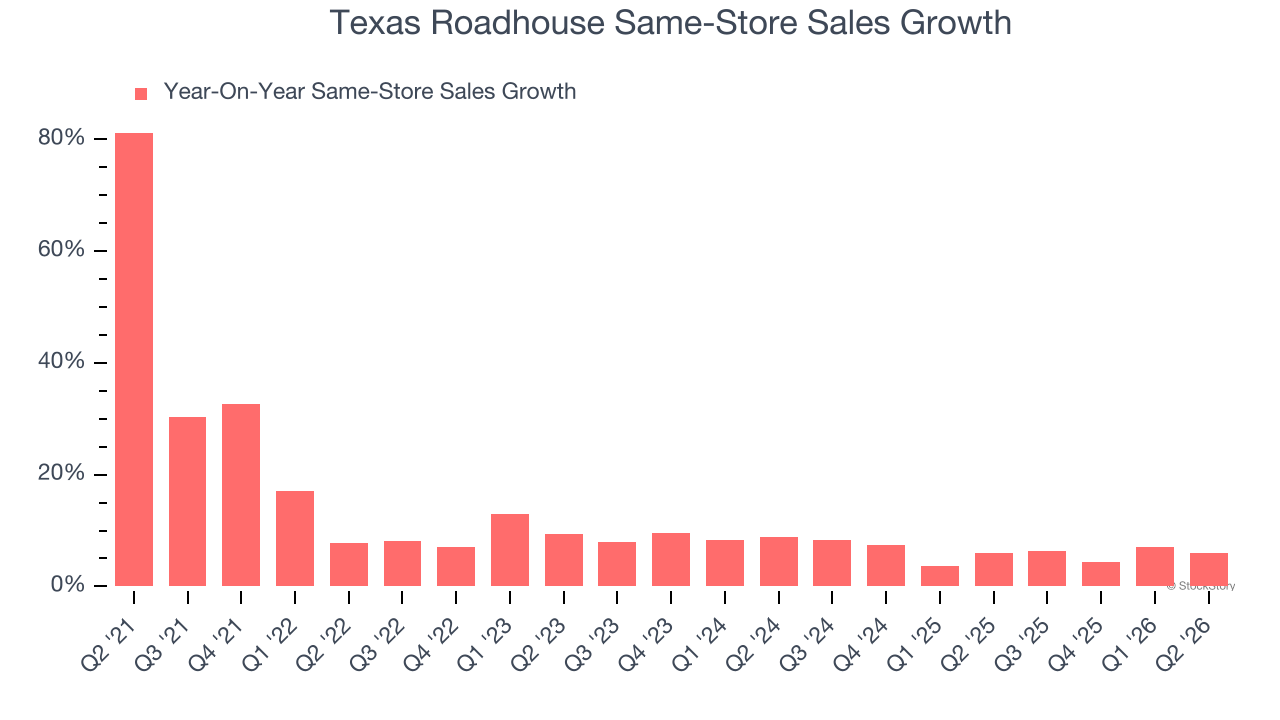
Same-store sales show the change in sales at restaurants open for at least a year. This is a key performance indicator because it measures organic growth.
Texas Roadhouse has been one of the most successful restaurant chains over the last two years thanks to skyrocketing demand within its existing dining locations. On average, the company has posted exceptional year-on-year same-store sales growth of 6.1%.
One Reason to Be Careful:
Low Gross Margin Reveals Weak Structural Profitability
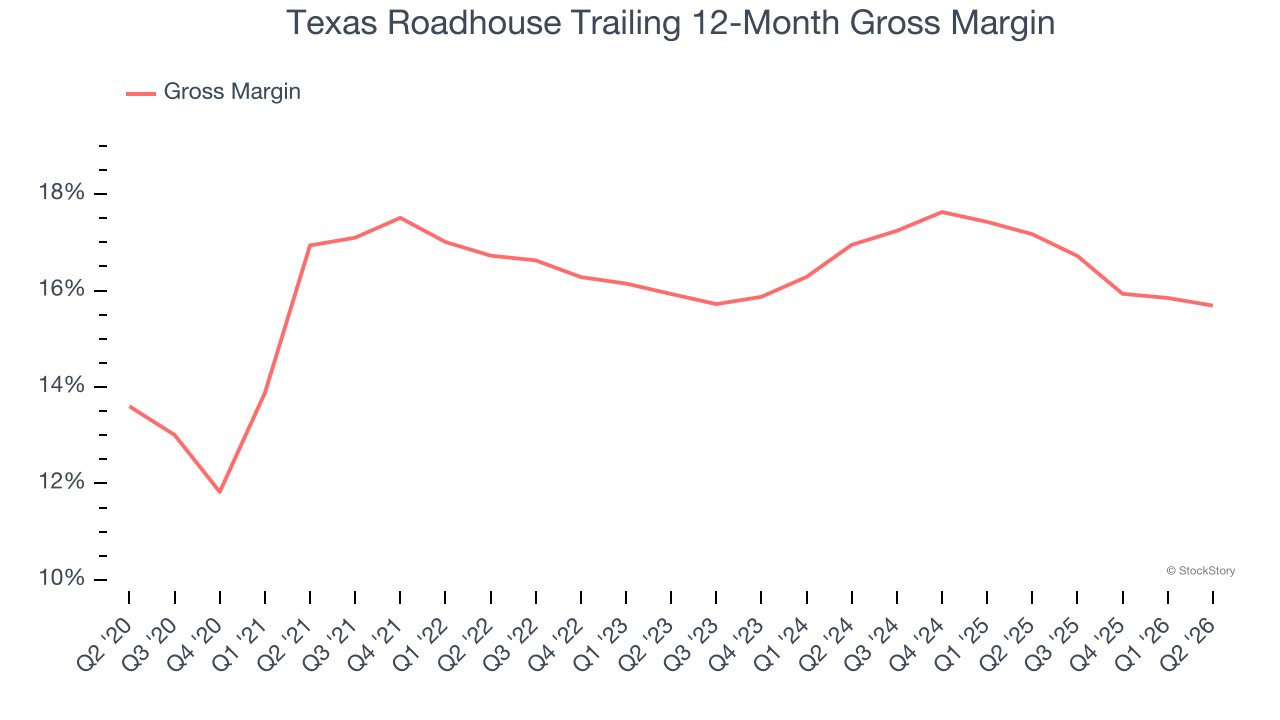
Gross profit margins are an important measure of a restaurant’s pricing power and differentiation, whether it be the dining experience or quality and taste of food.
Texas Roadhouse has bad unit economics for a restaurant company, signaling it operates in a competitive market and has little room for error if demand unexpectedly falls. As you can see below, it averaged a 16.4% gross margin over the last two years. Said differently, Texas Roadhouse had to pay a chunky $83.61 to its suppliers for every $100 in revenue.
Final Judgment
Texas Roadhouse’s merits more than compensate for its flaws. With its shares underperforming the market lately, the stock trades at 21.8× forward P/E (or $156.38 per share). Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.