Walker & Dunlop has gotten torched over the last six months - since April 2026, its stock price has dropped 21.7% to $35.12 per share. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Walker & Dunlop, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Walker & Dunlop Will Underperform?
Even though the stock has become cheaper, we don’t have much confidence in Walker & Dunlop. Here are three reasons why there are better opportunities than WD, plus one stock we’d rather own.
1. Declining Net Interest Income Reflects Weakness
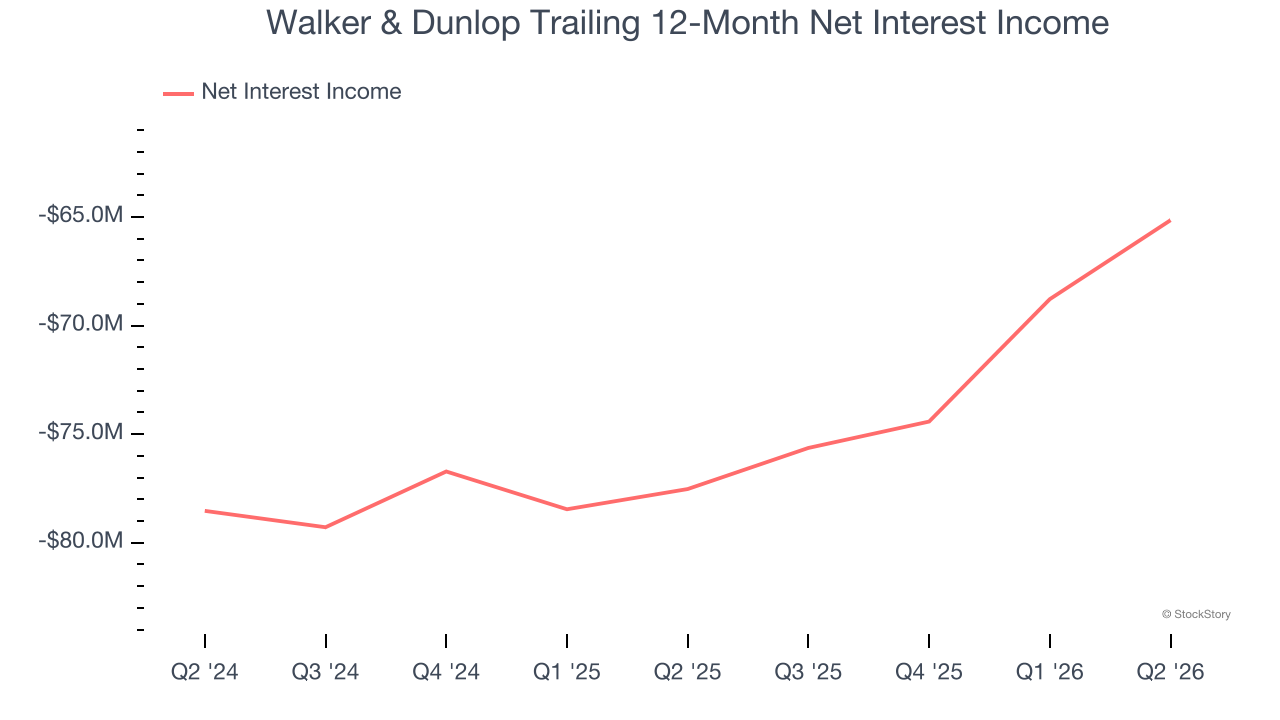
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
Walker & Dunlop’s net interest income has declined by 41.6% annually over the last five years, much worse than the broader banking industry. This shows that lending underperformed its other business lines.
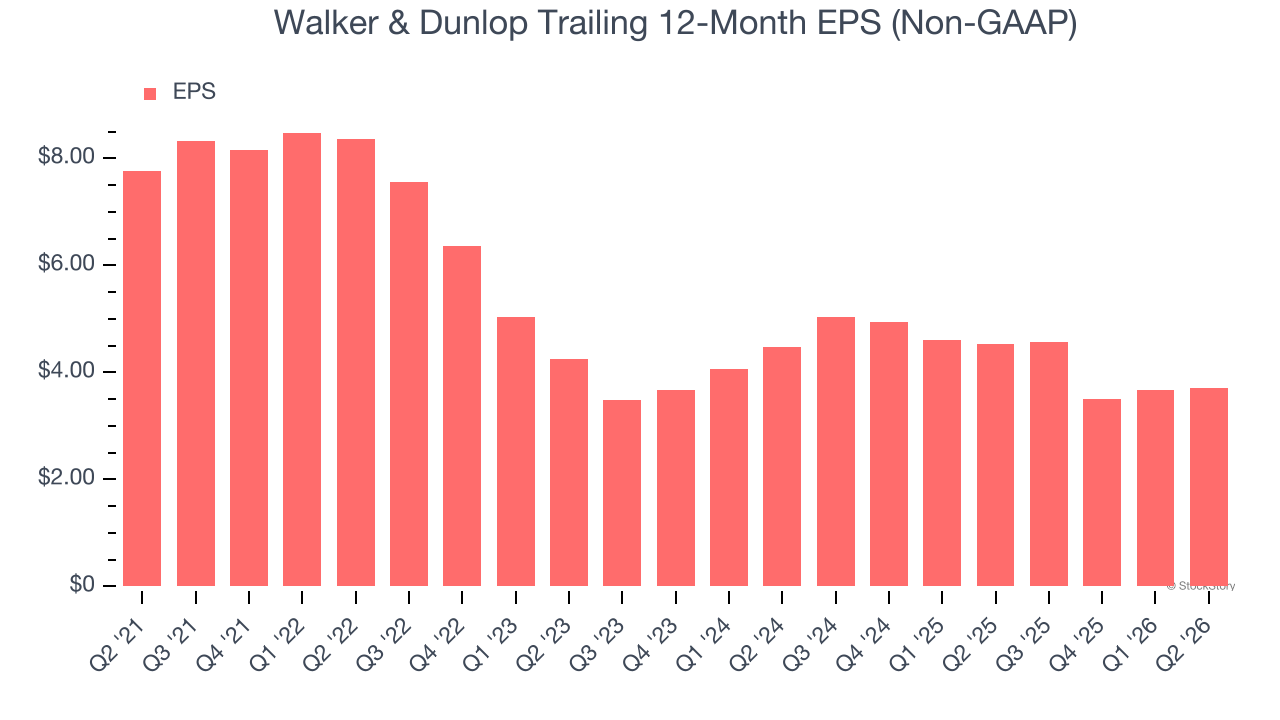
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Walker & Dunlop, its EPS declined by 13.7% annually over the last five years while its revenue grew by 3.1%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Substandard TBVPS Growth Indicates Limited Asset Expansion
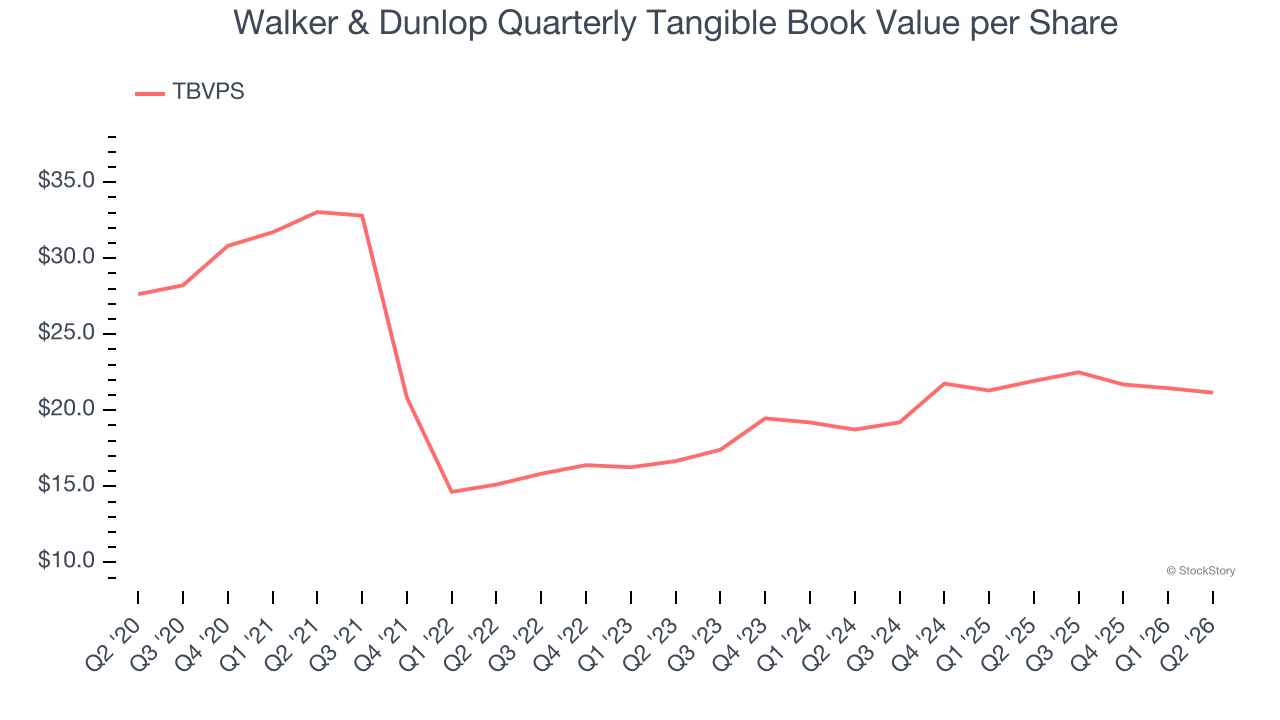
Tangible book value per share (TBVPS) serves as a key indicator of a bank’s financial strength, representing the hard assets available to shareholders after removing intangible assets that could evaporate during financial distress.
Disappointingly for investors, Walker & Dunlop’s TBVPS grew at a tepid 6.3% annual clip over the last two years.
Final Judgment
We cheer for all companies supporting the economy, but in the case of Walker & Dunlop, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 0.6× forward P/B (or $35.12 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d suggest looking at the most entrenched endpoint security platform on the market.
Stocks We Like More Than Walker & Dunlop
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.