Over the past six months, Petco’s stock price fell to $2.60. Shareholders have lost 6.7% of their capital, which is disappointing considering the S&P 500 has climbed by 7.2%. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Petco, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why do we think Petco will underperform?
Even though the stock has become cheaper, we’re passing on Petco for now. Here are three reasons why there are better opportunities than WOOF, plus one stock we’d rather own.
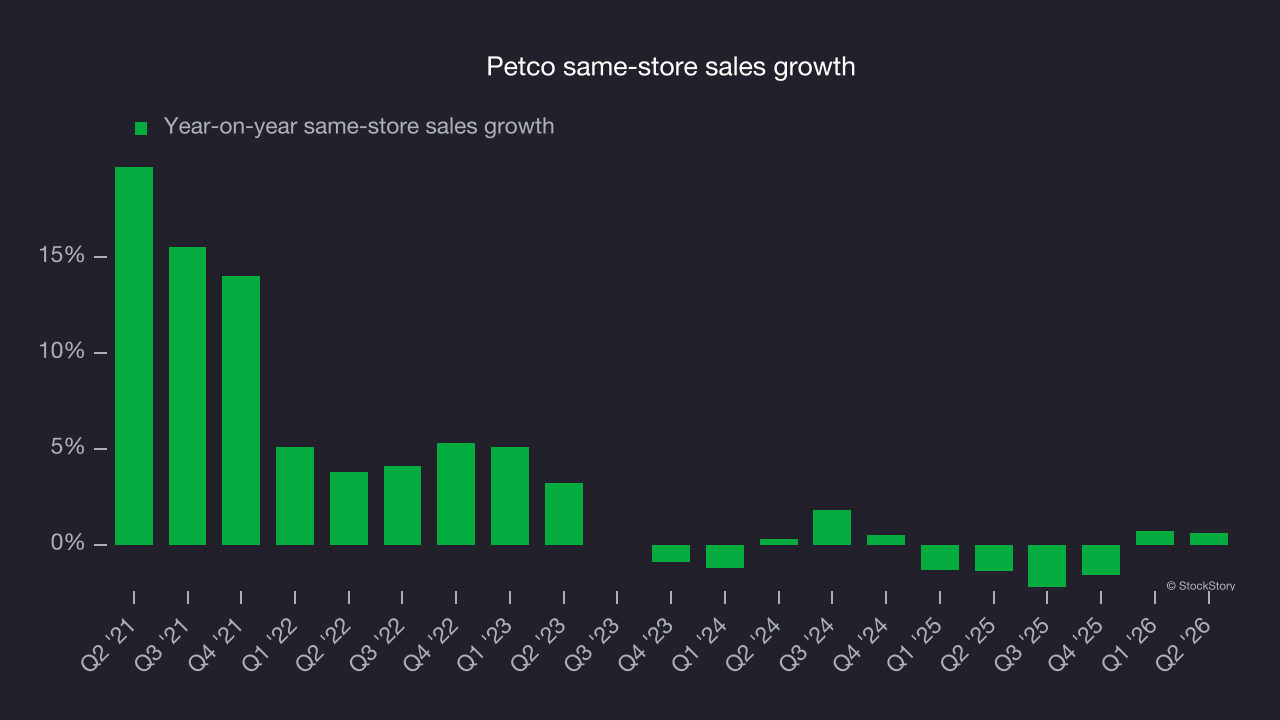
1. Flat same-store sales indicate weak demand
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Petco’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat.
2. Previous growth initiatives have lost money
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Petco’s five-year average ROIC was negative 3.8%, meaning management lost money while trying to expand the business. Its returns were among the worst in the consumer retail sector.
3. High debt levels increase risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Petco’s $2.82 billion of debt exceeds the $293.5 million of cash on its balance sheet. Furthermore, its 6× net-debt-to-EBITDA ratio (based on its EBITDA of $424.4 million over the last 12 months) shows the company is overleveraged.
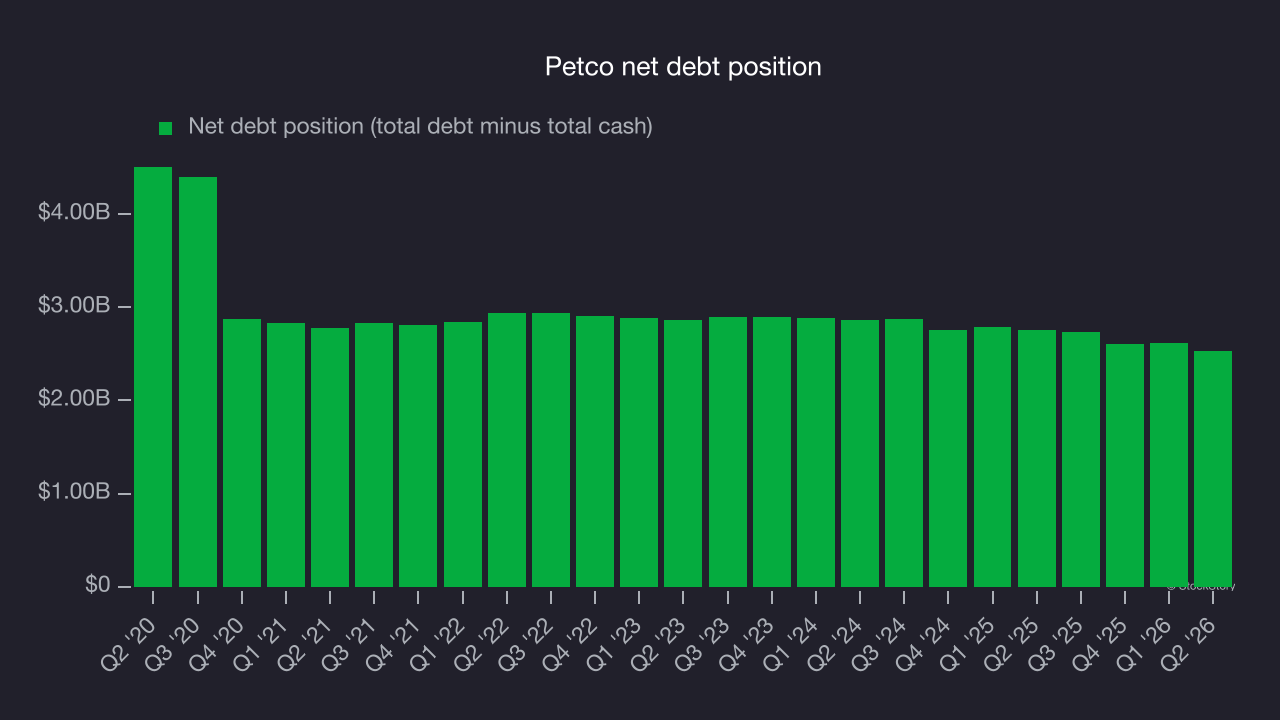
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Petco could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Petco can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final judgment
We see the value of companies helping consumers, but in the case of Petco, we’re out. Following the recent decline, the stock trades at 10.8× forward P/E (or $2.60 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are superior stocks to buy right now. We’d suggest looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks we like more than Petco
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.