Power resiliency solutions provider American Superconductor (NASDAQ: AMSC) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 (fiscal Q2 2026), with revenue up 42.8% year on year to $94.04 million. Its non-GAAP profit of $0.19 per share was 6.2% below analysts’ consensus estimates.
For more on American Superconductor, read our full research report for free.
American Superconductor (AMSC) Q3 CY2026 highlights:
- Revenue $94.04 million vs S&P analysts’ consensus estimates of $87.73 million (42.8% year-on-year growth, 7.2% beat)
- Adjusted EPS $0.19 vs S&P analysts’ consensus estimates of $0.20 (6.2% miss)
- Operating margin 5.7%, up from 4.5% in the same quarter last year
- Free cash flow margin 30.6%, up from 7.7% in the same quarter last year
- Market capitalization $1.34 billion
"We delivered over $90 million in second quarter revenue, up more than 40% year-over-year, reflecting continued customer-requested accelerations in project deliveries through the first half of our fiscal year. During the second quarter, our power solutions saw excellent traction with orders exceeding $95 million, driven primarily by traditional and renewable energy as well as demand from materials and utility customers. We also generated over $45 million in operating cash during the first half of the year. Our momentum along with our quarter-on-quarter gross margin expansion and significant operating cash flow provides a high degree of flexibility for our long-term strategic investments in growth,” said Daniel P. McGahn, Chairman, President, and CEO, AMSC. “Looking forward, we expect revenue to average approximately $90 million for each of our first three quarters. We anticipate strong demand to continue through the second half, ending the fiscal year on a high note and delivering significant year-over-year growth for the full fiscal year."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. American Superconductor’s 28.9% annualized revenue growth over the last five years was strong. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
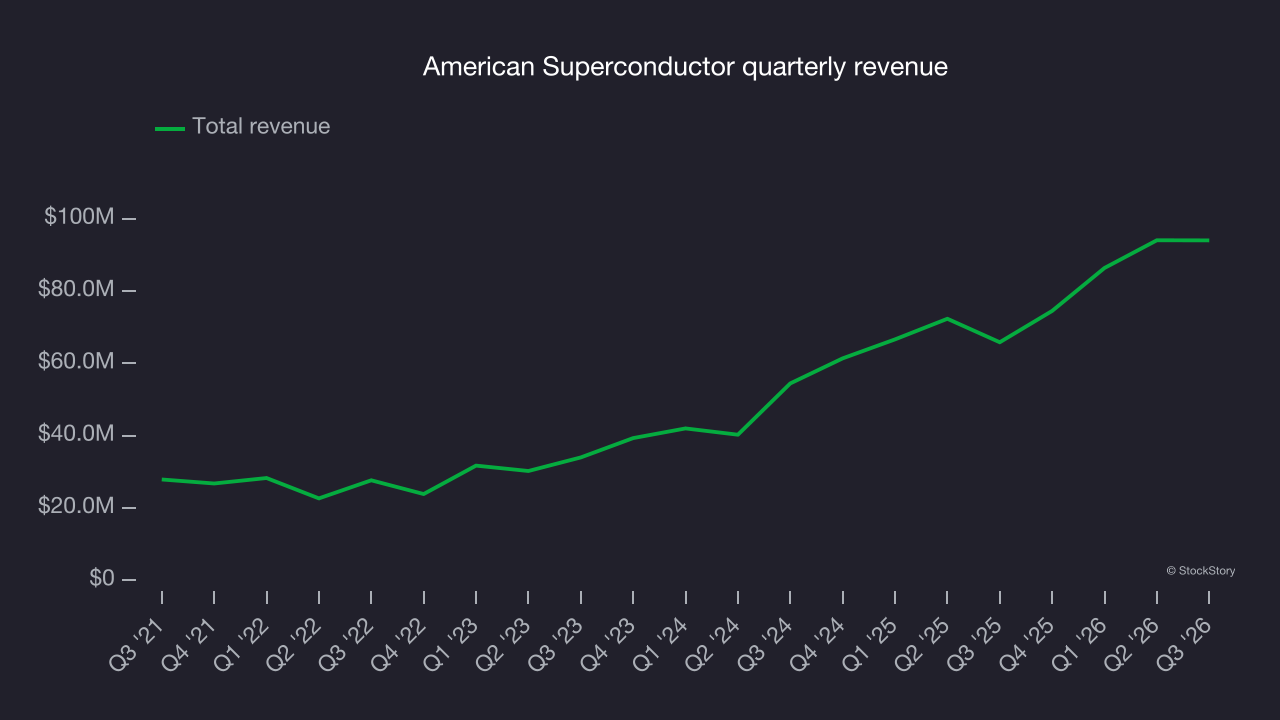
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. American Superconductor’s annualized revenue growth of 40.8% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated.
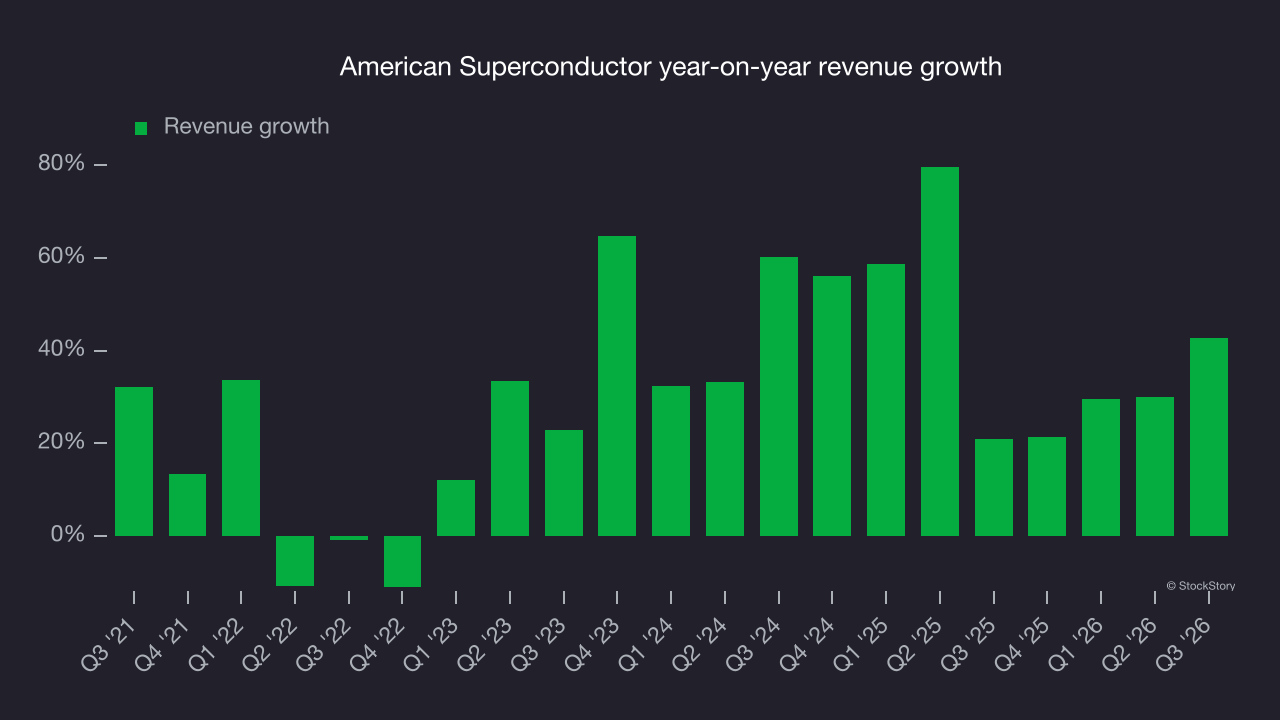
This quarter, American Superconductor reported year-on-year revenue growth of 42.8%, and its $94.04 million of revenue beat Wall Street’s consensus estimates by 7.2%.
Looking ahead, sell-side analysts expect revenue to grow 13% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, that is a strong growth forecast and implies the market expects its products and services to succeed.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Although American Superconductor was profitable this quarter from an operational perspective, it’s generally struggled over a longer time period. Its expensive cost structure has contributed to an average operating margin of negative 1.9% over the last five years. Unprofitable industrials companies require extra scrutiny because they can be vulnerable when conditions deteriorate.
On the positive side, American Superconductor’s operating margin rose by 33.2 percentage points over the last five years, as its revenue growth gave it operating leverage. Still, it will take much more for the company to show consistent profitability.
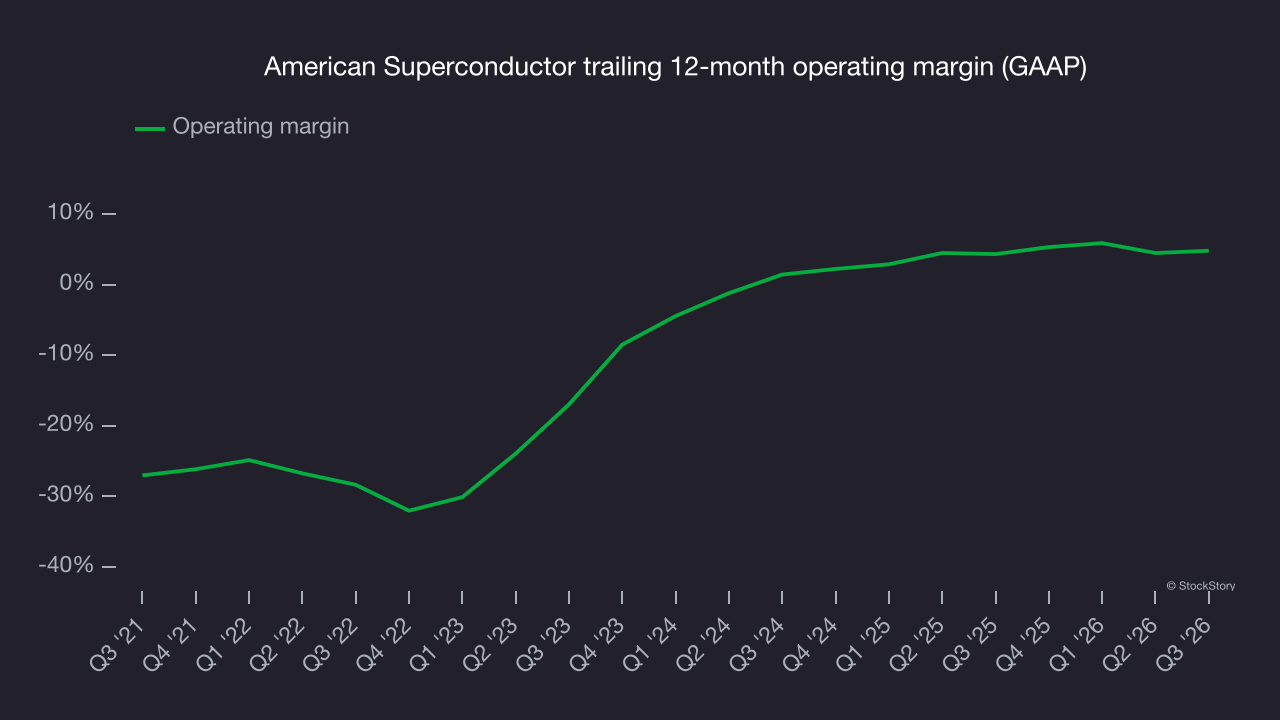
This quarter, American Superconductor generated an operating margin of 5.7%, up 1.2 percentage points year on year. The increase was a positive sign. Given that its gross margin decreased, the improvement suggests greater efficiency as operating expenses, including marketing costs, research and development spending and administrative overhead, grew more slowly than revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
American Superconductor’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
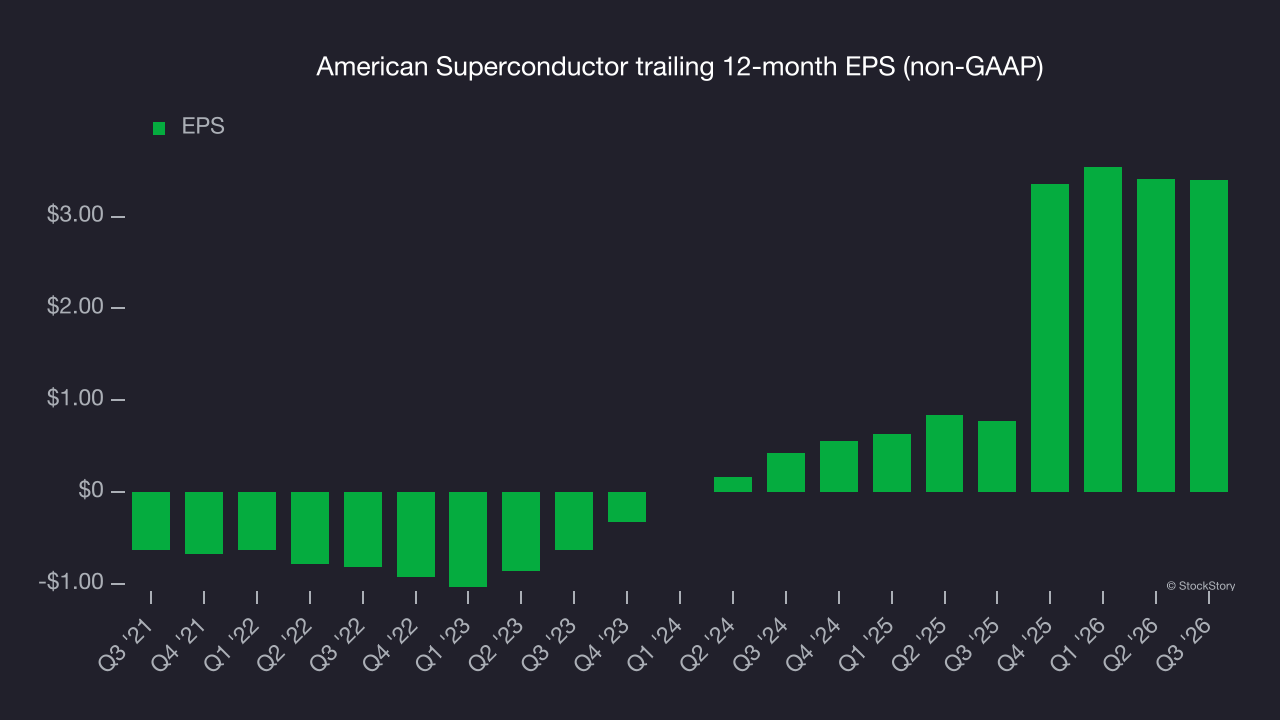
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
American Superconductor’s EPS grew at a 181% compounded annual growth rate over the last two years, higher than its 40.8% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
In Q3, American Superconductor reported adjusted EPS of $0.19, down from $0.20 in the same quarter last year. This result missed analysts’ consensus estimates, but long-term adjusted EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects American Superconductor’s full-year EPS to shrink by 65.5% from $3.40 to $1.17, according to S&P.
Key takeaways from American Superconductor’s Q3 results
American Superconductor’s sizable revenue beat was a positive, but EPS fell short of expectations, making for a mixed quarter overall. Shares rose 3% to $27.08 immediately after the results.
To assess American Superconductor at its current price, consider the bigger picture of valuation and business quality, as well as the latest earnings. Read the full research report here (it’s free).