Global media and publishing company News Corp (NASDAQ: NWSA) met Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), with revenue up 6.4% year on year to $2.28 billion. Its non-GAAP profit of $0.28 per share was 7.7% above analysts’ consensus estimates.
For more on News Corp, read our full research report for free.
News Corp (NWSA) Q3 CY2026 highlights:
- Revenue $2.28 billion vs S&P analysts’ consensus estimates of $2.27 billion (6.4% year-on-year growth, in line)
- Adjusted EPS $0.28 vs S&P analysts’ consensus estimates of $0.26 (7.7% beat)
- Adjusted EBITDA $392 million vs analysts’ consensus estimates of $391 million (17.2% margin, in line)
- Free cash flow -$89 million, down from $4 million in the same quarter last year
- Market capitalization $16.29 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. News Corp struggled to consistently generate demand over the last five years as its revenue dropped at a 1.2% annual rate. This fell short of our standards and points to poor business quality.
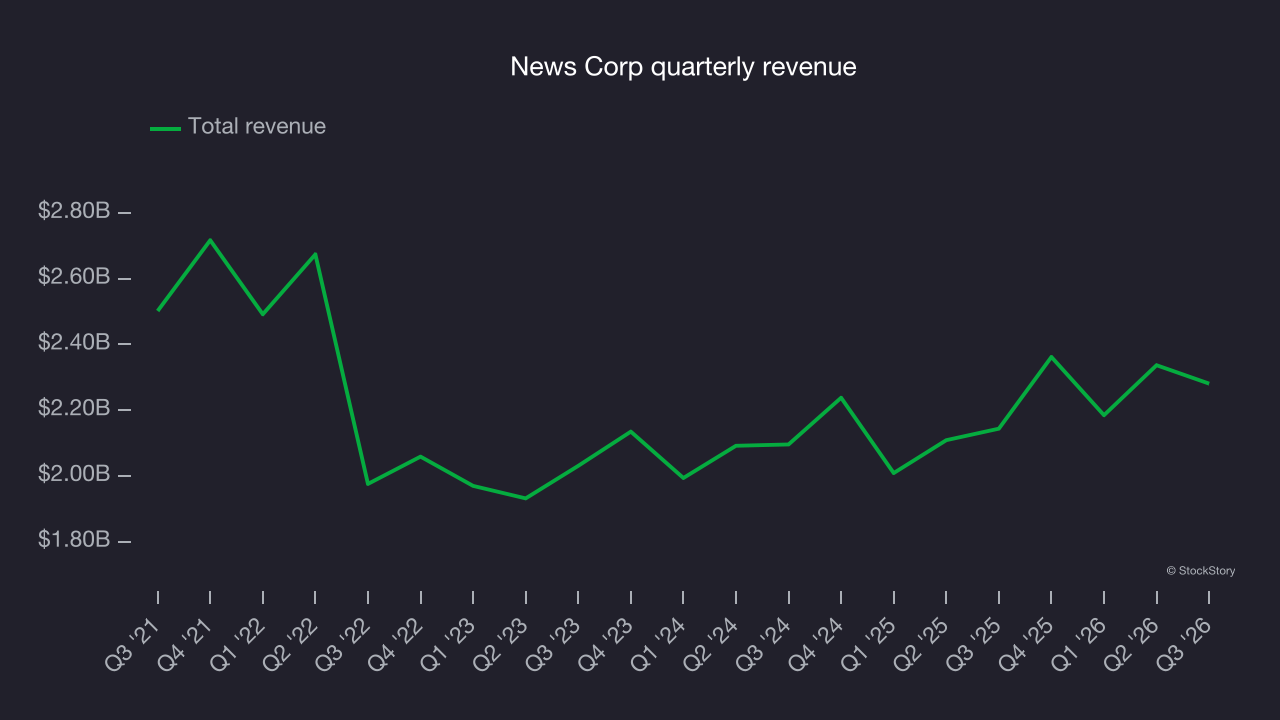
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. News Corp’s annualized revenue growth of 5% over the last two years is above its five-year trend, a positive sign. 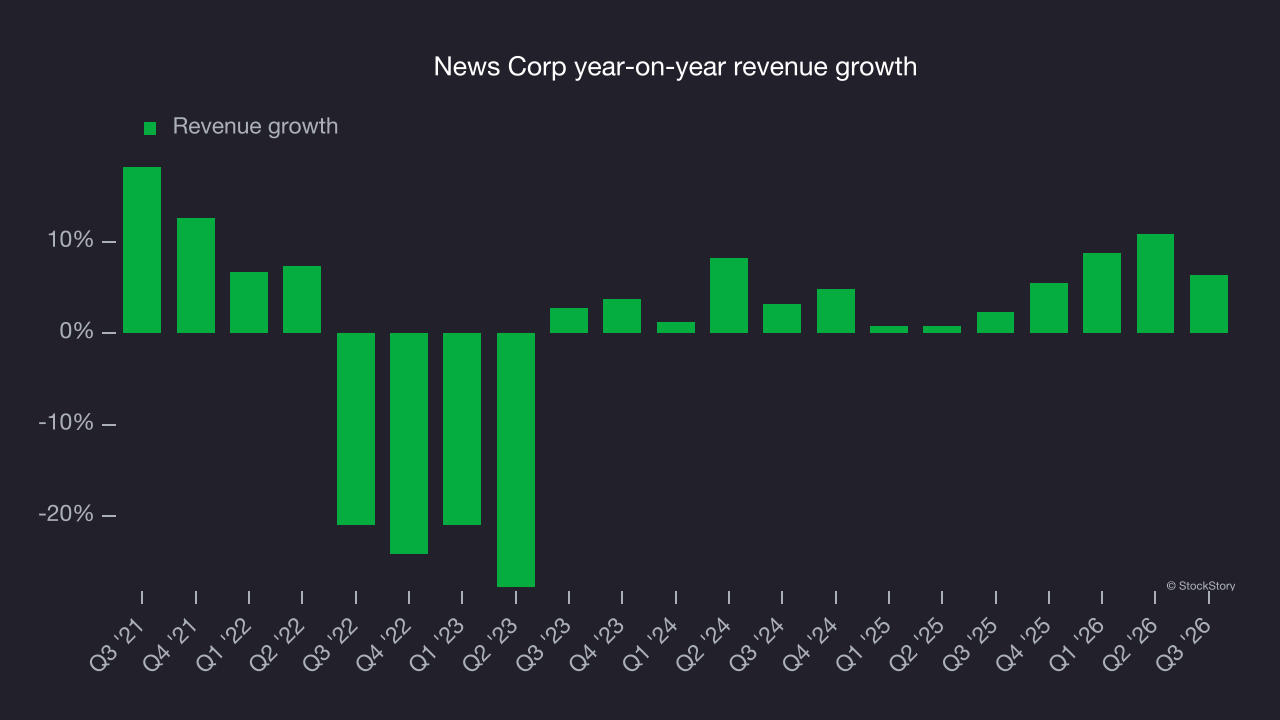
The company’s three most important segments are Dow Jones, News Media and Book Publishing, which account for 27.6%, 23.2% and 25.5% of revenue. Over the last two years, News Corp’s Dow Jones (media subsidiary) and News Media (general media) revenues averaged year-on-year growth of 6.3% and 1.8% while its Book Publishing revenue (general publishing) was flat. 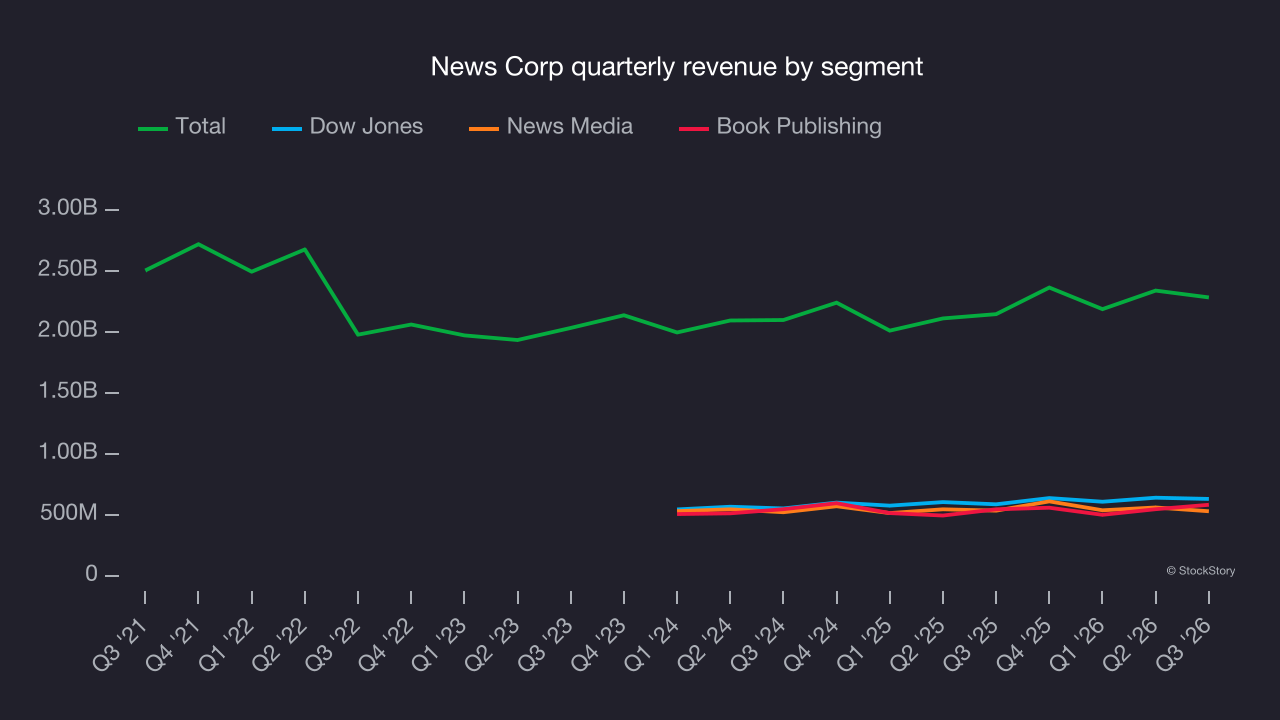
This quarter, News Corp grew its revenue by 6.4% year on year, and its $2.28 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 4.2% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and suggests its newer products and services will not lead to better top-line performance yet.
Operating margin
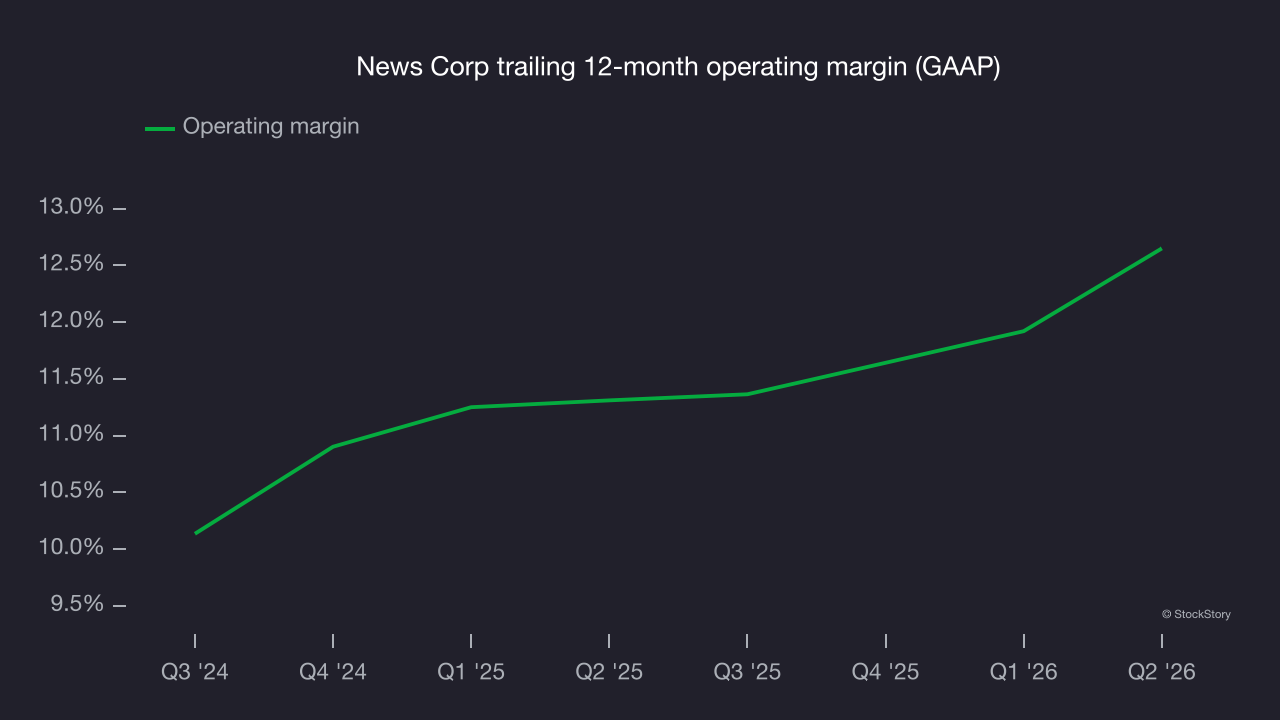
in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
News Corp’s EPS grew at an 8.6% compounded annual growth rate over the last five years. This performance was better than its 1.2% annualized revenue declines but doesn’t tell us much about its business quality because its operating margin didn’t improve.
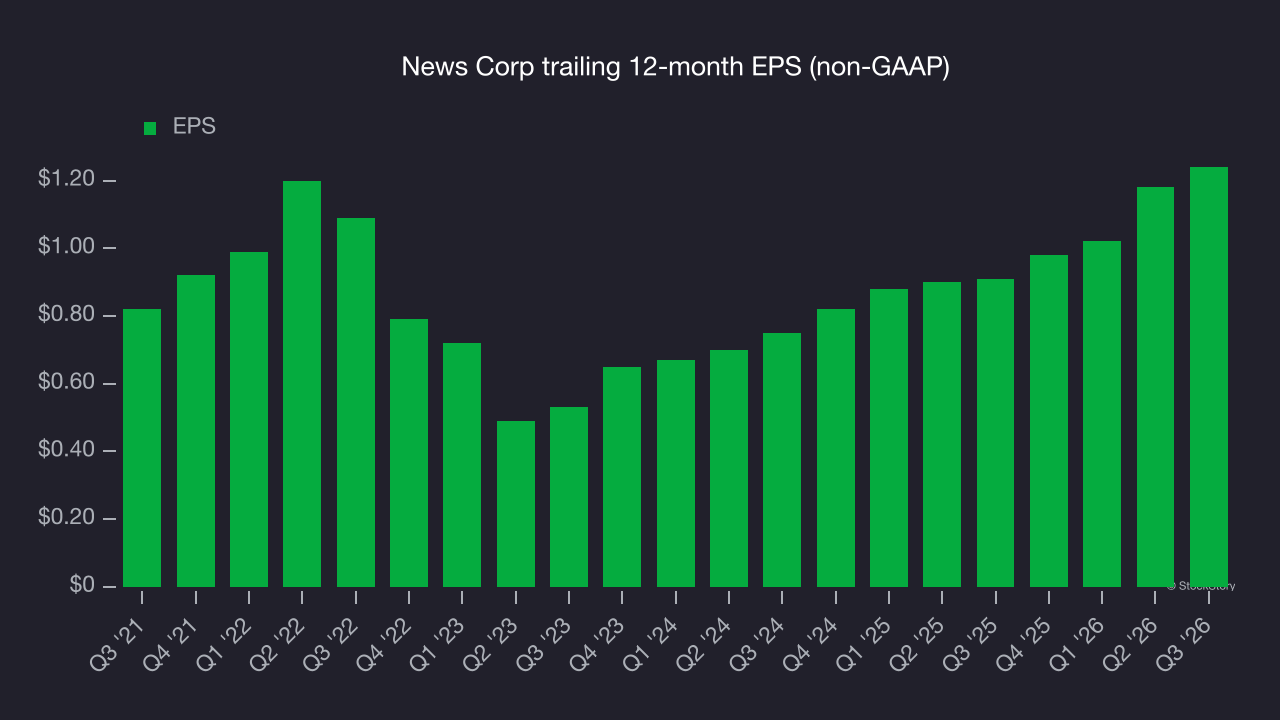
In Q3, News Corp reported adjusted EPS of $0.28, up from $0.22 in the same quarter last year. This result beat analysts’ consensus estimates by 7.7%. Over the next 12 months, Wall Street expects News Corp’s full-year EPS to grow 12.8% from $1.24 to $1.40, according to S&P.
Key takeaways from News Corp’s Q3 results
News Corp’s EPS beat analysts’ consensus estimates, a key positive in a quarter with some encouraging results. Shares remained flat at $30.53 immediately after the release.
Assessing whether News Corp is a buy at its current price requires a longer-term view. The latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. For more on News Corp, read the full research report here (it’s free).