Household products company Reynolds (NASDAQ: REYN) announced better-than-expected revenue in Q3 2026, with revenue up 1.4% year on year to $944 million. On the other hand, next quarter’s revenue guidance of $1.03 billion was less impressive, coming in 0.9% below analysts’ consensus estimates. Its non-GAAP profit of $0.39 per share was in line with analysts’ consensus estimates.
For more on Reynolds, read our free full research report.
Reynolds (REYN) Q3 2026 highlights:
- Revenue $944 million vs S&P analysts’ consensus estimates of $934.9 million (1.4% year-on-year growth, 1% beat)
- Adjusted EPS $0.39 vs S&P analysts’ consensus estimates of $0.38 (in line)
- Adjusted EBITDA $163 million vs analysts’ consensus estimates of $162.2 million (17.3% margin, in line)
- Revenue guidance $1.03 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.04 billion
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $1.60 at the midpoint
- EBITDA guidance $667.5 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 10.4%, down from 13.2% in the same quarter last year
- Free cash flow margin 1%, down from 5.2% in the same quarter last year
- Market capitalization $5.08 billion
“We delivered a solid third quarter in a volatile operating environment, acting decisively to address significant commodity inflation and delivering earnings in-line with our guidance,” said Scott Huckins, President and Chief Executive Officer. “We made further progress on our productivity initiatives, allowing us to continue investing behind our brands, innovation and other strategic initiatives. Disciplined execution remains critical as we navigate the balance of the year, and we remain focused on delivering against our full-year 2026 outlook and establishing a strong foundation for future growth.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $3.80 billion in revenue over the past 12 months, Reynolds carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
Reynolds struggled to increase demand as its $3.80 billion in revenue for the trailing 12 months was close to its revenue three years ago. This is mainly because it failed to grow its volumes.
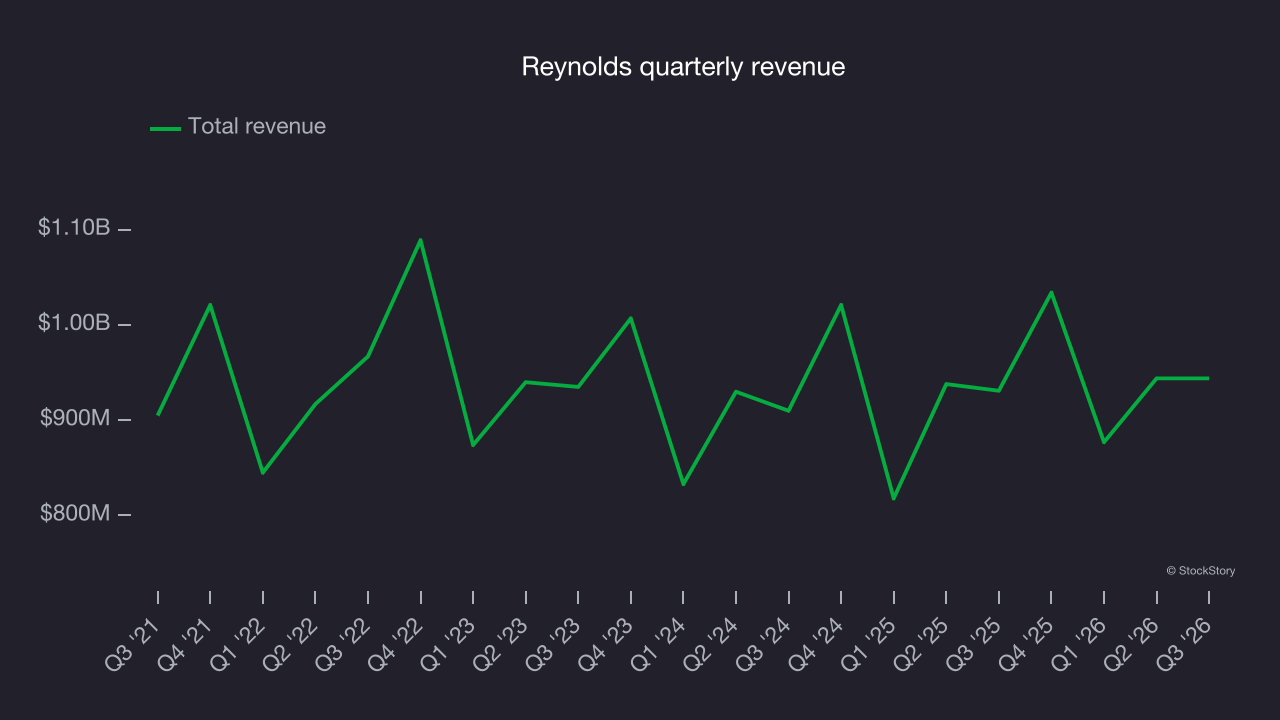
This quarter, Reynolds reported modest year-on-year revenue growth of 1.4% but beat Wall Street’s consensus estimates by 1%. Management is guiding for flat revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 1.2% over the next 12 months, according to S&P. While this projection implies its newer products will spur better top-line performance, it is still below the sector average.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it difficult to manipulate.
Reynolds has shown impressive cash profitability, giving it the option to reinvest or return capital to investors. The company’s free cash flow margin averaged 7.2% over the last two years, better than the broader consumer staples sector.
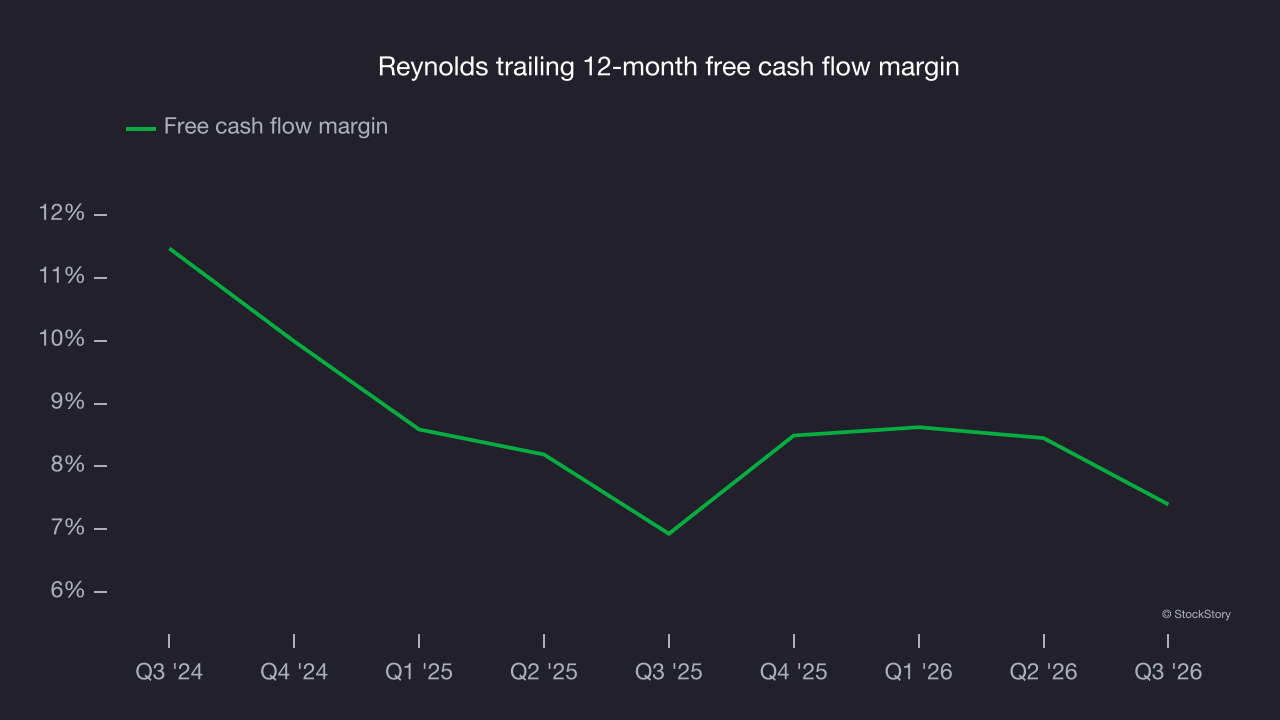
Reynolds broke even from a free cash flow perspective in Q3. The company’s cash profitability regressed as it was 4.2 percentage points lower than in the same quarter last year. This warrants extra attention because consumer staples companies typically produce more consistent and defensive performance.
Key takeaways from Reynolds’s Q3 results
Reynolds delivered a decent quarter, with gross margin above analysts’ consensus estimates and revenue narrowly ahead of Wall Street’s consensus. Shares remained flat at $24.09 immediately after the results.
How does Reynolds look at its current price? The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Reynolds, read the full research report here (it’s free).