
Although Powell (currently trading at $183.30 per share) has gained 5.3% over the last six months, it has trailed the S&P 500’s 12.9% return during that period. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Taking into account the weaker price action, is now a good time to buy POWL, or is it a pass? Find out in our full research report, it’s free.
Why Is POWL a Good Business?
Originally a metal-working shop supporting local petrochemical facilities, Powell (NYSE: POWL) has grown from a small Houston manufacturer to a global provider of electrical systems.
1. Skyrocketing Revenue Shows Strong Momentum
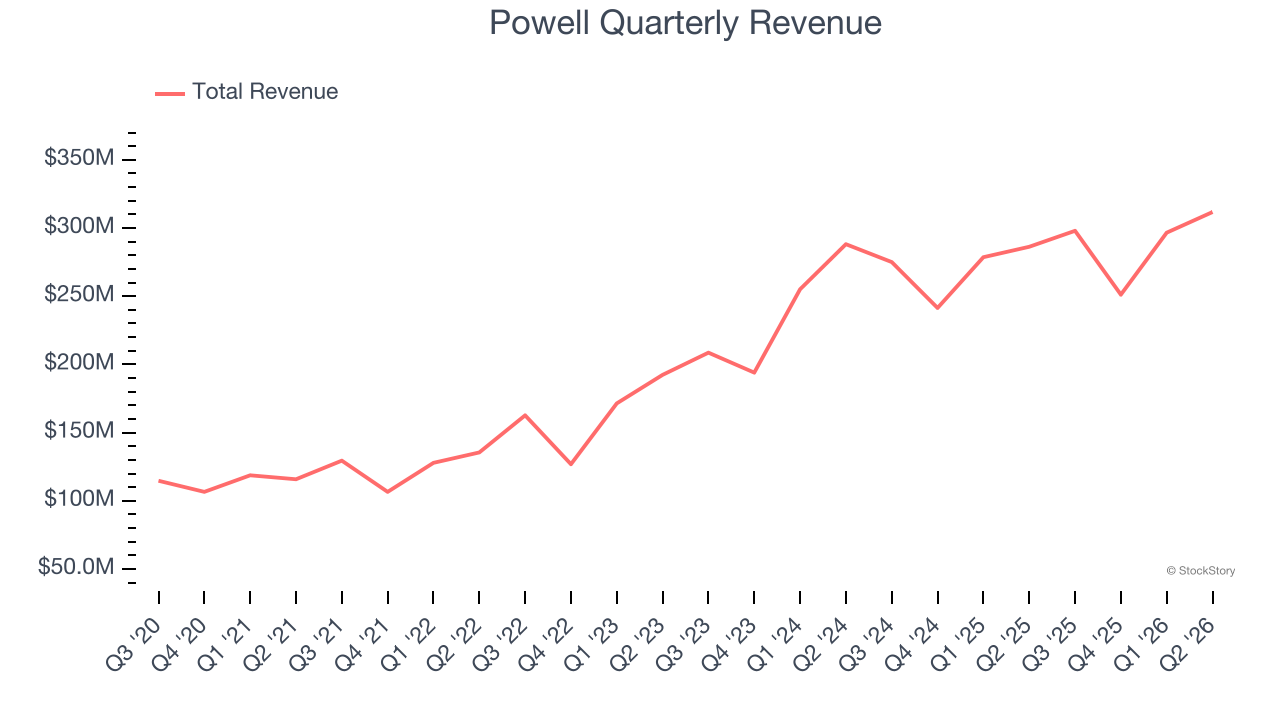
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Luckily, Powell’s sales grew at an incredible 20.5% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
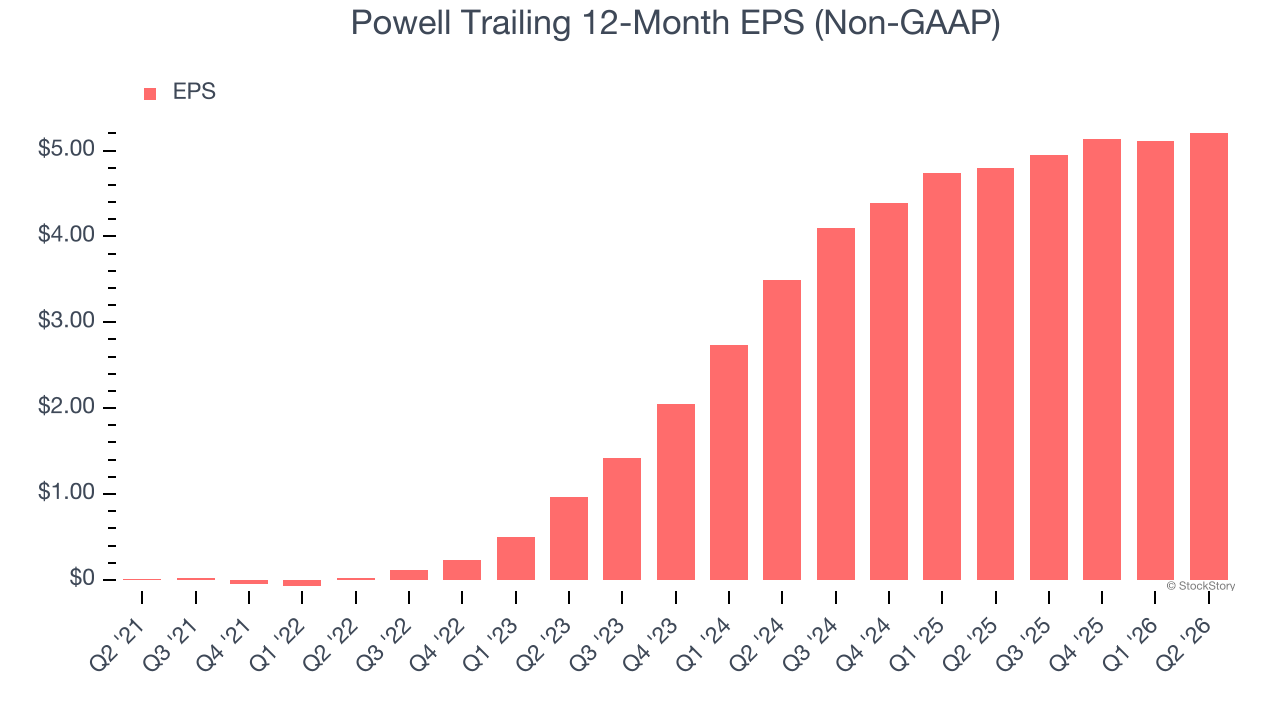
Powell’s EPS grew at 250% compounded annual growth rate over the last five years, higher than its 20.5% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
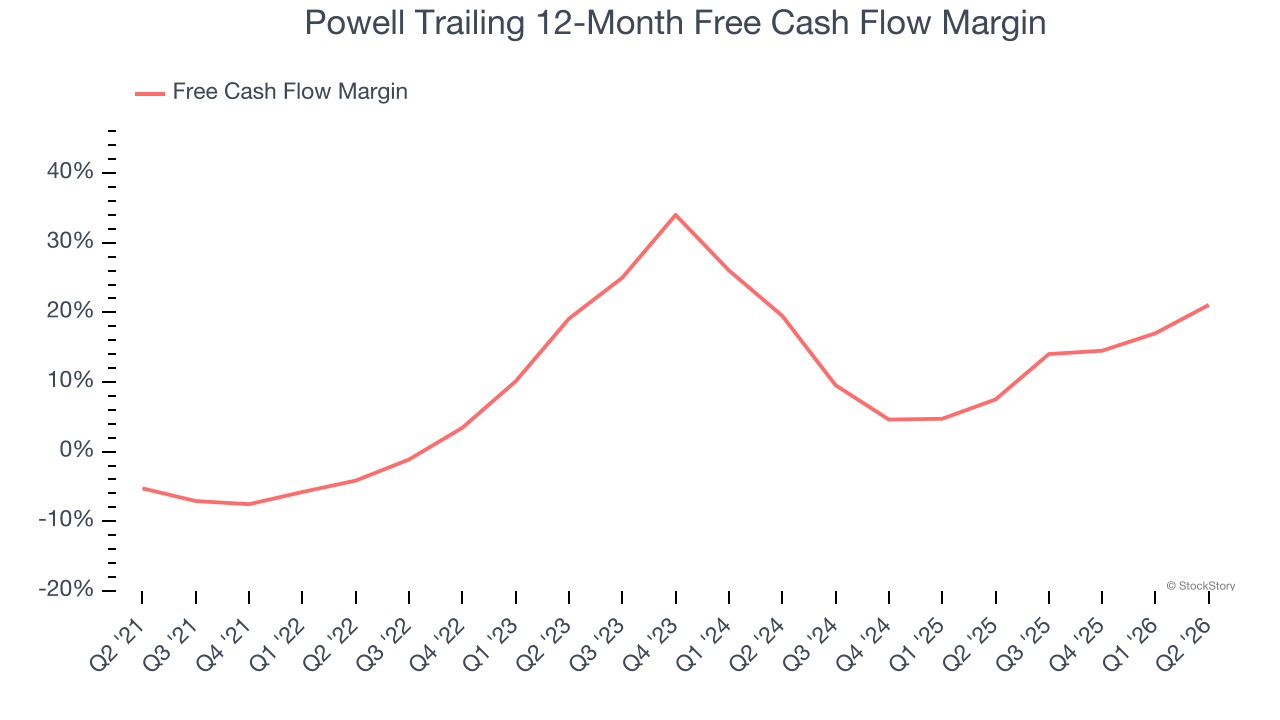
3. Increasing Free Cash Flow Margin Juices Financials
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Powell’s margin expanded by 25.2 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Powell’s free cash flow margin for the trailing 12 months was 21.1%.
Final Judgment
These are just a few reasons why Powell is a cream-of-the-crop industrials company. With its shares trailing the market in recent months, the stock trades at 26.6× forward P/E (or $183.30 per share). Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.