
Restaurant company Cracker Barrel (NASDAQ: CBRL) will be reporting earnings this Wednesday before the bell. Here’s what to expect.
Cracker Barrel beat analysts’ revenue expectations last quarter, reporting revenues of $797.4 million, down 2.9% year on year. It was a stunning quarter for the company, with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
Is Cracker Barrel a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Cracker Barrel’s revenue to decline 3.6% year on year, in line with the 2.9% decrease it recorded in the same quarter last year.
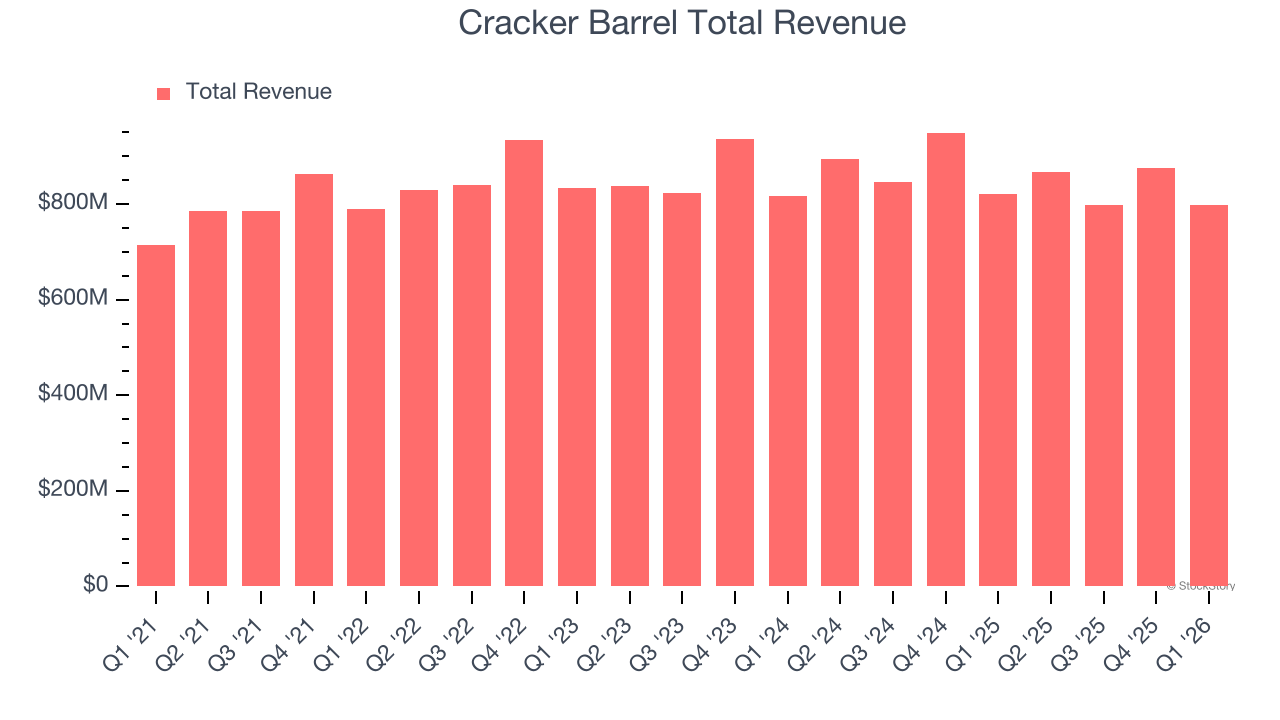
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Cracker Barrel has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Cracker Barrel’s peers in the restaurants segment, some have already reported their Q2 results, giving us a hint as to what we can expect. Brinker International delivered year-on-year revenue growth of 5.1%, meeting analysts’ expectations, and CAVA reported revenues up 31.3%, topping estimates by 2.4%. Brinker International traded up 7.8% following the results while CAVA was also up 14.2%.
Read our full analysis of Brinker International’s results here and CAVA’s results here.
In the last year or so, investors have shifted their focus from one macro dynamic to the next (AI disintermediation and AI investment to geopolitical conflict, interest rates, and the health of the wider economy). Investors in restaurants stocks haven’t been spared in this environment as share prices are down 16.8% on average over the last month. Cracker Barrel is down 22.6% during the same time and is heading into earnings with an average analyst price target of $46.13 (compared to the current share price of $44.89).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.