Financial services company Truist Financial (NYSE: TFC) fell short of the market’s revenue expectations in Q3 2026 as sales only rose 1.2% year on year to $5.3 billion. Its non-GAAP profit of $1.16 per share was 0.9% below analysts’ consensus estimates.
Is now the time to buy Truist Financial? Find out by accessing our full research report, it’s free.
Truist Financial (TFC) Q3 2026 Highlights:
- Net Interest Income: $3.71 billion vs analyst estimates of $3.7 billion (flat year on year, in line)
- Net Interest Margin: 3% vs analyst estimates of 3% (in line)
- Revenue: $5.3 billion vs analyst estimates of $5.36 billion (1.2% year-on-year growth, 1.1% miss)
- Efficiency Ratio: 82.9% vs analyst estimates of 58% (2,488.7 basis point miss)
- Adjusted EPS: $1.16 vs analyst expectations of $1.17 (0.9% miss)
- Tangible Book Value per Share: $31.90 vs analyst estimates of $33.27 (1.2% year-on-year decline, 4.1% miss)
- Market Capitalization: $56.89 billion
Company Overview
Born from the 2019 merger of BB&T and SunTrust in one of the largest banking combinations since the 2008 financial crisis, Truist Financial (NYSE: TFC) is a bank holding company that offers a wide range of financial services including consumer and commercial banking, wealth management, insurance, and lending solutions.
Sales Growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Over the last five years, Truist Financial’s demand was weak and its revenue declined by 1.3% per year. This wasn’t a great result and is a sign of poor business quality.
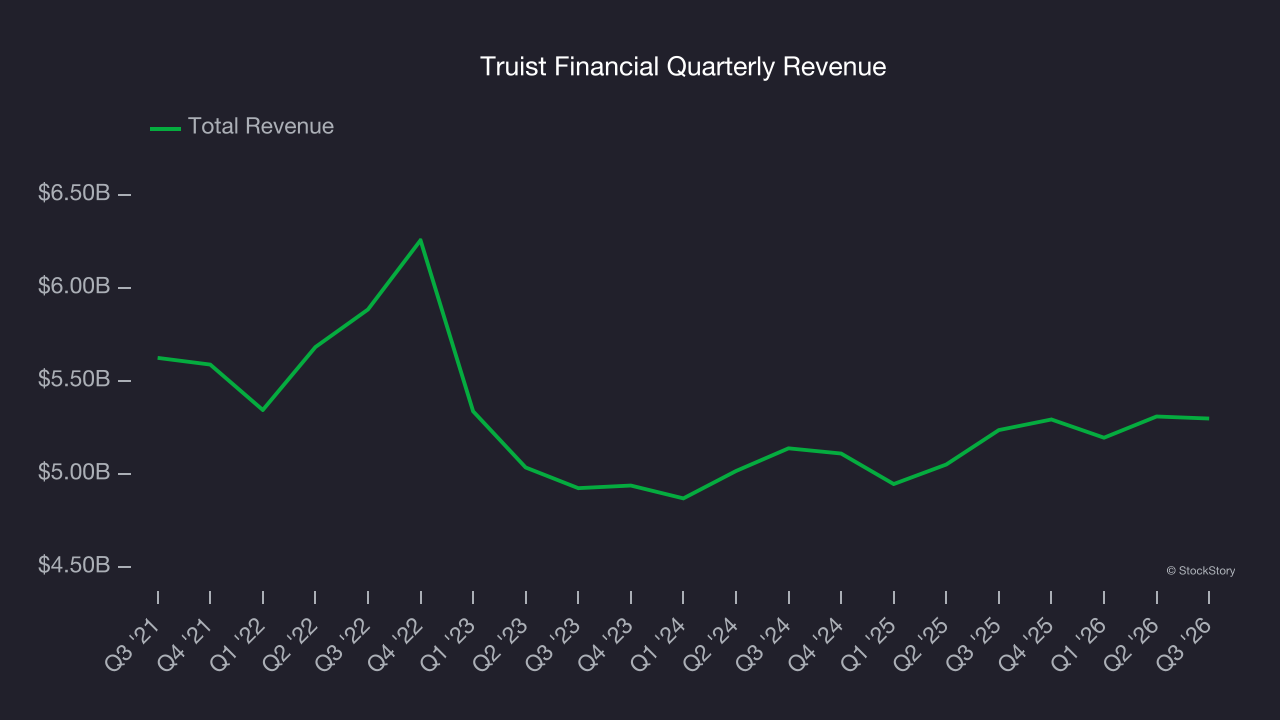
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Truist Financial’s annualized revenue growth of 2.8% over the last two years is above its five-year trend, which is encouraging. 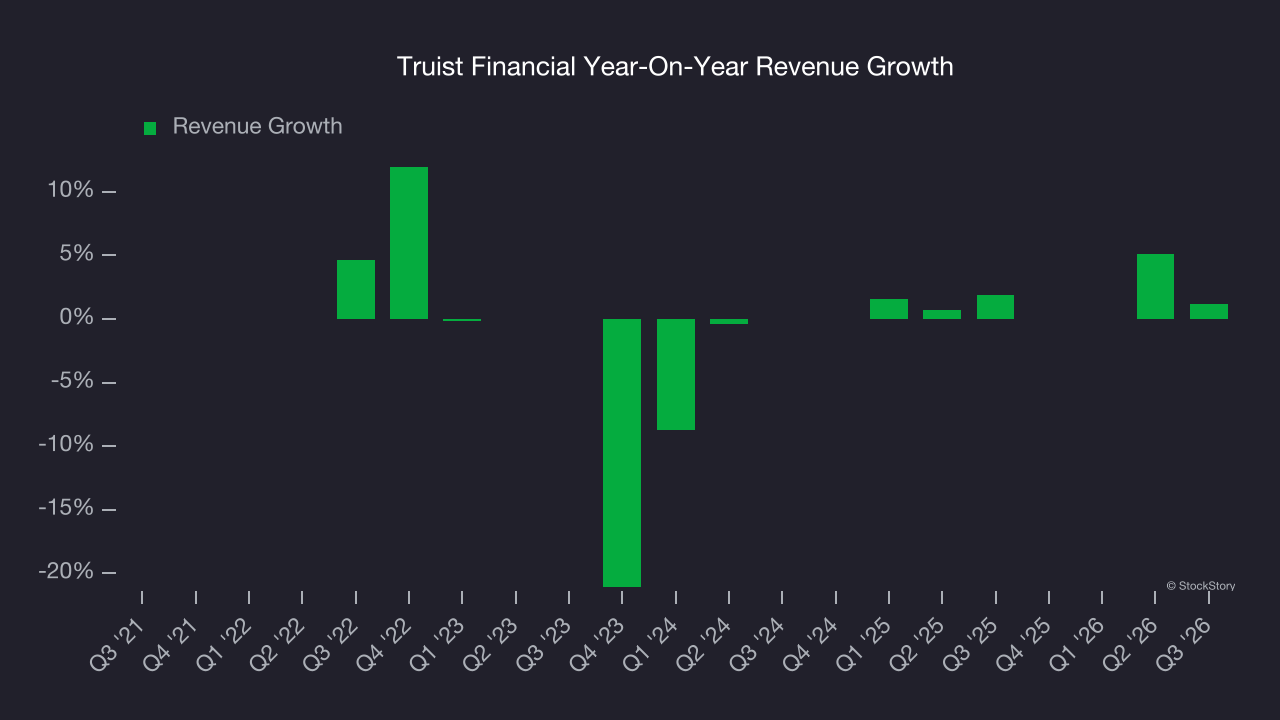 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Truist Financial’s revenue grew by 1.2% year on year to $5.3 billion, falling short of Wall Street’s estimates.
Net interest income made up 73.4% of the company’s total revenue during the last five years, meaning lending operations are Truist Financial’s largest source of revenue.
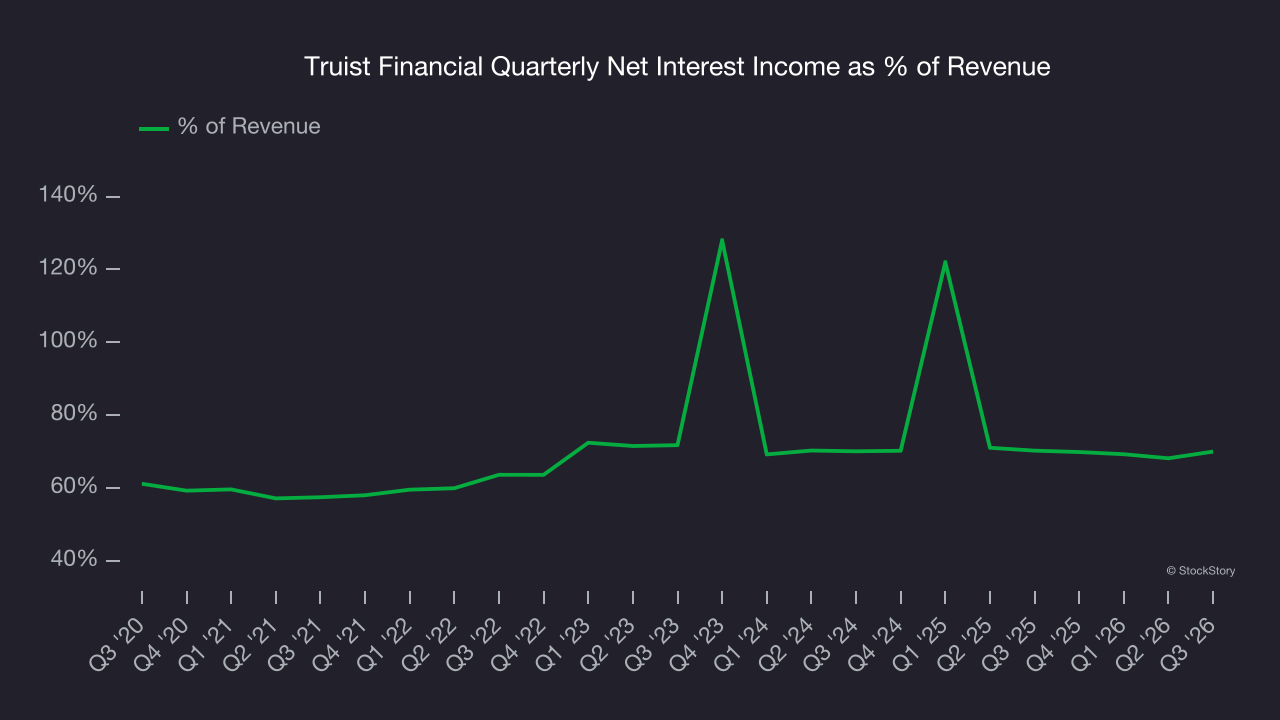
Net interest income commands greater market attention due to its reliability and consistency, whereas non-interest income is often seen as lower-quality revenue that lacks the same dependable characteristics.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible Book Value Per Share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This explains why tangible book value per share (TBVPS) stands as the premier banking metric. TBVPS strips away questionable intangible assets, revealing concrete per-share net worth that investors can trust. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
Truist Financial’s TBVPS grew at a mediocre 4.4% annual clip over the last five years. TBVPS growth has also recently decelerated a bit to 2.6% annual growth over the last two years (from $30.33 to $31.90 per share).
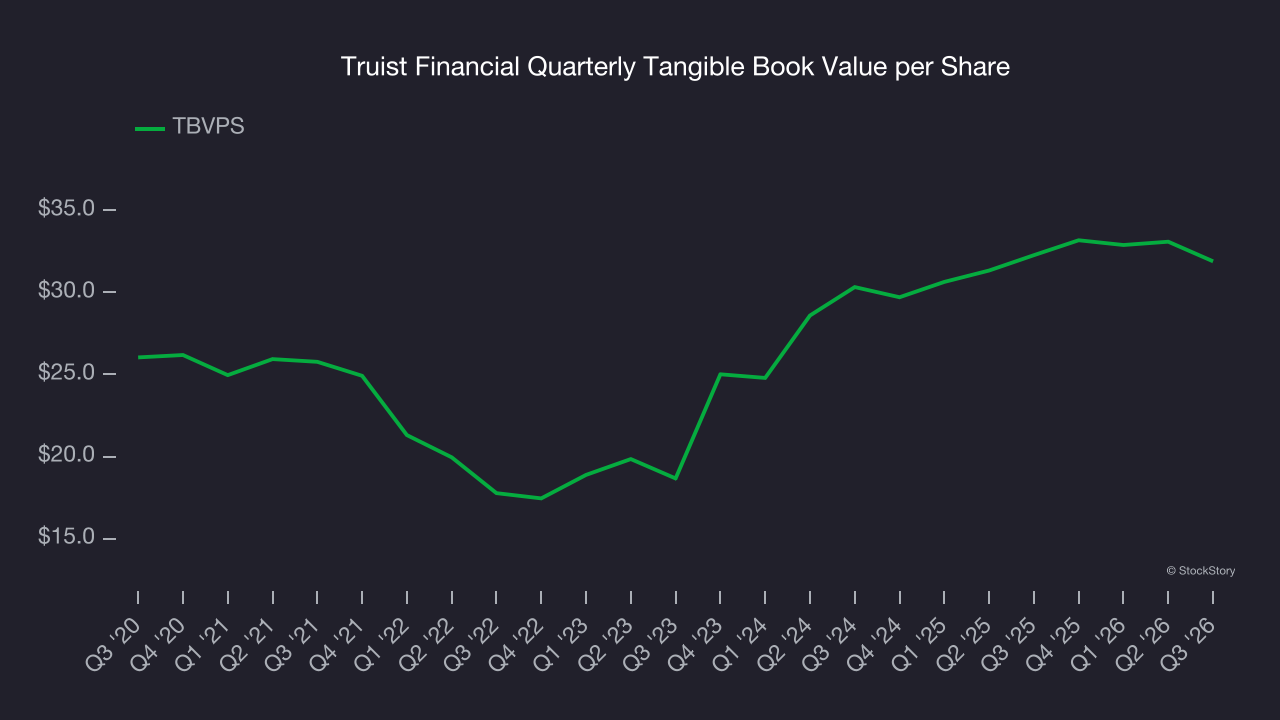
Over the next 12 months, Consensus estimates call for Truist Financial’s TBVPS to grow by 12.3% to $35.82, mediocre growth rate.
Key Takeaways from Truist Financial’s Q3 Results
Net interest income and net interest margin were both in line. On the negative side, tangible book value per share missed and EPS fell a bit short of Wall Street’s estimates. Overall, this was a softer quarter. The stock remained flat at $46.40 immediately following the results.
Truist Financial underperformed this quarter, but does that create an opportunity to invest right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).