Railway infrastructure company L.B. Foster (NASDAQ: FSTR) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 21.5% year on year to $168 million. The company’s full-year revenue guidance of $580 million at the midpoint came in 3.1% above analysts’ consensus estimates. Its GAAP profit of $0.64 per share was 6.7% above analysts’ consensus estimates.
For more on L.B. Foster, read our free full research report.
L.B. Foster (FSTR) Q3 2026 highlights:
- Revenue $168 million vs S&P analysts’ consensus estimates of $152.2 million (21.5% year-on-year growth, 10.4% beat)
- EPS (GAAP) $0.64 vs analysts’ consensus estimates of $0.60 (6.7% beat)
- Adjusted EBITDA $13.08 million vs analysts’ consensus estimates of $12.92 million (7.8% margin, 1.2% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $580 million at the midpoint from $560 million, a 3.6% increase
- EBITDA guidance $43.5 million at the midpoint for the full year, above analysts’ consensus estimates of $42.36 million
- Operating margin 6%, in line with the same quarter last year
- Free cash flow margin 12.4%, down from 19.1% in the same quarter last year
- Backlog $234.7 million at quarter end, down 5.1% year on year
- Market capitalization $383.6 million
John Kasel, President and Chief Executive Officer, commented, "We started the second half of the year with strong momentum, delivering meaningful growth in sales, profitability, and cash generation during the third quarter. Sales increased 21.5% over the prior year quarter, reflecting strong growth across both segments, while Adjusted EBITDA1 increased 15.1%. Gross profit expanded $3.4 million during the quarter despite a decline in gross margin of 200 bps to 20.5%. The margin decrease was primarily attributable to business mix within Rail, Technologies, and Services ("Rail"), reflecting stronger sales growth in the lower-margin Rail Distribution and UK businesses. Additionally, selling and administrative expense as a percentage of sales declined 190 bps to 14.1% reflecting continued operating discipline and sales growth. On a year-to-date basis, we are pleased with our sales growth of $48.1 million or 12.7% with growth occurring in both segments. This growth helped drive a $4.5 million, or 17.6%, expansion in Adjusted EBITDA1 over the prior year."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Over the last five years, L.B. Foster grew its revenue at a sluggish 2.6% compounded annual growth rate, falling short of our benchmarks.
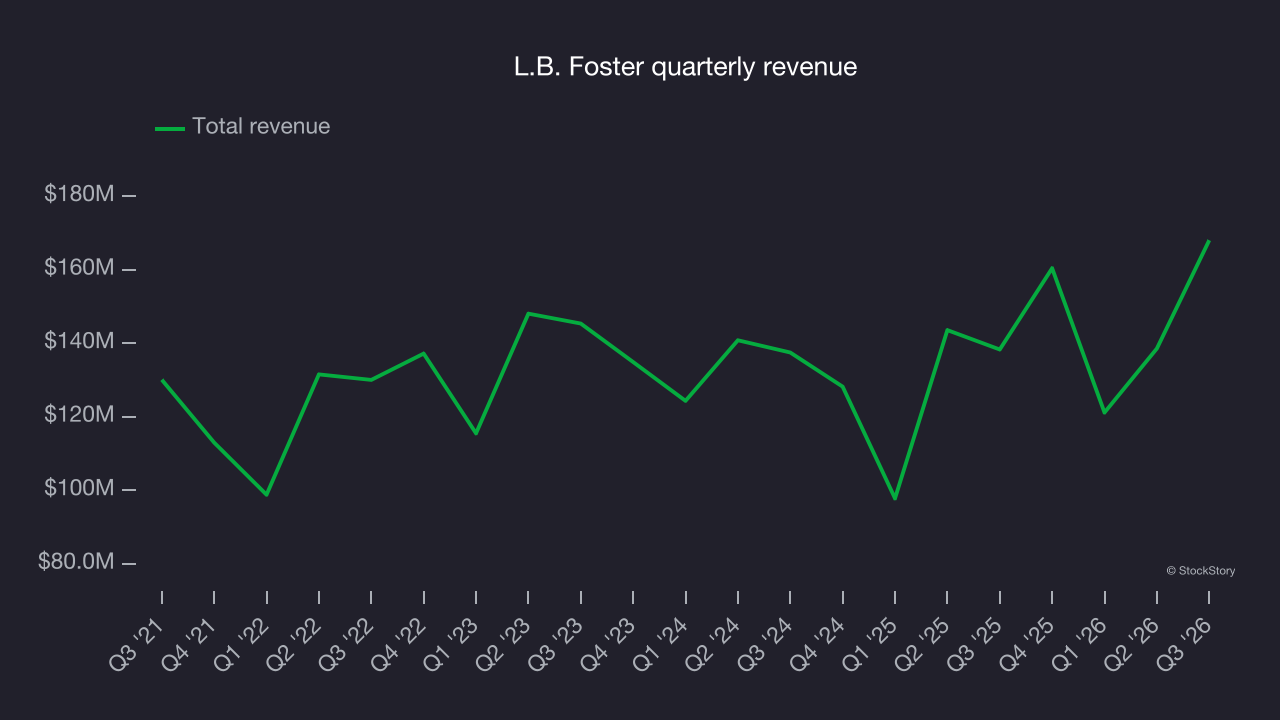
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. L.B. Foster’s annualized revenue growth of 4.6% over the last two years is above its five-year trend, a positive sign. 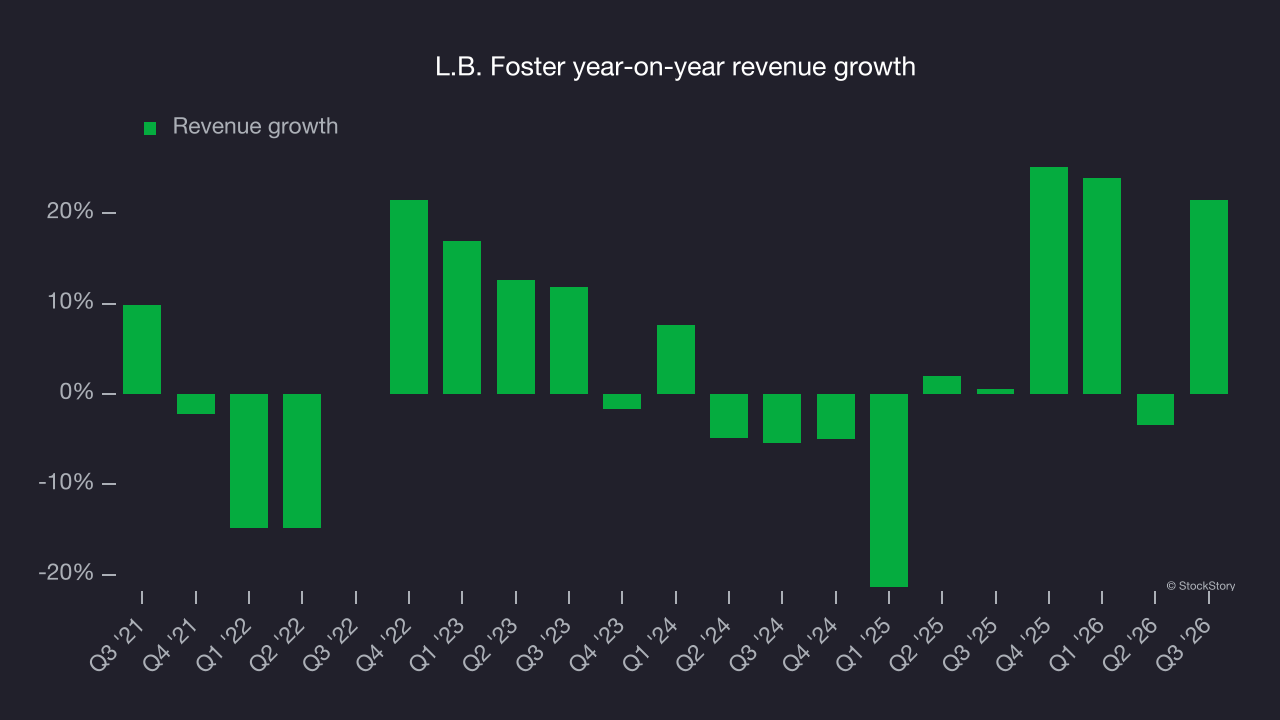
Analyzing the company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, helps explain its revenue dynamics. L.B. Foster’s backlog reached $234.7 million in the latest quarter and was flat over the last two years. Backlog growth trailed revenue growth, indicating the company hasn’t secured enough new orders to maintain its growth rate in the future. 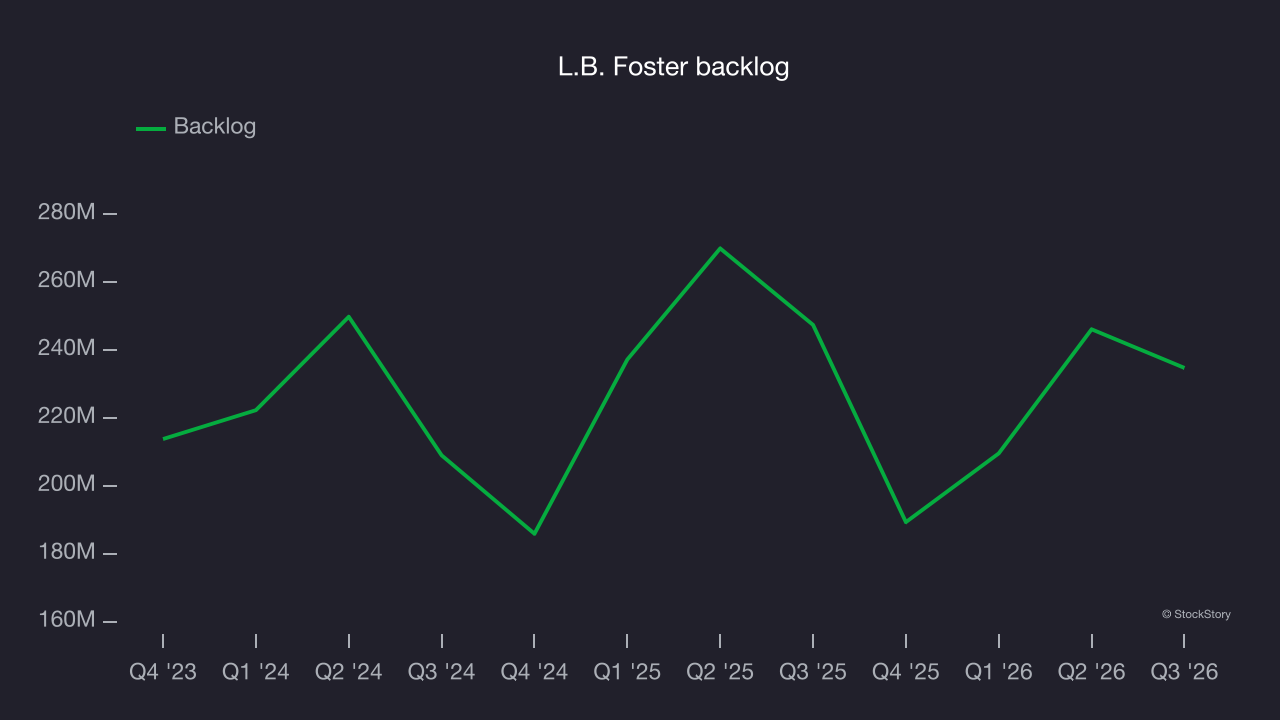
This quarter, L.B. Foster reported strong year-on-year revenue growth of 21.5%, and its $168 million of revenue topped Wall Street’s consensus estimates by 10.4%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will face some demand challenges.
Operating margin
L.B. Foster was profitable over the last five years but held back by its large cost base. Its average operating margin of 3% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, L.B. Foster’s operating margin rose by 5.4 percentage points over the last five years, as its revenue growth provided operating leverage.
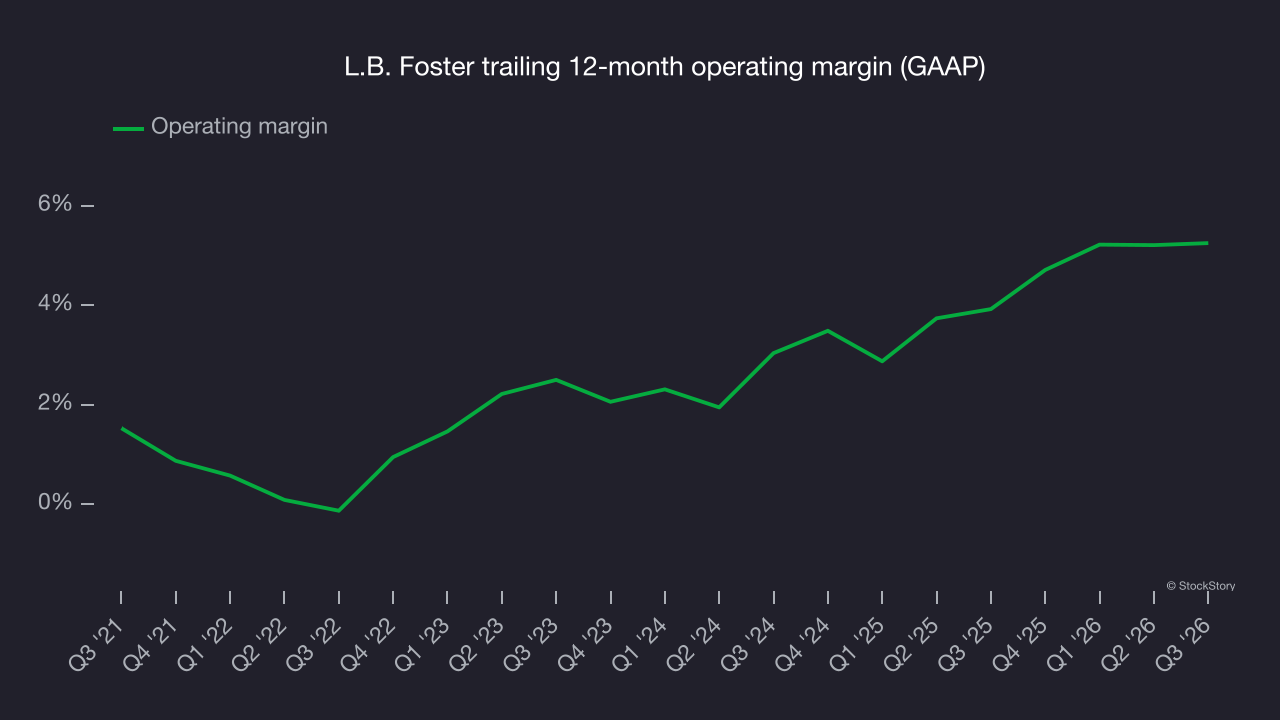
This quarter, L.B. Foster generated an operating margin of 6%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Long-term earnings per share, or EPS, growth matters for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
L.B. Foster’s EPS grew at a 17.7% compounded annual growth rate over the last five years, higher than its 2.6% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
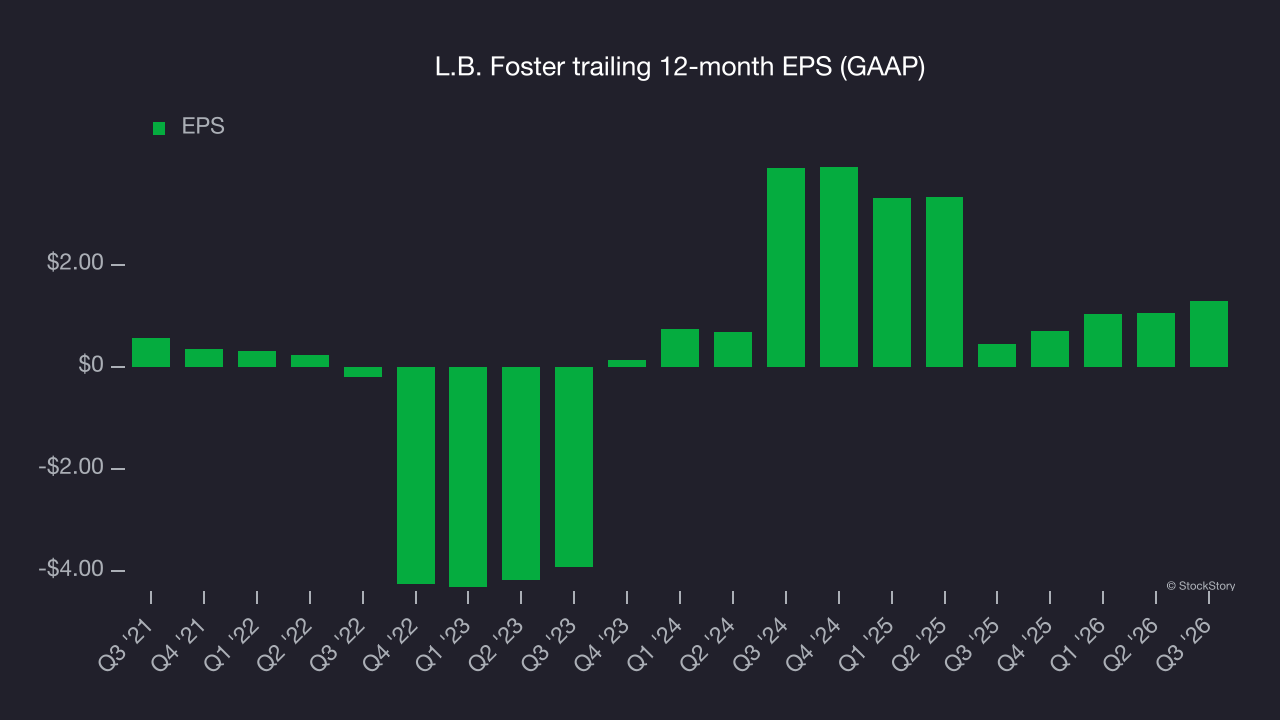
Examining L.B. Foster’s quality of earnings can provide a better understanding of its performance. As mentioned earlier, L.B. Foster’s operating margin was flat this quarter but expanded by 5.4 percentage points over the last five years. In addition, its share count shrank by 1.1%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 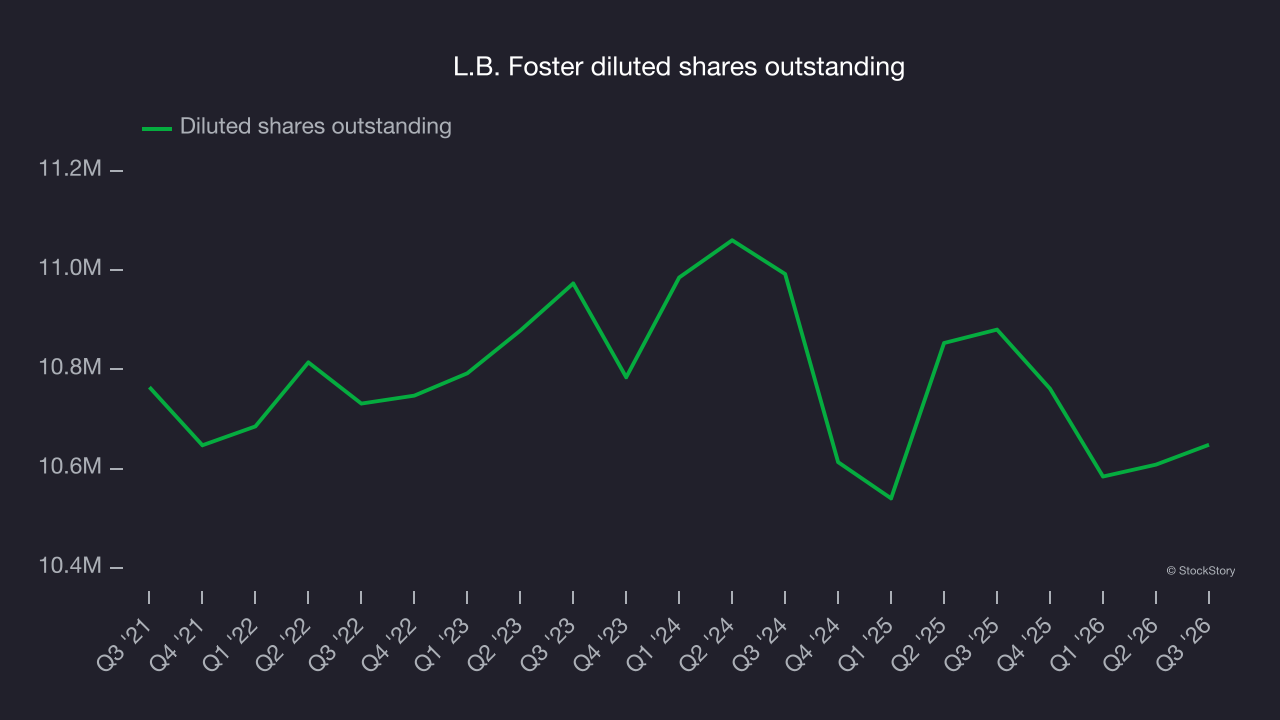
As with revenue, examining EPS over a shorter period can reveal changes in the business.
For L.B. Foster, its two-year annual EPS declines of 42.4% mark a reversal from its seemingly healthy five-year trend.
In Q3, L.B. Foster reported EPS of $0.64, up from $0.40 in the same quarter last year. This result beat analysts’ consensus estimates by 6.7%. Over the next 12 months, Wall Street expects L.B. Foster’s full-year EPS to grow 55.4% from $1.29 to $2.01, according to S&P.
Key takeaways from L.B. Foster’s Q3 results
L.B. Foster’s Q3 report had two important positives: Revenue beat analysts’ consensus estimates by a wide margin, and full-year revenue guidance topped Wall Street’s consensus. Shares rose 2.6% to $37.57 immediately after the results.
L.B. Foster had a solid quarterly earnings result, but is this stock a good investment? The latest quarter is only one part of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on those factors, read the full research report here (it’s free).