
eBay trades at $108.66 per share and has stayed right on track with the overall market, gaining 16.1% over the last six months. At the same time, the S&P 500 has returned 12.9%.
Is there a buying opportunity in eBay, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is eBay Not Exciting?
We don’t have much confidence in eBay. Here are three reasons you should be careful with EBAY, plus one stock we’d rather own.
1. Change in Active Buyers Points to Soft Demand
As an online marketplace, eBay generates revenue growth by increasing both the number of users on its platform and the average order size in dollars.
Over the last two years, eBay’s active buyers, a key performance metric for the company, increased by 1.3% annually to 136 million in the latest quarter. This growth rate is one of the lowest in the consumer internet sector, largely a function of its already massive scale and saturated market. If eBay wants to reaccelerate growth, it likely needs to innovate with new products. 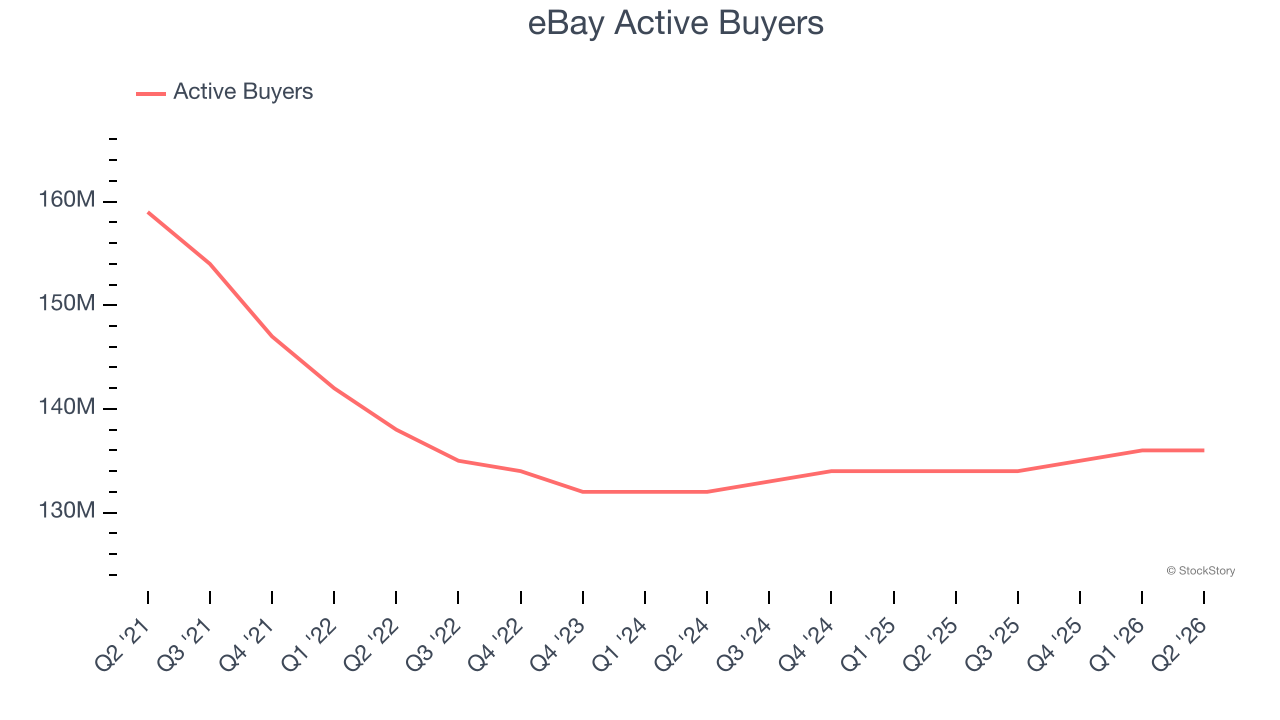
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect eBay’s revenue to rise by 7.8%, close to its 6.5% annualized growth for the past three years. This projection is underwhelming and suggests its newer products and services will not lead to better top-line performance yet.
3. Shrinking EBITDA Margin
Investors frequently analyze operating income to understand a business’s core profitability. Similar to operating income, EBITDA is a common profitability metric for consumer internet companies because it removes various one-time or non-cash expenses, offering a more normalized view of profit potential.
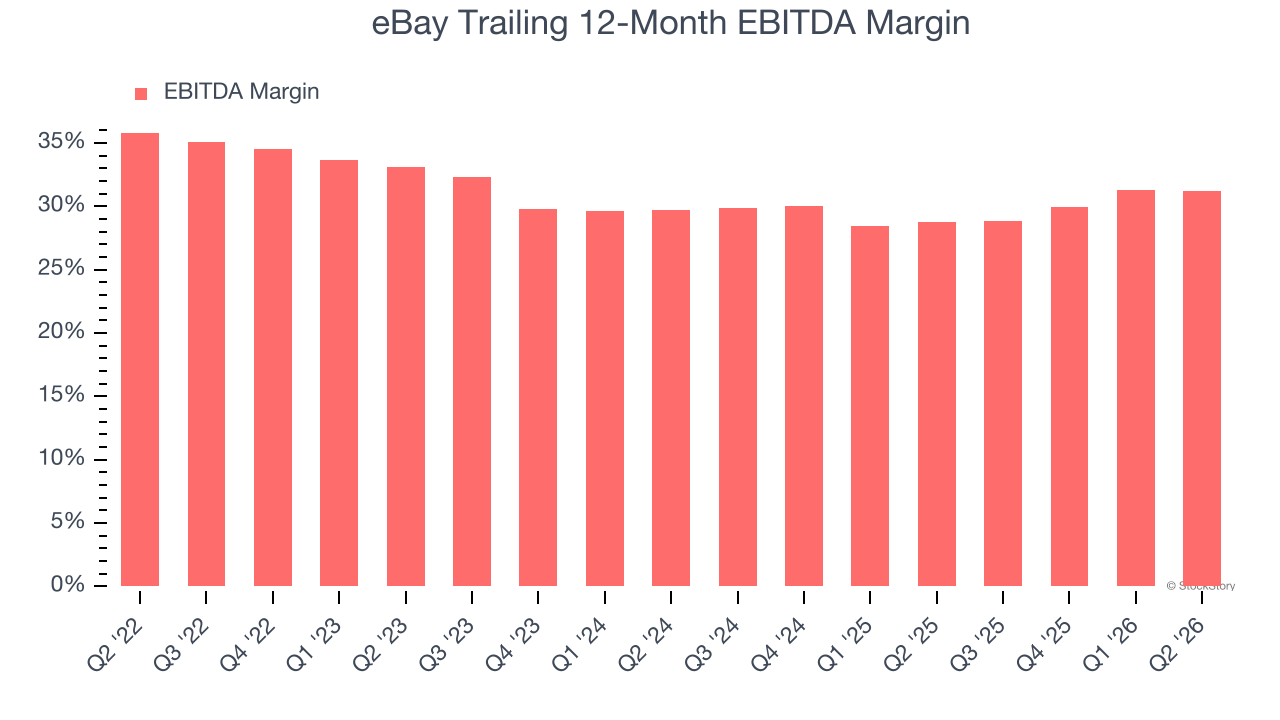
Analyzing the trend in its profitability, eBay’s EBITDA margin decreased by 1.9 percentage points over the last few years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its EBITDA margin for the trailing 12 months was 31.2%.
Final Judgment
eBay isn’t a terrible business, but it doesn’t pass our bar. That said, the stock currently trades at 13.7× forward EV/EBITDA (or $108.66 per share). This valuation tells us a lot of optimism is priced in - we think there are better stocks to buy right now. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of eBay
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.