
Permian Resources currently trades at $21.37 per share and has shown little upside over the past six months, posting a small loss of 0.6%. The stock also fell short of the S&P 500’s 21.4% gain during that period.
Is now the time to buy PR? Or does the price properly account for its business quality and fundamentals? Find out in our full research report, it’s free.
Why Are We Positive on PR?
Controlling roughly 450,000 net acres in America's most productive oil patch, Permian Resources (NYSE: PR) is an oil and natural gas producer that drills wells and extracts hydrocarbons from underground reservoirs in West Texas and New Mexico.
1. Skyrocketing Revenue Shows Strong Momentum
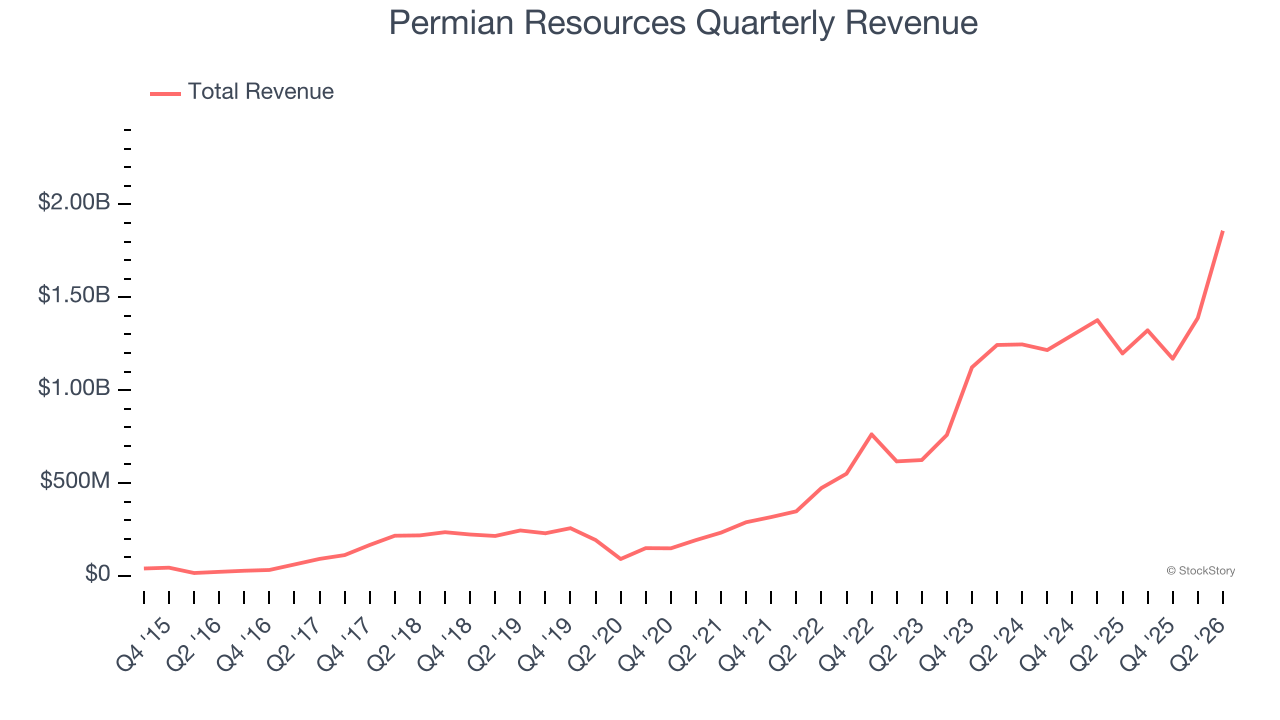
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can shine for a year or so, but a top-tier one should exhibit resilience through cycles. Over the last five years, Permian Resources grew its sales at an incredible 51.4% compounded annual growth rate. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Elite Gross Margin Powers Best-In-Class Business Model
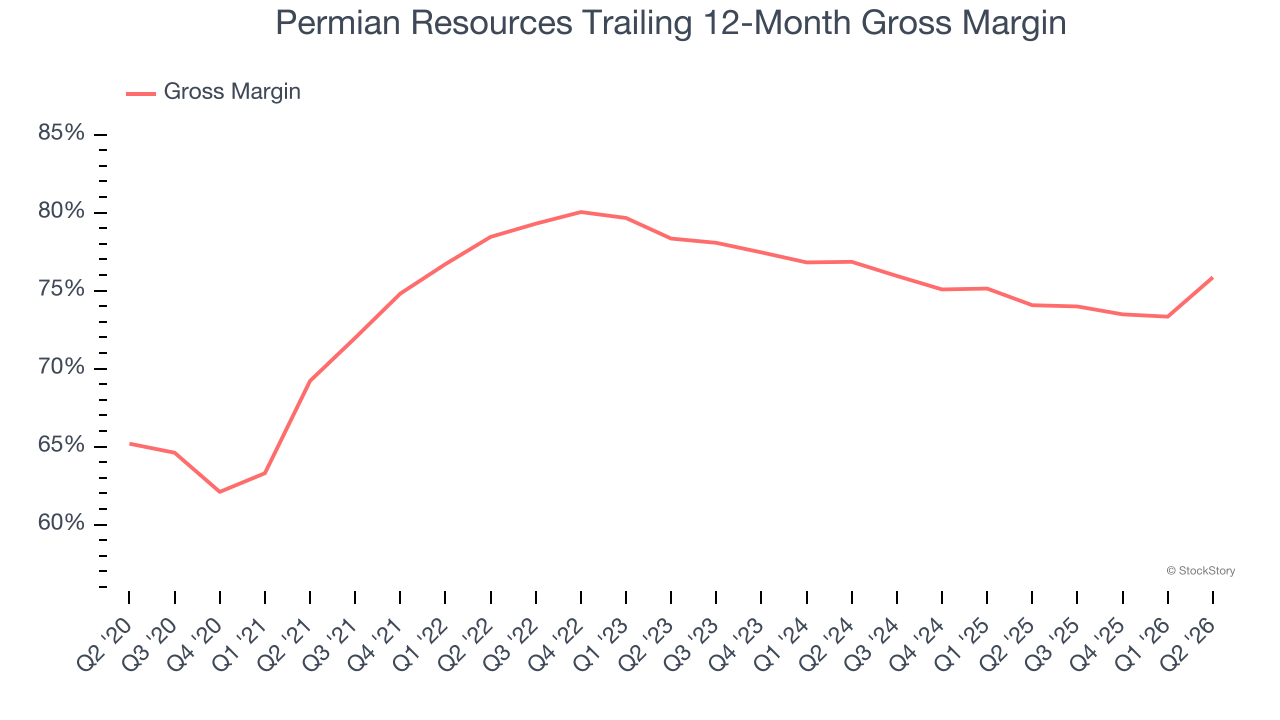
While energy gross margins can be distorted by commodity prices, hedging, and short-term cost swings, sustained margins across a full cycle reflect a producer’s underlying asset quality, infrastructure position, and cost structure.
Permian Resources, which averaged 76.1% gross margin over the last five years, exhibits enviable unit economics in the sector. It means the company will remain profitable at lower commodity prices than peers with inferior gross margins and serves as an advantaged starting point for ultimate operating profits and free cash flow generation.
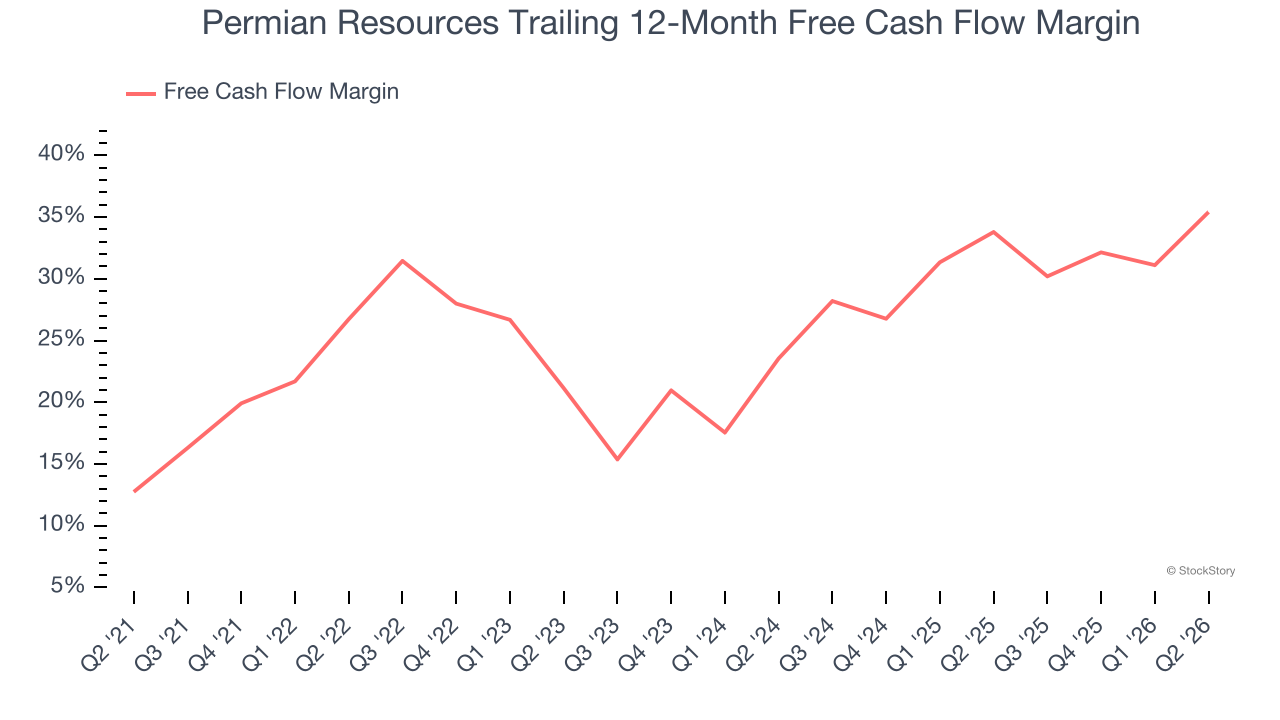
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Permian Resources has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 29.7% over the last five years.
Final Judgment
These are just a few reasons why we’re bullish on Permian Resources. With its shares lagging the market recently, the stock trades at 9.6× forward P/E (or $21.37 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.