
Egg company Cal-Maine Foods (NASDAQ: CALM) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), with sales falling 41.5% year on year to $539.6 million. Its GAAP loss of $1.26 per share was 63.1% below analysts’ consensus estimates.
Is now the time to buy Cal-Maine? Find out by accessing our full research report, it’s free.
Cal-Maine (CALM) Q3 CY2026 Highlights:
- Revenue: $539.6 million vs analyst estimates of $561.7 million (41.5% year-on-year decline, 3.9% miss)
- EPS (GAAP): -$1.26 vs analyst expectations of -$0.77 (63.1% miss)
- Operating Margin: -15.2%, down from 26.2% in the same quarter last year
- Market Capitalization: $3.22 billion
Mr. Miller commented, “Looking ahead, there are two important timing dynamics: when the conventional shell egg market begins to rebalance and when our investments in Prepared Foods translate into greater earnings contribution. We cannot precisely predict the first, but we have considerably greater visibility into the second. Current earnings reflect a difficult point in the commodity cycle while we are simultaneously investing ahead of growth, and we do not believe that fully reflects the through-cycle earnings power we are building. With a strong balance sheet, more than 60% planned growth in Prepared Foods capacity through the first half of fiscal 2028, and continued opportunities across Specialty Shell Eggs, we are well positioned to invest through the cycle and build a more diversified and durable earnings profile.”
Company Overview
Known for brands such as Egg-Land’s Best and Land O’ Lakes, Cal-Maine (NASDAQ: CALM) produces, packages, and distributes eggs.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $2.53 billion in revenue over the past 12 months, Cal-Maine carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
As you can see below, Cal-Maine struggled to generate demand over the last three years. Its sales dropped by 5% annually, a poor baseline for our analysis.
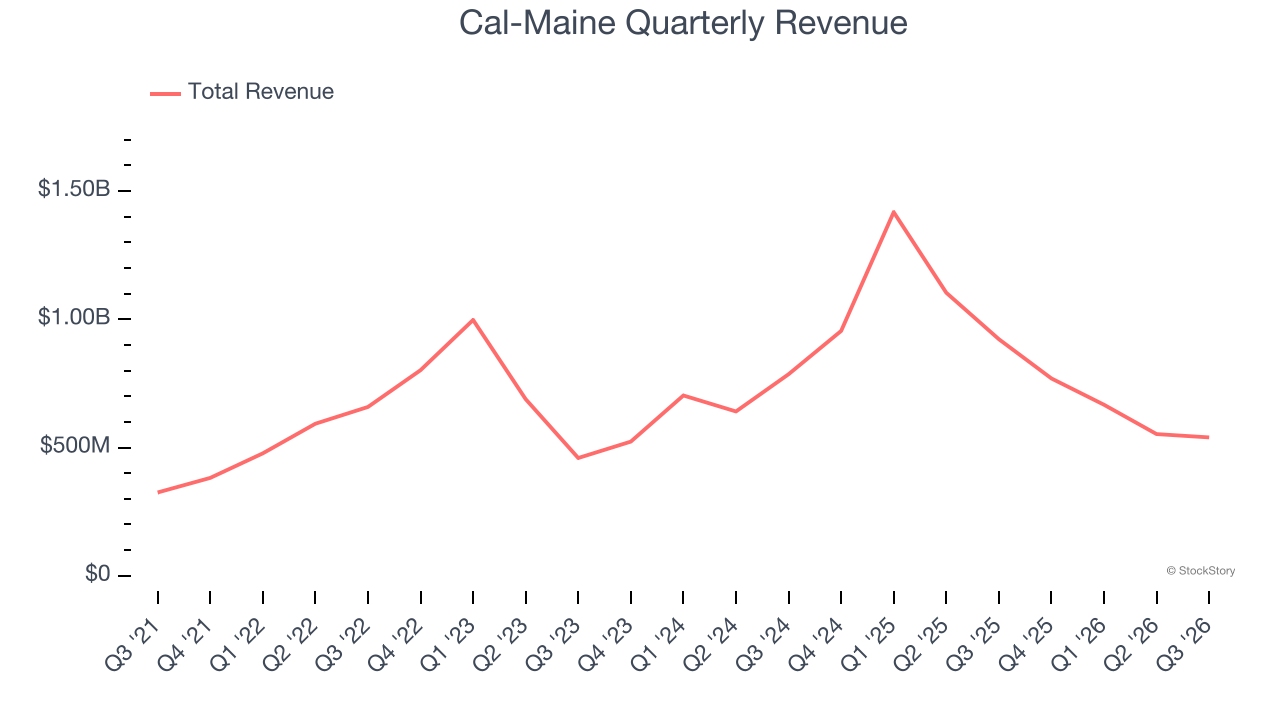
This quarter, Cal-Maine missed Wall Street’s estimates and reported a rather uninspiring 41.5% year-on-year revenue decline, generating $539.6 million of revenue.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months. While this projection implies its newer products will catalyze better top-line performance, it is still below the sector average.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Cash Is King
Although earnings are undoubtedly valuable for assessing company performance, we believe cash is king because you can’t use accounting profits to pay the bills.
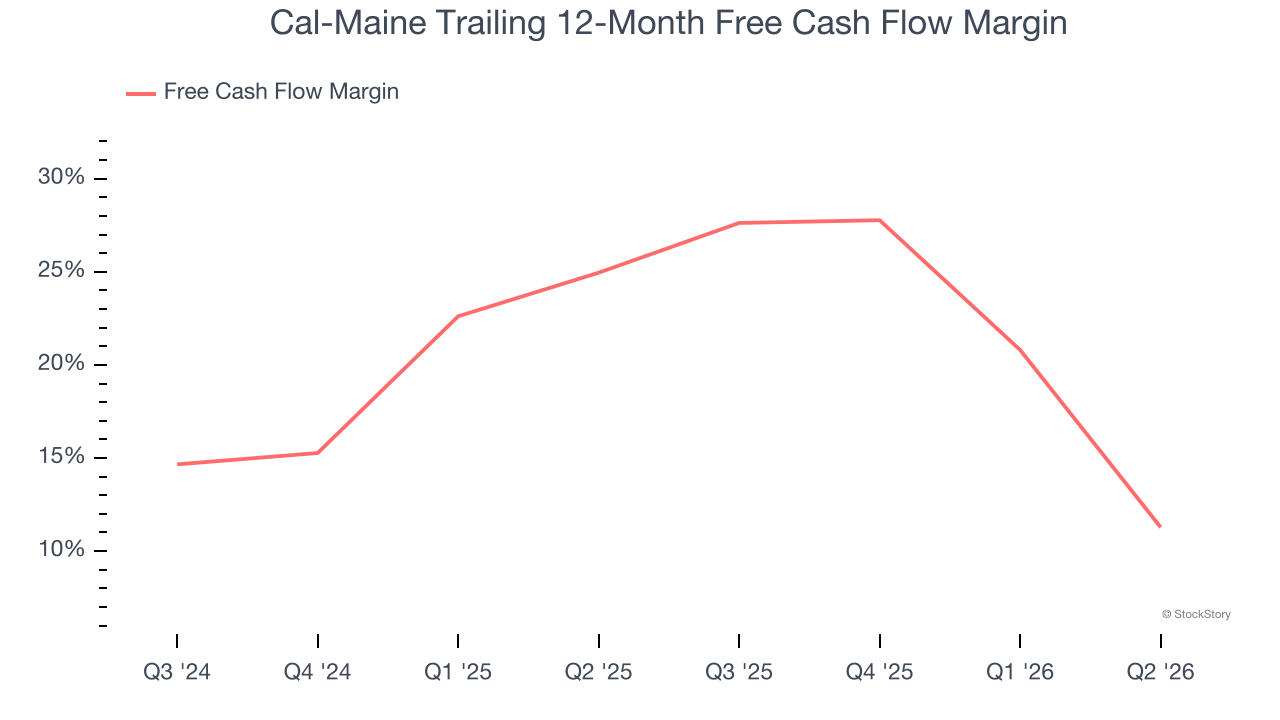
Cal-Maine has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 20.5% over the last two years.
Key Takeaways from Cal-Maine’s Q3 Results
We struggled to find many positives in these results. Its gross margin missed and its EPS fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock traded down 6% to $64.41 immediately following the results.
The latest quarter from Cal-Maine’s wasn’t that good. One earnings report doesn’t define a company’s quality, though, so let’s explore whether the stock is a buy at the current price. We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).